

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Preformed Firestop Market to Hit $1.7B by 2032, Growing at 7.15% CAGR

Strategic Intelligence for the Preformed Firestop Devices Market: Navigating the 2026 Decision Landscape
The global built environment is undergoing a fundamental shift in how passive fire protection is specified, installed, and verified. As construction methodologies accelerate and regulatory expectations tighten, preformed firestop devices have moved from convenience products to critical compliance infrastructure. Our newly released Worldwide Preformed Firestop Devices Market report is designed to give executives, purchasing leaders, and strategy teams a clear, actionable view of where this market is heading through 2032.
Worldwide Preformed Firestop Devices Market
This market has demonstrated consistent momentum over the past half-decade. From a base of nearly 745 million USD in 2020, worldwide revenue climbed steadily to approximately 1,006 million USD by 2024 and reached an estimated 1,050 million USD in 2025. The forward trajectory suggests a compound annual growth rate of 7.15 percent across the 2026 to 2032 forecast window, with market value projected to approach 1,703 million USD by the end of the period. These are not abstract figures. They reflect sustained procurement activity, specification shifts, and the gradual replacement of labor-intensive field-applied methods with engineered preformed alternatives. For decision-makers planning budgets, capacity, and competitive positioning in 2026, understanding the shape of this growth is no longer optional.
Why 2026 Is a Strategic Inflection Point
Several forces are converging at once. Building codes and international standards continue to emphasize tested, listed through-penetration systems that meet rigorous fire containment requirements. At the same time, project timelines are compressing, labor availability remains constrained in many regions, and owners are demanding faster inspections and fewer installation errors. Preformed devices address all three pressures simultaneously by offering repeatable geometries, pre-engineered fire ratings, and simplified hand-off between trades.
The market response has been visible in the product portfolios of leading manufacturers, who are expanding high-capacity pathways, modular sleeve systems, and blocks designed for rapid placement. Our report places these product moves in context, showing how innovation cycles align with specification trends rather than operating in isolation. Instead of chasing headlines, the analysis ties product launches, standard revisions, and procurement patterns into a single strategic narrative that procurement and engineering leaders can use immediately.
What the Report Delivers: Operational Depth Over Surface-Level Charts
Market size is only the starting point. The study is built around decision-useful content that translates market structure into operational insight. Readers will find a detailed segmentation framework covering product types, end-use environments, and regional demand structures, all mapped to the 2020 through 2025 historical period and extended across the 2026 to 2032 forecast horizon.
The report breaks down the preformed device landscape across multiple product architectures, including firestop blocks and plugs, cast-in devices, firestop sleeves, firestop pillows and bricks, and other preformed device categories. Rather than presenting numbers in isolation, the analysis explains how these categories compete for specification share, where installation advantages drive repeat purchasing, and which product families are gaining traction in retrofit versus new construction scenarios.
End-use coverage is equally practical. The study examines commercial buildings, industrial and power plant environments, data centers, and residential buildings, highlighting how firestopping requirements differ by occupancy type, cable density, penetraton complexity, and inspection cadence. This end-user lens helps teams anticipate where specification pressure will intensify and where supply chain readiness will matter most.
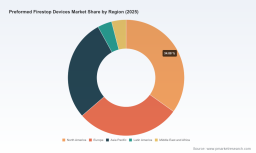
Regional coverage spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report does not merely distribute share percentages; it interprets demand polarity, code-driven pull, and project pipeline characteristics that shape procurement timing in each geography. For multinational manufacturers and distributors, this provides a basis for prioritizing market-entry sequencing, inventory positioning, and partner selection without relying on generic regional assumptions.
In addition to segmentation, the study incorporates competitive intensity metrics that reveal how consolidated the market remains. The top three competitors account for roughly 42.5 percent of market revenue, while the top five reach approximately 58.8 percent. That concentration matters because it indicates where pricing power, specification relationships, and technical support capacity are likely to be concentrated. The report uses this structure to explain which firms are scaling through broad portfolios, which are winning through specialization, and where white space may still exist for targeted growth strategies.
Competitive Landscape: Who Is Shaping the Market and How
The competitive set in preformed firestop devices is defined by a blend of broad-line fire protection portfolios and specialized device manufacturers. Our analysis profiles the companies that consistently appear in specification documents, distribution channels, and major project bid packages, then interprets what their positioning means for buyers and rivals alike.
Specified Technologies Inc., known commercially as STI Firestop, operates from Somerville, New Jersey and has established itself as a global leader in preformed pass-through devices. Its EZ-Path family, including high-capacity options such as the Series 84+, is designed for cable penetrations in walls and floors, with particular relevance for data-intensive environments. The company also provides perimeter fire barrier systems and related preformed components for through-penetration applications. Recent activity underscores a focus on capacity and digital infrastructure demand: in November 2025, STI unveiled the EZ Path Series 84+ Fire-Rated Pathway, which delivers what the company describes as the industry's largest cable capacity for high-demand data center and digital infrastructure applications. The solution was subsequently featured at the 2026 PDC Summit in February, and an additional member of the EZ Path family was introduced in late 2024 with activity referenced into 2025. For strategy teams, this signals a deliberate push toward high-density cabling environments where installers need both volume capacity and tested compliance.
Hilti Group, headquartered in Schaan, Liechtenstein, takes a different but equally influential approach. Its preformed offerings include cast-in firestop sleeves such as the CFS-CID series for pipes, firestop speed sleeves, modular fire sleeves from the CFS-MSL series, and gangplate systems designed to simplify installation and inspection of cable and pipe penetrations. In May 2025, Hilti highlighted preformed firestop solutions such as firestop blocks for easier installation and compliance with fire resistance standards. The company's emphasis on installation efficiency and inspection-friendly design aligns with a broader industry pivot toward prefabricated components that reduce on-site variability. This matters for buyers evaluating total installation cost rather than unit price alone.
3M Company, based in St. Paul, Minnesota, contributes through through-penetration firestop solutions that include preformed Fire Barrier Electrical Box Inserts and Tuck-In Wrap Strips. These products leverage intumescent Hyper-GS technology for fire, smoke, and gas containment in walls and floors. 3M's presence illustrates how material science and device design intersect in the preformed category, especially where combustible smoke control and gas leakage prevention are part of the specification conversation.
Firestop Sealants Market
Unique Firestop Products, Inc., operating from Robertsdale, Alabama, concentrates on firestop products for data cables and wires in firewalls. Its preformed split sleeve systems, including the SSS-1, are oriented to both new and retrofit construction and focus exclusively on cable firestopping. That narrow specialization can be a strategic advantage in projects where cable management is the dominant penetration challenge, and it also demonstrates how focused portfolios can earn strong specification loyalty in targeted segments.
HoldRite, operating under the RWC brand in the United States, offers UL-listed cast-in-place firestop sleeves and HydroFlame firestop systems that provide barriers against fire, smoke, gas, and water for pipe and penetration applications. The inclusion of water barrier performance in certain systems broadens the value proposition beyond fire resistance alone, which is increasingly relevant in mixed-service penetrations where multiple containment objectives must be met in a single assembly.
Additional players round out the competitive picture. RectorSeal Corporation, now part of CSW Industrials, Inc., remains an active provider of firestop solutions, including preformed devices within a broader fire protection portfolio for construction penetrations. Etex Group, based in Belgium, offers preformed firestop devices through its building materials portfolio with a focus on passive fire protection in infrastructure and commercial projects. Together, these firms show that preformed devices are not supplied by a single type of company; they emerge from both purpose-built firestop specialists and larger building-material platforms, each with distinct channel advantages and specification pathways.
Industry Dynamics Shaping Demand and Execution
The growth trajectory is supported by more than product launches. Several structural dynamics are redefining how preformed firestop devices are specified and deployed.
Standards and testing requirements continue to anchor the market. Preformed firestop devices and systems for through-penetrations must comply with ASTM E814 and UL 1479 testing standards as referenced in the International Building Code for fire containment. This compliance architecture creates a high barrier to casual entry and rewards manufacturers that can demonstrate tested performance across a wide range of wall, floor, and penetration conditions. It also gives specifiers a clear basis forcomparing devices beyond aesthetics or price.
Quality assurance frameworks are evolving in parallel. The FM 4991 Standard for the Approval of Firestop Contractors, developed in collaboration with the Firestop Contractors International Association and FM Approvals, serves as an international quality benchmark widely specified in master specifications for firestop installations including preformed devices. As project owners and engineers increasingly reference such standards in bid documentation, installation partners and product suppliers alike are pushed toward more consistent performance, documentation, and traceability.
Material economics also influence cost planning. Mineral wool, a core component in many firestop boards, plugs, and composite preformed devices, had a US Producer Price Index of 278.425 in March 2026 for industrial applications. While raw material indices fluctuate, persistent input cost attention affects manufacturer pricing strategies, margin management, and the relative attractiveness of preformed designs that reduce waste and labor compared with field-mixed alternatives.
Construction practice trends reinforce the strategic case for preformed solutions. There is increasing emphasis on prefabricated and preformed firestop solutions in mass timber and modern construction to simplify installation, reduce errors, and accelerate inspections while meeting stringent fire safety and energy efficiency requirements. This trend is not limited to any one region or building type. It reflects a broader operational preference for components that behave predictably in the field, support prefabrication workflows, and reduce the risk of post-installation remediation.
How to Use This Research for 2026 Decision-Making
The report is structured to support several recurring executive decisions. Procurement leaders can use the segmentation and forecast content to align purchase planning with anticipated specification volume by product family and end use. Commercial and business development teams can use the competitive profiles and concentration metrics to identify where supplier relationships are most concentrated and where alternative sourcing or partnership strategies may create leverage.
For manufacturers and distributors evaluating capacity expansion, the analysis offers context on which device categories are positioned for sustained demand and which end-use environments are likely to generate repeat specification activity. For investors and strategy functions, the combination of historical growth, concentration data, and dynamic drivers provides a framework for assessing whether current market participants are competing on installation efficiency, testing breadth, portfolio breadth, or specialized application focus.
Importantly, the study also helps teams separate temporary product-cycle noise from durable demand drivers. Not every launch or promotion has the same strategic weight. By mapping product introductions to the standards, construction practices, and end-use pressures that actually govern specification behavior, the report gives readers a more reliable basis for prioritizing attention in 2026.
What Remains Inside the Full Report
This introduction is deliberately designed to demonstrate analytical rigor while preserving the granular intelligence that justifies the full study. The complete report contains detailed segmentation values, regional and end-user demand structures, product-type comparisons, concentration analysis, and company-specific assessments that cannot be fully reproduced here without losing the decision-ready context our clients rely on.
Readers seeking the full segmentation breakdown, the detailed regional interpretation, the comprehensive competitive profiling, and the forecast mechanics that tie historical performance to the 2026 through 2032 outlook will find them in the complete market research. The aim of this overview is simple: to show that the market is large enough, dynamic enough, and specification-sensitive enough to warrant a structured, evidence-based view before major procurement, investment, or competitive decisions are locked in for the year ahead.
For organizations that need to act with confidence in 2026, the Worldwide Preformed Firestop Devices Market report provides that view. It turns broad growth signals into usable intelligence, connects competitive behavior to specification reality, and clarifies where the next wave of demand is most likely to emerge.
For detailed analysis of this topic, please visit the official page: Worldwide Preformed Firestop Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com