

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
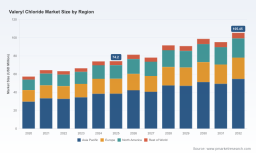
PW Consulting: Valeryl Chloride Market to Hit $105.45M by 2032, 5.15% CAGR, APAC Leads

Global Valeryl Chloride Market Intelligence: Strategic Blueprint for 2026 and Beyond
The valeryl chloride market stands at a pivotal inflection point. As a critical acylation agent in organic synthesis, this chlorinated intermediate fuels supply chains across pharmaceuticals, agrochemicals, liquid crystals, and specialty flavors. Yet, the path forward is neither linear nor uniform. Market participants navigating 2026 must reconcile volatile raw material dynamics, tightening environmental mandates, and a highly concentrated supplier ecosystem that rewards strategic foresight over reactive procurement. This analysis draws directly from our newly released Worldwide Valeryl Chloride Market Research, a comprehensive intelligence asset engineered to convert macroeconomic signals into actionable corporate strategy. The report does not merely trace historical trajectories; it constructs a decision-ready framework calibrated for the 2026–2032 window, equipping executives, procurement leaders, and market developers with the structural clarity required to allocate capital, hedge risk, and capture share in an increasingly regulated and regionally fragmented landscape.
Macro Trajectory and the 2026 Strategic Imperative
Historical performance between 2020 and 2025 reveals a market that has navigated external shocks, raw material disruptions, and shifting end-user demand with notable resilience. The trajectory demonstrates a clear recovery arc, followed by stabilization, positioning the industry for a measured but persistent expansion phase. Our baseline assessment places the 2025 valuation at the lower end of the recent growth corridor, while the 2026 projection marks a defining turning point. The compound annual growth rate across the forecast horizon settles at 5.15 percent, a figure that signals gradual maturation rather than explosive scalability. For corporate planning, this growth profile carries specific implications. It suggests that volume-driven strategies will yield diminishing marginal returns unless paired with structural efficiency gains, purity differentiation, and geographic rebalancing. Companies treating valeryl chloride as a commoditized input will face margin compression, while those aligning procurement, synthesis capabilities, and compliance infrastructure with long-term demand curves will secure disproportionate competitive leverage.
Importantly, the forecast window is not a straight line. The data reflects periods of recalibration where supply constraints, regulatory adjustments, and end-market substitution temporarily reshape velocity. These inflection zones are precisely where strategic agility separates market leaders from followers. Organizations prepared to interpret volatility as a signal rather than a disruption will reposition sourcing contracts, optimize inventory buffers, and adjust capacity commitments ahead of broader market recognition. The research underscores that 2026 is less about chasing headline growth and more about mapping the structural forces that will define value creation over the next seven years.
Structural Architecture: Purity, Applications, and Regional Allocation
Beneath the aggregate trajectory lies a multidimensional demand architecture that rewards granular understanding. The research dissects consumption patterns across purity specifications, end-use applications, and geographic distribution, revealing where margin profiles, technical requirements, and competitive intensity diverge. The purity segment illustrates a market that increasingly rewards specification precision. Higher-grade material commands distinct procurement behavior, driven by pharmaceutical and fine chemical applications where consistency, residue limits, and downstream synthesis reliability dictate purchasing decisions. Lower-purity streams serve cost-sensitive and bulk industrial pathways, but their strategic relevance is often underestimated. Mapping the interplay between these grades allows companies to evaluate whether they should compete on volume efficiency, technical differentiation, or hybrid service models that bundle specification assurance with flexible logistics.
Application-level demand further clarifies where valeryl chloride functions as a mission-critical intermediate rather than a interchangeable commodity. Pharmaceutical synthesis, agrochemical formulation, and specialty fragrance and flavor production each impose unique technical, regulatory, and supply continuity requirements. The research examines how these application clusters influence order sizing, qualification cycles, validation costs, and supplier relationship durability. Companies that map their exposure across these verticals can identify concentration risk, prioritize qualification investments, and align production or sourcing strategies with the most defensible demand pools. Regional allocation completes the structural picture. The Asia Pacific corridor carries the largest share of total market activity, reflecting established manufacturing density, active intermediate trade, and proximity to high-volume formulation hubs. Europe and North America operate with different supply chain architectures, shaped by localized compliance burdens, import dependency patterns, and distinct quality expectations. The rest of the world represents a smaller but strategically evolving footprint, where emerging procurement networks, capacity migration, and regulatory harmonization efforts gradually reshape sourcing logic. The research refrains from presenting regional splits as static map coordinates; instead, it treats them as dynamic vectors influenced by trade policy, freight economics, local manufacturing investment, and compliance-driven substitution. Understanding these vectors enables executives to evaluate where nearshoring, diversification, or long-term supplier partnerships will yield the highest risk-adjusted returns.
Worldwide ¦Ä-Valerolactone Market
Competitive Dynamics and the Concentrated Supplier Ecosystem
The valeryl chloride market is characterized by a concentrated supplier base, with the top three participants commanding a combined share of approximately 56.4 percent and the top five extending that influence to 74.15 percent. This concentration shapes pricing behavior, capacity utilization, technical service expectations, and negotiation leverage across the value chain. Rather than a fragmented commodity marketplace, the industry functions as a curated supplier network where scale, formulation expertise, regulatory readiness, and reliability often matter more than headline pricing alone.
Several established manufacturers anchor the competitive landscape, each with distinct positioning that reflects regional strengths and application specialization. Fengchen Group Co., Ltd., headquartered in Qingdao, operates as a producer and supplier of valeryl chloride serving pharmaceutical, pesticide, and liquid crystal synthesis pathways. NINGBO INNO PHARMCHEM CO.,LTD., based in Ningbo, positions itself around pharmaceutical intermediates and agrochemical inputs, offering custom synthesis and contract manufacturing capabilities tailored to specific downstream requirements. In the United States, VanDeMark Chemical supplies specialty-grade valeryl chloride with defined purity thresholds and packaging specifications that align with stringent organic synthesis and handling protocols. In India, multiple manufacturers, including Shital Chemical, Shree Sulphuric Private Limited, and Simson Pharma Limited, contribute to the supplier ecosystem with varying emphases on pharmaceutical intermediates, export-oriented supply, and research-grade material provision. The competitive implications of this landscape are significant. Buyers in highly regulated or technically demanding segments often prioritize suppliers that can demonstrate consistent specification control, documentation rigor, and responsive technical support. At the same time, supply diversification becomes a strategic necessity, not merely a contingency plan, as concentration heightens exposure to production disruptions, regulatory changes, or regional logistics constraints. The research evaluates how these players differentiate through service models, purity assurance, packaging standards, and regional footprint, while also examining where consolidation pressure, capacity expansion, or application-specific specialization may reshape competitive rankings over the forecast period.
Regulatory Friction, Raw Material Sensitivity, and Operational Resilience
Market performance in valeryl chloride is inseparable from the operational environment in which it is produced, transported, and consumed. Regulatory frameworks impose material compliance obligations across the production lifecycle. Handling, storage, disposal, and emissions control for chlorinated compounds are subject to stringent environmental and safety requirements, with European REACH regulations serving as a prominent example of compliance regimes that elevate operating costs and documentation complexity. These obligations are not peripheral; they influence facility design, product handling protocols, export eligibility, and the cost structure of competing suppliers across jurisdictions. Companies that internalize compliance as a strategic capability rather than a cost center are better positioned to maintain supply continuity, negotiate favorable terms, and avoid disruption during audit cycles or regulatory updates.
On the input side, pricing behavior remains sensitive to raw material availability and cost dynamics, particularly the supply and pricing of n-valeric acid and the reagents used in chlorination processes. Because valeryl chloride is primarily synthesized through chlorination pathways involving reagents such as thionyl chloride or phosphorus trichloride, production economics are tightly coupled to chemical feedstock markets, process efficiency, and waste management costs. This sensitivity requires procurement teams and production planners to monitor upstream indicators, evaluate alternative sourcing routes, and design contract structures that account for input volatility without sacrificing supply reliability. Operational handling also introduces practical constraints that affect logistics and storage strategy. As a corrosive and flammable material with specific flash point characteristics, valeryl chloride demands controlled packaging, stability monitoring, and handling protocols designed to mitigate hydrolysis and migration risks during transit and storage. Packaging choices, drum specifications, and storage conditions therefore become part of the total cost and risk equation, influencing freight planning, warehouse requirements, and downstream acceptance criteria. The research integrates these dynamics into a practical risk framework, enabling organizations to stress-test supply chains against regulatory shifts, raw material shocks, and logistics constraints before they escalate into operational disruptions.
Inside the Research: What the Report Delivers for Execution Teams
The Worldwide Valeryl Chloride Market Research is structured to support execution-level decision-making rather than abstract market commentary. It combines historical reconstruction with forward-looking scenario analysis, allowing readers to trace how past demand cycles, supply adjustments, and regulatory interventions inform the forecast architecture. The report maps market sizing and growth pathways across the full historical and forecast horizon, embedding the compound growth trajectory within a context of periodic recalibration rather than linear projection. It examines segmentation logic across purity grades, application clusters, and geographic corridors, with the intent of clarifying where technical requirements, purchasing behavior, and competitive intensity diverge.
The competitive section profiles key participants, evaluates differentiation levers, and assesses how concentration, regional footprint, and service models influence supplier selection and negotiation positioning. Beyond profiling, the research provides analytical tools for evaluating supplier risk, identifying qualification priorities, and aligning sourcing strategies with end-use reliability requirements. Operational and regulatory considerations are treated as integral market drivers, with examination of compliance cost implications, input sensitivity, handling and packaging constraints, and the strategic importance of supply continuity in regulated environments. For procurement, R&D, and commercial teams, the report is designed to answer practical questions: where demand is structurally expanding, which purity and application pathways offer the strongest defensible margins, how regional dynamics alter sourcing options, and what operational capabilities separate resilient suppliers from vulnerable ones. The objective is to convert intelligence into action, enabling stakeholders to refine forecasting models, negotiate with greater structural awareness, and build supply strategies that remain effective through changing regulatory and input conditions.
Strategic Positioning for 2026 and the Road to 2032
As organizations enter the 2026 planning cycle, valeryl chloride market strategy must move beyond single-variable assumptions. Growth will accrue to companies that combine specification discipline with supply resilience, that read regional dynamics as actionable intelligence rather than background noise, and that treat compliance and handling requirements as competitive infrastructure. The forecast horizon offers room for measured expansion, but it also amplifies the consequences of operational fragility, over-concentration, and reactive procurement. Market leaders will be those who integrate demand signals, input economics, regulatory exposure, and supplier capabilities into a coherent strategic framework before volatility forces reactive adjustment. Our research is built to support that transition, providing the structural clarity needed to allocate resources, manage risk, and position for durable advantage across the forecast window.
Access the Complete Market Intelligence
This overview establishes the strategic contours of the worldwide valeryl chloride market and demonstrates the analytical rigor embedded in our latest research. To support precise corporate planning, the full report delivers the comprehensive segmentation analysis, detailed competitive profiling, regional supply-architecture evaluation, regulatory impact mapping, and forecast scenario modeling required for execution-level decision-making. The macro trajectory, concentration structure, and operational dynamics described here represent only the strategic surface layer. The complete intelligence set contains the depth, granularity, and methodological transparency that procurement leaders, commercial strategists, and market developers need to translate insight into actionable plans. Access the full Worldwide Valeryl Chloride Market Research to secure the complete dataset, scenario frameworks, and vendor-level analysis necessary to navigate 2026 with confidence and build supply strategies that hold their value through the remainder of the decade.
Worldwide Valeryl Chloride Market
For detailed analysis of this topic, please visit the official page: Worldwide Valeryl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com