

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Isononyl Alcohol Market to Hit $2.19B by 2032, Driven by 5.55% CAGR

Strategic Outlook: Navigating the Isononyl Alcohol Market Through 2032
The global chemical industry stands at a critical inflection point, where foundational intermediates like Isononyl Alcohol (INA) are experiencing renewed strategic importance amidst evolving regulatory landscapes and shifting demand centers. As enterprises plan for the 2026-to-2032 horizon, understanding the trajectory of this specialty chemical market is not merely an operational necessity but a core component of long-range capital allocation and supply chain resilience. PW Consulting presents this deep-dive analysis to equip stakeholders with the intelligence required to navigate the coming cycle of growth, consolidation, and technological transformation.
Market Trajectory Overview: A Story of Resilient Growth
The Isononyl Alcohol market has demonstrated consistent expansion over the past five years, establishing a robust baseline entering the forecast period. From a market valuation of approximately 1,200 million USD in 2020, the sector has climbed steadily to reach an estimated 1,500 million USD in 2025. This historical momentum sets the stage for a forecast period that projects continued appreciation, with market size expected to expand from roughly 1,565 million USD in 2026 to over 2,185 million USD by 2032.
This growth trajectory reflects a compound annual growth rate of 5.55 percent, signaling a healthy expansion pace that outpaces many general chemical segments. Such performance is underpinned by the material's entrenched role as a critical precursor in high-volume applications, particularly within the plastics and coatings industries. However, the aggregate figures only tell part of the story. The distribution of this growth is uneven across geographies and production methodologies, creating pockets of opportunity and risk that require granular understanding. For decision-makers, the challenge lies in distinguishing between cyclical demand fluctuations and structural shifts in how INA is produced, sourced, and utilized globally.
Core Applications and Consumption Drivers
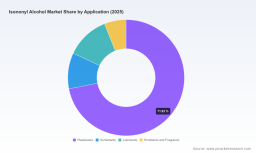
Demand for Isononyl Alcohol is fundamentally tied to its downstream utility, with the market anchored by several key application verticals. The largest share of consumption continues to flow into the plasticizers segment, where INA serves as an essential building block for phthalate and non-phthalate ester plasticizers used in flexible PVC applications. This sector benefits from sustained demand in construction, automotive interiors, and medical tubing, though it faces concurrent pressure from regulatory shifts favoring non-phthalate alternatives. Beyond plasticizers, the market supports more specialized consumption streams.
Isononanoic Acid Market
Surfactants and lubricants represent distinct growth avenues, leveraging INA's fatty alcohol characteristics for industrial cleaning formulations and high-performance lubricating esters. Meanwhile, the emollients and fragrance segment utilizes higher-purity grades of INA in personal care and specialty chemical formulations. Each of these application vectors responds differently to macroeconomic conditions, raw material cost volatility, and regional industrialization rates. The interplay between these segments creates a complex demand matrix where a slowdown in one vertical can be partially offset by acceleration in another, providing a degree of natural hedging for diversified producers. For corporate strategists, mapping exposure across these application lines and understanding their respective growth elasticities is essential for scenario planning.
Regional Dynamics and Supply Chain Architecture
The geographic footprint of Isononyl Alcohol consumption and production reflects the broader realignment of global chemical manufacturing capacity. Asia Pacific has emerged as a dominant region in terms of market activity, driven by industrialization, expanding PVC processing industries, and the establishment of large-scale production facilities within the region. North America and Europe maintain significant market presence, supported by mature downstream demand and stringent regulatory frameworks that shape product specifications and sourcing preferences. Latin America and the Middle East and Africa contribute incremental demand, often influenced by infrastructure development cycles and local manufacturing capabilities.
On the supply side, the production of Isononyl Alcohol is concentrated among a set of integrated chemical manufacturers capable of executing complex oxo synthesis processes. Two primary production methodologies define the supply architecture: the C4 Chemicals Process pathway and the ExxonMobil Process variant. Each route carries distinct technical considerations regarding feedstock flexibility, yield characteristics, purity profiles, and environmental footprint. Producers must balance these technical trade-offs against capital investment requirements and regional feedstock availability. The concentration of global market share among the top firms underscores the capital-intensive nature of oxo alcohol production, creating high barriers to entry and fostering strategic partnerships that span technology licensing, feedstock supply, and distribution networks. Understanding the geographic dispersion of these production assets and the logistics implications for end-users is a key component of supply chain risk management.
Competitive Landscape and Strategic Positioning
The competitive environment in the Isononyl Alcohol market is shaped by a cohort of established chemical firms, each with distinct portfolios, technological heritage, and regional strengths. Evonik Industries AG maintains a significant position through its production site in Marl, Germany, where it manufactures Isononanol as a C9 oxo alcohol primarily serving plasticizer and surfactant applications via hydroformylation of C8 olefins. Evonik has also pursued sustainability certifications, including ISCC PLUS certification for its INA production site, signaling alignment with circular economy standards and sustainable sourcing expectations.
BASF SE stands as a major player, supplying Isononanol through a combination of partner arrangements, including collaboration with PETRONAS, and its own manufacturing facilities. BASF's role as a key supplier for plasticizer applications is reinforced by ongoing regulatory engagement, with REACH registration documentation confirming compliance for production and use within European jurisdictions. OXEA GmbH operates as a leading oxo intermediates producer, distributing Isononanol grades worldwide for both plasticizer and specialty chemical applications, leveraging its reputation for quality and reliability in the oxo alcohol segment.
ExxonMobil Chemical Company contributes to the supply base through its production facility at the Baytown complex, where Isononanol is generated via the Exxon oxo process. This capacity supports high-purity plasticizer applications, including DINP, catering to customers with stringent technical specifications. Eastman Chemical Company supplies Isononanol for specialty esters and non-phthalate plasticizer formulations, serving North American and global markets with a focus on alternative plasticizer solutions that respond to evolving regulatory preferences.
Isononyl Alcohol Market
LG Chem Ltd. operates an integrated production capability at its Daesan Complex in South Korea, producing Isononanol for PVC plasticizers and serving Asian export markets. This regional production base positions LG Chem to capture demand growth in East Asia while benefiting from integrated logistics and feedstock access. Perstorp AB offers Isononanol within its broader C8-C10 oxo alcohol portfolio, with recent activities including the product launch at its Pengerang Integrated Complex in Malaysia, expanding its geographic reach in Southeast Asia. Mitsubishi Chemical Corporation supplies Isononanol through licensed oxo processes, emphasizing high-purity grades tailored for electronics and automotive applications, where material consistency and performance are paramount. Sasol Limited rounds out the competitive set, producing Isononanol as part of its oxo alcohol portfolio for plasticizer and surfactant uses, drawing on its extensive experience in Fischer-Tropsch and oxo chemistry.
A notable development reshaping the competitive map is the capacity expansion activity by Ningbo Refining and Chemical Co. Ltd. in China. The company has signed a technology license agreement with BASF to construct a new world-scale Isononanol production facility in Ningbo, with a target capacity of 200,000 tons per year. Commercial startup of this plant is expected in 2026, introducing significant new supply into the Asia Pacific market. This expansion signals the continued industrialization of China's chemical sector and the strategic importance of securing access to advanced oxo synthesis technology to compete on scale and quality. For existing producers, such capacity additions bring both competitive pressure and opportunities for supply diversification, depending on regional demand absorption and price dynamics.
Regulatory Environment and Sustainability Imperatives
Regulatory frameworks increasingly influence the Isononyl Alcohol market, shaping both production methods and downstream application viability. In Europe, REACH registration requirements mandate comprehensive documentation for chemicals used in industrial applications, and Isononanol is subject to these compliance obligations, particularly within the plasticizer supply chain. BASF and other producers maintain up-to-date regulatory filings to ensure uninterrupted market access. Beyond traditional chemical compliance, sustainability certifications have become a competitive differentiator. The issuance of ISCC PLUS certificates for Isononanol production sites confirms adherence to sustainable sourcing criteria and circular economy principles, addressing procurement requirements from downstream customers in sensitive sectors such as automotive, packaging, and consumer goods.
These regulatory and sustainability trends are not static; they evolve in response to broader environmental policy directions, consumer preferences, and industry-led initiatives. Producers that proactively align their operations with sustainability benchmarks and maintain robust regulatory documentation are better positioned to serve customers facing their own compliance obligations. Conversely, gaps in certification or registration can restrict market access or increase the cost of commercial engagement. For enterprises evaluating supply partnerships or contemplating market entry, the regulatory status of potential suppliers and the sustainability profile of the INA sourced should be integral to vendor qualification and risk assessment processes.
Strategic Priorities for 2026 Decision-Makers
As organizations formulate their strategies for 2026 and beyond, several focus areas merit attention for those exposed to the Isononyl Alcohol value chain. First, capacity expansion events, such as the new facility in Ningbo, require updates to supply-demand balance assessments. Markets that were previously constrained may experience relief in availability, while price dynamics could shift depending on regional demand elasticity and the pace of downstream capacity commissioning. Monitoring commissioning timelines, ramp-up rates, and initial operating performance of new assets will be critical for accurate near-term forecasting.
Second, the diversity of production processes and the concentration of market share among leading firms suggest that supply security is closely linked to supplier selection and geographic diversification. Relying on a single source or a narrow set of suppliers introduces vulnerability to operational disruptions, feedstock availability constraints, or regional policy changes. Developing a multi-sourced procurement strategy, evaluating supplier technical capabilities and financial stability, and understanding logistics corridors are foundational steps toward resilient supply management.
Third, application-side trends demand continued vigilance. The plasticizer segment, while dominant, is subject to substitution pressures and regulatory scrutiny that can alter demand patterns over time. Specialty applications in electronics, automotive, and personal care offer growth avenues but often require higher-purity grades and more rigorous quality assurance. Enterprises should assess their exposure to each application vertical, identify potential substitution risks, and explore opportunities to align product offerings with emerging market preferences, such as non-phthalate plasticizer demand or bio-based material trends.
Fourth, sustainability credentials are transitioning from optional differentiators to baseline expectations in many customer segments. Investing in sustainability reporting, exploring certification pathways, and engaging with suppliers on circular economy initiatives can enhance commercial positioning and mitigate future compliance risk. The interaction between regulatory developments, such as REACH updates, and voluntary sustainability standards creates a layered compliance landscape that benefits from proactive management.
Conclusion: Equipping Strategy with Intelligence
The Isononyl Alcohol market presents a landscape of steady growth, concentrated competitive dynamics, and evolving regulatory and sustainability requirements. The numbers indicate a market expanding from approximately 1,565 million USD in 2026 toward nearly 2,200 million USD by 2032, with a growth rate that underscores the material's enduring relevance in key industrial applications. Yet, the strategic implications extend far beyond these headline figures. Opportunities and risks are distributed across regions, processes, applications, and supplier relationships, demanding a nuanced understanding that aggregates cannot provide.
PW Consulting's comprehensive Isononyl Alcohol Market Research report is designed to fill that gap. The study delivers detailed segmentation analysis, granular regional and application-level assessments, and in-depth competitive profiling that goes beyond the overview presented here. It examines supply chain structures, tracks recent developments and capacity announcements, evaluates regulatory and sustainability trends, and provides scenario-based insights to support decision-making under uncertainty. For executives, procurement leaders, investors, and strategic planners, the full report offers the actionable intelligence needed to shape sourcing strategies, assess market entry viability, benchmark performance, and anticipate the shifts that will define the 2026-to-2032 period.
To access the complete analysis and unlock the full scope of data-driven insights, we invite you to explore the full report. The detailed intelligence contained within is structured to support confident, forward-looking decisions in a market where precision in understanding translates directly into competitive advantage.
For detailed analysis of this topic, please visit the official page: Isononyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com