

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bovine Lactoferrin Market Hits $565.08M in 2025, Driven by Asia Pacific

Navigating the Bovine Lactoferrin Market: Strategic Intelligence for 2026 and Beyond
The global bovine lactoferrin market stands at a critical inflection point. As demand for bioactive dairy proteins accelerates across infant nutrition, dietary supplements, and pharmaceutical applications, stakeholders require more than headline figures. They need a granular, forward-looking view of supply constraints, regulatory shifts, and competitive positioning. Our latest market research delivers precisely that intelligence, equipping leadership teams with the analytical rigor required to make confident capital allocation, product development, and partnership decisions throughout the 2026 to 2032 forecast horizon.
This report is engineered as a strategic compass. It translates historical trajectory, forward-looking projections, and on-the-ground industry signals into actionable frameworks. Decision-makers will find a structured assessment of market concentration, segmentation dynamics, production technology pathways, and the evolving regulatory landscape that will dictate commercial viability in key end-use sectors.
Bovine Colostrum Market
Market Trajectory and Structural Foundations
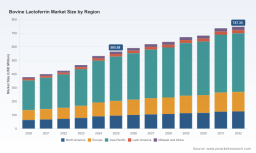
Historical performance from 2020 through the base year of 2025 demonstrates a consistent upward trajectory for bovine lactoferrin, reflecting sustained procurement by high-value nutrition and health applications. The market recorded steady revenue expansion across this period, moving from a baseline in the upper three-hundred-million range to a clearly elevated position as manufacturers scaled production and end-users integrated lactoferrin into core formulations. This historical momentum establishes a robust foundation for the forecast period extending through 2032.
Looking ahead, the market is projected to continue its measured expansion, sustained by multi-year investment in extraction capacity, growing acceptance of lactoferrin in specialized nutrition, and broadening application portfolios. The forecast period highlights a compound annual growth rate that underscores steady, compounding value creation rather than speculative volatility. Revenue growth will be shaped by the interplay of production scalability, feedstock economics, and the pace at which regulatory approvals unlock new geographic and application markets. Leadership teams planning capacity investments, pricing strategies, or market entry must anchor their models to this trajectory while remaining敏锐 to the structural variables that can accelerate or decelerate realization.
The report contextualizes these projections within a framework that separates durable demand drivers from short-term cyclical noise. By mapping the evolution from historical baselines to forward estimates, the analysis enables stakeholders to stress-test assumptions, calibrate inventory strategies, and align product roadmaps with the pace of market maturation.
Segmentation Dynamics and Application Realities
Bovine lactoferrin demand is distributed across multiple application vectors, each with distinct procurement cycles, quality requirements, and margin structures. Infant formula represents a substantial and structurally resilient demand center, driven by the protein's recognized bioactive profile and its integration into premium nutrition portfolios. Dietary supplements form another critical pillar, where lactoferrin's positioning within immune and gut-health formulations continues to attract formulation scientists and brand developers. Pharmaceuticals and food and beverage applications, while smaller in absolute contribution, represent high-growth vectors where regulatory clearance and functional validation will determine the pace of adoption. Additional use cases span specialized nutrition and emerging wellness categories, providing incremental demand that compounds as formulation expertise deepens.
Production technology also shapes segment economics. The market encompasses both freeze-dried and spray-dried processing pathways, each offering different trade-offs in purity retention, solubility, bulk density, and cost structure. Freeze-dried formats appeal to applications demanding maximum bioactivity preservation and stringent quality attributes, while spray-dried variants serve high-volume dry-mix and ingredient blending workflows where handling efficiency and cost competitiveness are paramount. Understanding which processing route aligns with specific end-use requirements is essential for procurement strategy, supplier selection, and product positioning.
Geographically, demand is distributed across a diverse set of regions, reflecting different stages of market development, regulatory environments, and consumer familiarity with bioactive dairy ingredients. Some regions exhibit mature procurement infrastructures and established supplier relationships, while others are in earlier phases of adoption where education, distribution building, and regulatory alignment remain active priorities. The report examines how these regional nuances influence sourcing strategies, channel development, and the timing of commercial rollouts, without reducing complex dynamics to simplistic rankings.
Competitive Landscape and Strategic Positioning
The bovine lactoferrin market is characterized by a mix of established dairy ingredient specialists, regional producers, and technology-forward entrants. Competitive intensity is moderated by meaningful barriers to entry, including the need for specialized extraction and purification capabilities, consistent access to high-quality milk feedstock, and the operational expertise required to maintain batch-to-batch consistency at commercial scale. These factors contribute to a moderately concentrated landscape where incumbency, process know-how, and supply chain reliability carry significant weight.
Several organizations anchor the competitive field. Armor Protéines, based in France, markets Vitalarmor® Lactoferrin in its native bovine form, with organic-grade variants targeting infant nutrition and dry-mix applications. Bega Cheese Limited leverages its broader dairy ingredients portfolio to supply bovine lactoferrin, integrating production with established milk processing operations. Fonterra Co-operative Group Limited provides lactoferrin through its Ingredients business, supported by continued investment in high-value product capacity that reinforces its role as a scalable supplier. Glanbia Plc delivers lactoferrin ingredients oriented toward nutrition applications, drawing on its global position in dairy-based nutritional solutions.
In Asia Pacific, Inner Mongolia Yili Industrial Group Co., Ltd. incorporates bovine lactoferrin into its dairy ingredients lineup, aligning production with regional demand centers and growing domestic nutrition markets. Milei GmbH stands out as a high-volume producer utilizing Morinaga process technology, giving it a distinct manufacturing footprint and supply capability. Morinaga Co., Ltd. has built long-term production and supply operations through subsidiary structures, emphasizing reliability and sustained commercial relationships. Noumi Limited markets PUREnFERRIN™, an ultra-premium native bovine lactoferrin derived from Australian whey, positioning on quality and provenance. Nutriscience Innovations, LLC operates as a U.S.-based supplier of bovine lactoferrin ingredients, serving formulation and distribution networks across North America.
Saputo Inc. produces bovine lactoferrin within its specialty ingredients range, benefiting from integrated dairy operations and established customer channels. Synlait Milk Ltd and Tatua Co-Operative Dairy Company Ltd both supply lactoferrin from dairy processing operations in New Zealand, capitalizing on the country's milk quality reputation and ingredient export infrastructure. Valfoo operates Switzerland's largest lactoferrin production facility, manufacturing Swissferrin® from fresh cow's milk and emphasizing domestic processing capability and quality control. Beston Global Food Company Ltd, based in Australia, manufactures high-purity bovine lactoferrin at its Jervois dairy factory, with capabilities reaching up to 95% purity, reflecting a focus on premium-grade output.
This competitive mosaic creates distinct strategic opportunities. Buyers must evaluate suppliers not only on price but on process consistency, regulatory documentation, capacity resilience, and the ability to support co-development or custom specification requirements. Suppliers, in turn, must differentiate through quality assurance, application expertise, and the strategic framing of their production technology and feedstock advantages.
2025 to 2026 Industry Dynamics and Catalysts
Recent developments illustrate how rapidly the competitive and regulatory environment is evolving. In late 2025, All G and Armor Protéines announced a joint venture to scale production and commercialization of human and bovine lactoferrin, with All G's first bovine lactoferrin powder product launching in late 2025. This partnership signals a broader trend toward structured collaborations that pair production capability with commercialization reach. Around the same period, All G raised more than A$10 million to support commercial-scale production, with its first bovine lactoferrin product targeted for launch in the first quarter of 2026, underscoring the capital intensity and execution risk associated with scaling novel ingredient supply.
Regulatory milestones are reshaping the addressable market. In May 2025, TurtleTree received the first no-questions letter from the FDA for precision-fermented bovine lactoferrin, enabling broader food and supplement use and opening a complementary pathway alongside traditional dairy-derived supply. This development aligns with the broader FDA GRAS notice issued on May 7, 2025, covering recombinant bovine lactoferrin isolate produced by Komagataella phaffii M020. Together, these regulatory actions expand the technical and commercial options available to formulators, while also introducing strategic questions about sourcing mix, labeling, and the long-term role of fermentation-derived ingredients relative to conventional dairy extraction.
Capacity expansion remains a central theme. Beston Global Food Company Ltd expanded lactoferrin production capacity at its Jervois dairy factory in Australia to up to 25 metric tons of 95% pure lactoferrin per year, a move that directly addresses supply constraints in the premium purity segment and reflects the strategic importance of dedicated processing lines. Such expansions signal that producers are actively aligning capacity with anticipated demand rather than relying solely on incremental throughput adjustments.
Regulatory and policy developments continue to influence market access and input economics. The European Union assessed bovine lactoferrin as a food ingredient in 2025 under Novel Food regulation, with evaluation covering uses in infant formula, supplements, and sports nutrition. The outcome of such assessments will shape the pace at which new application categories open in European markets. In China, the elimination of import tariffs on dairy-based formula foods for special medical purposes, effective in late 2023 and continuing into 2025, has implications for specialized nutrition procurement and cross-border ingredient flows. At the same time, the U.S. Department of Energy invested $9.7 million in alternative protein projects, including lactoferrin, to support decarbonization of the food sector, indicating that sustainability and production efficiency are increasingly being treated as strategic policy priorities rather than peripheral considerations.
Feedstock dynamics remain a persistent operational variable. High-quality bovine milk feedstock exhibits price volatility due to seasonal variations, feed costs, and global dairy market fluctuations. This volatility directly affects production economics and underscores the importance of feedstock sourcing strategy, hedging approaches, and supplier diversification for both ingredient manufacturers and downstream buyers.
What the Report Delivers: Analytical Architecture and Practical Utility
Our research is structured to move beyond descriptive summary and into decision-grade analysis. The report provides a comprehensive market sizing framework that integrates historical data with a multi-year forecast, enabling stakeholders to understand both the magnitude of the opportunity and the pacing of growth across the forecast window. Market concentration metrics are examined to clarify the extent to which revenue is distributed among leading participants and where consolidation, partnership, or niche positioning may create advantage.
Segmentation analysis is delivered in a format designed for practical application. Rather than treating categories in isolation, the report connects type, application, and regional demand patterns to procurement behavior, formulation requirements, and supply chain risk. This integrated view helps teams evaluate where to prioritize R&D, which customer segments warrant dedicated commercial resources, and how production technology choices influence margin and market access.
The competitive analysis goes beyond corporate profiling to assess strategic posture, differentiation levers, and the implications of recent capacity and partnership moves. By placing companies within the context of production capabilities, technology pathways, and regional footprints, the report equips stakeholders to map supplier suitability, anticipate competitive responses, and identify partnership or acquisition targets aligned with specific strategic objectives.
Regulatory and policy developments are tracked and interpreted with an eye toward commercial impact. The report translates regulatory milestones, tariff changes, and assessment processes into implications for market entry timing, formulation strategy, and sourcing architecture. This ensures that compliance considerations are treated as strategic inputs rather than afterthoughts.
Scenario and sensitivity considerations are embedded throughout. Feedstock volatility, regulatory approval timelines, capacity ramp-up risk, and the emergence of alternative production pathways are all factored into the analytical framework so that leadership can stress-test plans against plausible variations in the operating environment.
Strategic Imperatives for 2026 Decision-Making
As organizations move from planning to execution in 2026, several strategic imperatives stand out. First, sourcing strategy must balance quality, capacity, and resilience. With multiple processing technologies, purity grades, and supplier archetypes available, procurement teams need a structured method for matching supply characteristics to application requirements while safeguarding against feedstock and capacity disruption.
Second, product and formulation strategy should account for the expanding range of regulatory and technological options. The convergence of dairy-derived and precision-fermentation pathways is broadening the ingredient toolkit, and companies that evaluate these options early will be better positioned to optimize cost, functionality, and market positioning.
Third, competitive strategy should be anchored in differentiation that is difficult to replicate. Process know-how, application expertise, consistent quality documentation, and the ability to support customer co-development are likely to matter as much as price in a market where performance claims and regulatory compliance carry significant weight.
Fourth, geographic and channel planning should reflect the uneven pace of adoption and regulatory readiness across regions. Markets with established procurement infrastructures may reward scale and reliability, while earlier-stage markets may require education, distribution building, and carefully sequenced regulatory engagement.
Finally, capital and partnership decisions should be informed by a clear view of where market concentration, capacity expansions, and joint ventures are reshaping supply dynamics. The recent wave of investment and collaboration activity indicates that the market is entering a phase where strategic alignment between production capability and commercialization capacity will separate scalable participants from those constrained by fragmented or under-resourced operations.
Conclusion: Turning Intelligence into Execution
The bovine lactoferrin market offers meaningful long-term opportunity, but realizing that opportunity requires more than awareness of headline growth. It demands a clear understanding of segmentation realities, competitive positioning, regulatory direction, and the operational variables that shape cost and supply continuity. Our market research is designed to provide exactly that depth, translating complex industry signals into a structured basis for sourcing, product, and partnership decisions throughout the 2026 to 2032 period.
Organizations that approach the market with rigorous segmentation analysis, a clear view of supplier capabilities, and a forward-looking stance on regulatory and technology developments will be best placed to capture value as demand broadens and production capacity matures. This report delivers the foundational intelligence needed to build those strategies with confidence, while leaving room for tailored internal modeling and scenario planning.
For decision-makers seeking the full quantification, detailed segmentation breakdowns, company-level assessments, and forward-looking scenario analysis, the complete report is available for review. The full intelligence package extends beyond the overview presented here, providing the granular data and strategic frameworks required to translate market insight into executable plans.
Bovine Lactoferrin Market
For detailed analysis of this topic, please visit the official page: Bovine Lactoferrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com