

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Wheel Balancer Market Hits $242M in 2025, Projects 4.1% CAGR to 2032

Strategic Balancing: Navigating the Wheel Balancer Market in 2026 and Beyond
The global automotive aftermarket ecosystem is undergoing a profound transformation, driven by tightening safety regulations, chronic labor shortages, and accelerating adoption of automated service equipment. Within this evolving landscape, wheel balancers have emerged as a critical node in the value chain, bridging vehicle safety compliance with operational efficiency in tire service facilities. Our latest comprehensive market research on the Wheel Balancer Market offers enterprise decision-makers a rigorous, forward-looking intelligence framework designed specifically to inform capital allocation, product development roadmaps, and competitive positioning strategies through 2032.
For executives operating in automotive service equipment, tire retail, fleet maintenance, or industrial manufacturing, the timing of this analysis is deliberate. The market has transitioned from a mature, price-driven segment into a technology-differentiated arena where precision, automation, and regulatory alignment dictate margin structures and customer retention. Understanding the underlying trajectories is no longer optional; it is a prerequisite for sustaining competitive advantage in an environment where workshop throughput, technician productivity, and safety compliance directly translate into revenue resilience.
Worldwide Wheel Balancer With Touchscreen Market
Macro Trajectory and Growth Architecture
Drawing on a consolidated historical dataset spanning 2020 through 2025, the market has demonstrated consistent expansion, culminating in a 2025 revenue baseline of 242.0 million USD. Projections extending through the 2026 to 2032 forecast horizon indicate a steady compounding trajectory, with an estimated compound annual growth rate of 4.1 percent. By the close of the forecast period, market valuations are positioned to approach 320.0 million USD. This growth profile reflects a sector that is neither undergoing explosive disruption nor facing structural contraction, but rather maturing through incremental technological upgrades, regulatory reinforcement, and regional capacity expansion.
The sustained upward momentum is fundamentally anchored in the dual pressures of vehicle safety enforcement and workshop labor economics. Mandatory periodic technical inspections under established regulatory frameworks continue to require precise wheel balancing as a non-negotiable compliance parameter. Concurrently, rising operational costs and persistent technician shortages are compelling service providers to invest in equipment that reduces cycle times and lowers labor intensity. Automation in balancing operations has therefore shifted from an optional efficiency measure to a strategic necessity, enabling facilities to maintain throughput without proportionally expanding headcount.
From a market structure perspective, concentration dynamics reveal a moderately consolidated landscape. Leading suppliers collectively command a significant share of total revenue, while the remaining portion is distributed across specialized manufacturers and regional equipment integrators. This concentration pattern suggests that scale advantages, brand recognition, and established service networks continue to differentiate veteran players, but also leaves room for targeted innovators who can address emerging demands in fleet-specific balancing, heavy-duty applications, and integrated diagnostic workflows.
Dimensioning the Opportunity Landscape
The market is structurally organized across equipment architecture, vehicle application, and geographic deployment. Each dimension carries distinct operational implications, pricing sensitivities, and adoption curves that directly influence procurement strategy and product portfolio design.
Equipment architecture represents the foundational strategic axis. Dynamic balancing systems continue to anchor the mainstream professional service segment, favored for their precision, compatibility with high-speed diagnostic routines, and alignment with standardized workshop practices. Static configurations retain relevance in specialized or budget-conscious settings, while bubble-based approaches occupy a narrower niche where manual processes and cost constraints dominate. The strategic implication is clear: procurement decisions increasingly weigh precision throughput against total cost of ownership, with automation-ready architectures capturing premium positioning as labor economics tighten.
Application segmentation further delineates demand drivers. Passenger vehicle servicing constitutes the dominant volume channel, reflecting the sheer density of light-duty fleets and the frequency of aftermarket tire maintenance. Commercial vehicle applications, while smaller in relative scale, present higher barriers to entry and greater value per installation, driven by fleet uptime requirements, heavy-duty load conditions, and specialized balancing needs. Companies that can bridge the requirements of both segments, or that can tailor solutions to one with clear differentiation, are better positioned to navigate demand volatility and expand addressable market share.
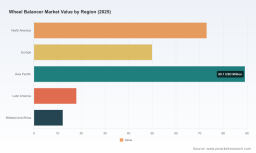
Regional distribution introduces additional complexity. North American and European markets are characterized by mature service networks, stringent safety standards, and strong aftermarket substitution demand. Asia Pacific represents a high-volume, rapidly expanding deployment zone where fleet growth, urbanization, and progressive formalization of service standards are accelerating equipment modernization. Latin American and Middle East and Africa regions operate with more variable regulatory maturity and purchasing power, yet they remain strategically relevant as diversification avenues and as channels where lightweight, cost-optimized configurations can gain traction. The strategic takeaway is that regional strategy must be calibrated to local compliance environments, labor dynamics, and the pace of workshop technology adoption rather than assumed through a uniform global template.
Competitive Architecture and Strategic Positioning
The competitive field is defined by a mix of established North American manufacturers, European engineering specialists, and broadening supply capabilities from Asia-based equipment groups. Each category brings a distinct strategic posture, product philosophy, and channel advantage that shapes market execution.
Among the most prominent incumbents, Hunter Engineering Company has reinforced its reputation through the integration of advanced diagnostic balancing with hands-off operational workflows. The introduction of the Road Force WalkAway wheel balancer, featuring an automatic hands-off inflation system, directly addresses one of the most persistent workshop bottlenecks: tire changeover time. By reducing four-tire changeover times by up to 45 percent, the solution exemplifies how automation can translate into measurable labor savings and throughput gains. Its demonstration at the SEMA Show 2025, paired with an integrated Revolution tire changer, signals a broader ecosystem strategy in which balancing equipment is increasingly positioned as part of coordinated service lines rather than isolated tools.
Coats Company LLC has carved out a strong footprint in heavy-duty and high-volume service environments. Its Direct Drive balancing platforms, including the HD-6450 and ProBalance E900 models, are engineered for durability, speed, and operational consistency in tire service operations where uptime and repeatability are paramount. The strategic value of such offerings lies in their alignment with commercial and high-throughput passenger service requirements, where equipment reliability directly affects shop scheduling and customer turnaround expectations.
Snap-on Incorporated continues to leverage its broad professional tool ecosystem by supplying motorized wheel balancers, including Sun Wheel Balancer lines and the EEWB334A model, tailored for high-volume shop use. The company's channel strength and brand trust within professional service networks provide a durable distribution advantage, particularly in markets where integrated tool procurement and service support are decisive purchasing criteria.
CEMB S.p.A. brings a European engineering perspective, emphasizing garage and truck-oriented balancing solutions with vibration analysis integration and touchless alignment compatibility. Its product direction reflects a growing convergence between balancing, alignment, and diagnostic inspection capabilities, a trend that is gaining relevance in facilities seeking to consolidate service functions and reduce equipment footprint.
IMI Products has pursued a highly targeted strategic path with the Equal FLEXX internal adaptive balancing system, designed specifically for fleet truck tires with an emphasis on vibration reduction and fuel efficiency improvements. The approval of this system by UPS for its 2026 Tire Solutions Program, following a two-year field evaluation exceeding 10,000 assemblies, illustrates the growing importance of fleet-validated performance in commercial segment decision-making. Such endorsements can materially influence procurement standards within large fleet operations and signal a shift toward evidence-based equipment selection.
Balance Group, operating from China, represents a broadening manufacturing presence that integrates wheel balancers into comprehensive tire service equipment lineups spanning car, motorcycle, truck, and heavy-duty wheels. This integrated equipment strategy enables suppliers to address broader service facility needs through bundled offerings, a model that can be especially compelling in growing markets where dealers and workshops favor consolidated procurement and after-sales support.
Beyond named incumbents, the competitive environment also reflects product innovation from other regional players. For example, the launch of new heavy-duty wheel balancer lines incorporating Tri-Sensor Technology and LCD displays underscores an ongoing industry-wide push toward improved precision, operator visibility, and workshop usability. Collectively, these developments highlight that competition is no longer defined solely by price or basic balancing capability; it is increasingly determined by workflow integration, automation readiness, fleet validation, and the ability to align equipment performance with compliance and efficiency mandates.
Wheel Balancer Market
Regulatory, Safety, and Operational Dynamics
The market does not operate in a regulatory vacuum. Equipment standards governed by OSHA, CE, and ISO frameworks shape workshop safety requirements for tire handling equipment, including wheel balancers, and influence procurement specifications across commercial and institutional buyers. Simultaneously, mandatory periodic technical inspection regimes, such as TÜV and MoT-aligned systems, reinforce the necessity of accurate wheel balancing as a component of vehicle safety compliance. These regulatory touchpoints create predictable, recurring demand drivers while also establishing performance expectations that newer or less-established entrants must meet to gain acceptance in professional service channels.
A parallel operational dynamic is the reduction of technician dependency through automated balancing cycles. As labor markets tighten and service facilities face pressure to maintain output with constrained staffing, automation functions that accelerate balancing procedures and reduce manual intervention are becoming central to equipment evaluation. This trend favors manufacturers that can demonstrate measurable cycle-time improvements, reduced re-work, and enhanced operator usability, while alsofavoring service providers who can translate equipment upgrades into service capacity expansion without proportionally increasing labor costs.
Strategic Implications for 2026 Enterprise Decision-Making
For executives evaluating market entry, portfolio expansion, partnership structures, or capital equipment procurement, the 2026 landscape presents several actionable imperatives. First, product strategy must account for the growing convergence of balancing, inflation automation, and diagnostic integration. Solutions that streamline tire service workflows and reduce changeover friction are gaining preferential positioning in high-volume and fleet-adjacent environments. Second, procurement and channel strategy should be calibrated to regional compliance expectations and labor economics, recognizing that the same equipment may deliver different value propositions depending on inspection regimes, workshop staffing models, and customer throughput requirements. Third, commercial vehicle and fleet-oriented segments reward evidence-based validation and long-term reliability, making field-proven performance and fleet endorsements increasingly influential in enterprise purchasing decisions.
Supply-side positioning also requires disciplined attention to concentration dynamics and differentiation pathways. In a market where leading players hold a meaningful share of revenue, new entrants and expanding manufacturers must identify defensible niches; whether through heavy-duty specialization, adaptive internal balancing, integrated service equipment bundling, or automation-enabled speed gains. Pricing competition alone is unlikely to sustain long-term advantage; rather, value capture will accrue to those who can align equipment performance with the operational realities of modern tire service facilities.
Why This Market Research Delivers Strategic Value
This study is designed to move beyond surface-level sizing and into the operational, competitive, and regulatory mechanics that actually shape procurement behavior and product strategy. The report integrates historical performance data, forward-looking growth architecture, and segmentation-level strategic interpretation, while protecting sensitive quantitative detail for clients who require granular intelligence for investment modeling and market planning. It examines equipment type dynamics, application-specific demand profiles, and regional deployment considerations with an emphasis on how these variables translate into pricing behavior, channel strategy, and differentiation opportunity.
Equally important, the analysis embeds competitive profiling and recent market developments into a cohesive strategic narrative. Product launches, trade show demonstrations, fleet approvals, and regulatory-driven operational shifts are evaluated not as isolated events, but as indicators of where industry momentum is heading and which capabilities are becoming table stakes. This contextual depth enables executives to anticipate demand shifts, benchmark competitive positioning, and align internal roadmaps with the structural forces that will define the 2026 to 2032 period.
Accessing the Full Intelligence Framework
The macro trajectory, segmentation architecture, concentration profile, and competitive developments outlined here represent a strategic preview of the full research. Detailed quantitative breakdowns, scenario analysis, supplier benchmarking, and region-specific deployment insights are reserved for the complete report. For organizations seeking to make informed equipment procurement, market entry, or product strategy decisions in the Wheel Balancer Market, the full study provides the structured intelligence necessary to convert industry momentum into actionable advantage.
The market is advancing with measurable consistency and increasing technological differentiation. In that environment, the most resilient strategies will be those built on precise understanding of demand drivers, regulatory reinforcement, automation economics, and competitive capability. This research is purpose-built to supply that understanding, enabling decision-makers to navigate the next phase of market evolution with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Wheel Balancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com