

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lysine Market Hits $4.36B in 2025, Projected to Surpass $6.7B by 2032 at 6.45% CAGR

The Strategic Imperative of the Global Lysine Market in 2026
The global lysine industry has entered a decisive phase of structural realignment, shaped by tightening trade defenses, volatile feedstock economics, and accelerating demand from protein-intensive supply chains. For executives navigating capital allocation, procurement strategy, and geographic expansion in 2026, superficial market narratives are no longer sufficient. The Lysine Market research report delivers a rigorously constructed analytical framework designed to translate macroeconomic shifts into executable corporate strategy. This introductory overview outlines the directional landscape and the analytical architecture embedded within the full study, providing decision-makers with a clear view of why deeper intelligence matters at this inflection point.
Macro Trajectory and the Strategic Window of 2026
Lysine has evolved from a commoditized feed additive into a strategically weighted input node that sits at the intersection of agricultural economics, animal nutrition efficiency, and downstream human consumption. The past half-decade has demonstrated a steady expansion in total market value, reflecting compound annual growth that positions the sector on a clear upward trajectory through the end of the decade. By the close of the historical review period, total revenue had surpassed the four-billion-dollar threshold, and forward modeling extends this momentum into a forecast window that projects a sustained climb toward the upper range of the six-billion-dollar mark by the terminal forecast year.
ε-Polylysine Market
The intermediate forecast years reveal a growth cadence that is neither linear nor uniformly distributed across horizons. Revenue milestones advance through the late 2020s, with acceleration points that reflect capacity expansions, regional demand maturation, and the gradual conversion of feedstock cost pressures into pricing and margin recalibration. For corporate planners, the critical takeaway is not simply that the market is expanding, but that the pace and shape of that expansion will differ materially across procurement cycles, investment horizons, and geographic footprints. Understanding where growth accelerates, where it plateaus, and which structural variables drive each phase is essential for timing capacity decisions, renegotiating long-term supply agreements, and prioritizing M&A or partnership targets.
This report's forecast architecture is built precisely for that purpose. Rather than presenting growth as a flat curve, the analysis decomposes the trajectory into scenario-sensitive pathways, allowing leadership teams to test assumptions around feedstock volatility, trade policy shifts, and demand elasticity before committing capital. In an environment where corn-based fermentation economics and nitrogen supply dynamics interact continuously with policy intervention, scenario discipline is not optional—it is the foundation of resilient planning.
Structural Architecture of Demand and Supply
The lysine value chain is defined by a clear hierarchy of applications, product forms, and regional demand centers. Animal nutrition continues to function as the dominant consumption pillar, anchoring volume requirements for feed-grade formulations and determining the baseline economics of fermentation operations. Food and dietary supplement applications represent a meaningful secondary channel, while pharmaceutical-grade and specialty uses occupy a narrower but strategically valuable niche where purity specifications, regulatory compliance, and batch consistency command differentiated pricing dynamics.
On the product-form side, the market is structured around distinct chemical variants, each with its own handling requirements, downstream usage patterns, and margin implications. The dominant form remains tightly tied to feed-grade demand, supported by well-established distribution channels and longstanding formulation standards. Secondary product forms serve complementary roles, often aligning with specific regional preferences, technical requirements, or application-specific cost structures. The report examines how these product segments interact with sourcing logic, logistics considerations, and strategic inventory positioning, giving procurement and product strategy teams a clearer map of where substitution risk, specification lock-in, or formulation flexibility may emerge.
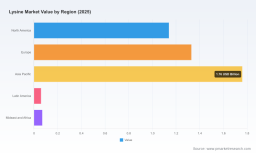
Regional demand distribution further shapes competitive behavior and supply-chain architecture. Asia Pacific remains the largest demand base, reflecting the scale and intensification of livestock production systems across several major economies. Europe and North America each represent substantial consumption centers with distinct procurement cultures, regulatory environments, and feed formulation practices. Latin America and the Middle East and Africa, while smaller in absolute share, function as strategically relevant nodes where trade flows, capacity placement, and policy interventions can influence price transmission and availability. The full report does not merely list these regional allocations; it interprets them through the lens of sourcing cost, logistics friction, tariff exposure, and localized competition intensity, enabling supply-chain leaders to evaluate which routes and partners align with their risk tolerance and growth ambitions.
The Competitive Arena: Scale, Geography, and Operational Posture
The lysine market is characterized by high concentration and a competitive field anchored by firms that combine fermentation scale, geographic diversification, and product specialization. A handful of leading players command a substantial share of global production, a structure that intensifies the strategic importance of capacity footprint, feedstock access, and regional market positioning. The full study profiles the organizations that define the current competitive baseline, tracing how each company's operational footprint and product focus shape its exposure to trade policy, demand shifts, and input cost volatility.
Global leaders in amino acid production continue to anchor the market through large-scale fermentation operations distributed across multiple continents. One Japanese incumbent maintains a broad lysine portfolio tied to feed-grade demand, leveraging production assets in South America, Southeast Asia, and the United States to support diversified regional supply. A major North American food and agricultural processor runs high-capacity fermentation facilities oriented toward animal nutrition, with production emphasis across both North American and Asian markets. A significant German specialty chemicals and nutrition supplier supplies branded lysine products for feed applications, maintaining fermentation capacity in the Americas and concentrating its commercial positioning on animal nutrition use cases.
From East Asia, one of the world's largest lysine producers operates an extensive network of fermentation facilities spanning Indonesia, China, Brazil, and the United States, supplying hydrochloride and sulfate forms for feed applications at global scale. Several Chinese manufacturers form a second competitive tier with rapidly expanding fermentation capacity. One leading Shandong-based producer is scaling capacity specifically for poultry and swine feed markets, while a major Beijing-based amino acid manufacturer maintains large-scale fermentation operations in China with a strong focus on feed-grade sulfate and hydrochloride. A specialized producer in northwestern China targets both feed and food-grade applications, and a Hong Kong-linked group maintains fermentation operations in Asia for animal nutrition products.
This competitive configuration matters for corporate strategy because scale, location, and product mix determine each player's vulnerability to trade measures, feedstock fluctuations, and regional demand shocks. The report's competitive analysis goes beyond basic company descriptions to examine how operational footprints interact with pricing behavior, capacity utilization trends, and geographic arbitrage opportunities. For organizations evaluating supplier diversification, partnership structures, or market entry, this competitive mapping provides the basis for assessing which counterparties offer reliability, which present cost advantages, and which may face structural constraints under evolving policy conditions.
Policy Friction and Feedstock Volatility: The 2026 Operating Environment
Trade policy has become one of the most influential variables in lysine market strategy. Over the past year and a half, multiple jurisdictions have moved to impose or investigate anti-dumping measures targeting Chinese lysine imports. In mid-2025, the European Commission initiated an investigation that was subsequently formalized into duties ranging from the low-to-mid forty percent range up toward the high fifty percent range, materially altering the economics of Chinese supply into the European market. In early 2026, the U.S. Department of Commerce announced a preliminary affirmative determination in its own antidumping duty investigation of lysine from China, signaling further potential disruption to transatlantic and transpacific trade flows. These measures do not simply affect one corridor; they reshape sourcing logic, redirect arbitration toward alternative origins, and introduce new layers of compliance and contingency planning for procurement organizations.
Feedstock economics add another dimension of operational uncertainty. Corn prices, a central determinant of fermentation input costs, have exhibited levels that place upward pressure on production economics for lysine manufacturers. When corn costs remain elevated, fermentation-based producers must navigate the tension between input cost absorption, margin preservation, and competitive pricing behavior. Compounding this is the broader nitrogen supply chain context, where tariff actions on related agricultural inputs have introduced cost and availability questions that indirectly influence lysine production economics. In a market where capacity utilization, feedstock procurement, and pricing response are tightly linked, these dynamics demand scenario-aware procurement strategies rather than static contract assumptions.
Lysine Market
The report incorporates these developments into a structured dynamics analysis, connecting regulatory timelines, commodity price movements, and production economics to the strategic questions faced by buyers, producers, and investors. Rather than treating each event in isolation, the analysis examines how overlapping policy and cost pressures will reshape competitive advantage, regional supply availability, and risk exposure across the forecast period.
What the Full Report Delivers: An Operational Intelligence Architecture
The complete Lysine Market research report is designed to function as a decision-enabling toolkit rather than a static market summary. It translates the structural, competitive, and regulatory context into actionable analysis organized around the questions that actually drive board-level and operational decisions in 2026.
- The forecast module delivers multi-year revenue pathways and growth momentum indicators that allow teams to align investment planning, budgeting cycles, and capacity assessment with realistic market progression rather than point estimates.
- Segmentation analysis examines product forms, application channels, and regional demand structures with the depth required to support sourcing strategies, product positioning decisions, and geographic prioritization.
- Competitive profiling maps the operational posture of leading lysine producers, connecting facility locations, product focus, and scale to the strategic implications each company's footprint creates for suppliers, buyers, and prospective entrants.
- Dynamics coverage integrates trade investigations, duty outcomes, feedstock cost pressures, and nitrogen supply chain considerations into a coherent picture of the operating environment, helping risk and procurement teams anticipate where disruption is most likely to emerge.
- Scenario-sensitive analysis supports stress-testing of assumptions around cost transmission, trade-route substitution, and demand responsiveness, giving leadership teams a structured way to evaluate resilience before committing resources.
The report's architecture is built to support cross-functional use. Procurement teams can leverage the segmentation and dynamics sections to refine supplier diversification and contract negotiation logic. Strategy and corporate development teams can use the competitive and forecast modules to evaluate partnership targets, geographic entry priorities, and investment timing. Finance and risk functions can apply the scenario framework to assess exposure to tariff shifts, feedstock volatility, and regional demand changes. By unifying these perspectives in one coherent research base, the study reduces the friction involved in aligning commercial, operational, and financial strategies around a common market view.
Why This Study Matters for 2026 Decision-Making
The lysine market in 2026 is not defined by a single dominant trend; it is defined by the interaction of several forces that converge on sourcing reliability, cost structure, and competitive positioning. Trade measures are altering the relative attractiveness of different supply origins. Feedstock costs are pressuring production margins and reshaping pricing behavior. Demand continues to build on the foundation of animal nutrition, while higher-value applications provide differentiated opportunities for players with the right technical and compliance capabilities. In this environment, strategic decisions made without granular, scenario-oriented intelligence carry disproportionate risk.
Companies that rely on top-line growth figures alone risk misreading where opportunity is concentrated and where vulnerability lies. Regional demand shares, product-form economics, and competitive footprints each influence how growth translates into actionable advantage. Similarly, understanding trade and feedstock dynamics in isolation is insufficient; the strategic value emerges when policy, cost, and demand are evaluated together through a structured analytical lens. This report is designed to provide that lens.
For organizations planning procurement renegotiations, evaluating capacity investments, assessing supplier diversification, or exploring market-entry and partnership strategies, the full research study offers the depth needed to convert market context into concrete action. The executive summary and directional analysis presented here illustrate the strategic framing and analytical discipline embedded in the complete work, while the full study supplies the detailed segmentation, competitive mapping, scenario pathways, and dynamics assessment required for confident execution.
To access the complete dataset, scenario models, and operational analysis supporting these conclusions, readers are directed to the full report portal, where the underlying segmentation detail, competitive profiles, and policy-impact assessments are available for internal strategy development and cross-functional alignment.
For detailed analysis of this topic, please visit the official page: Lysine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com