

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Footwear Market Hits $483B in 2025, Projected 4.7% CAGR to Reach $663.9B by 2032

Navigating the Future of Footwear: Strategic Intelligence for 2026 and Beyond
The global footwear market stands at a critical inflection point. As brands confront shifting trade policies, evolving sustainability mandates, and rapidly changing consumer preferences, the margin between reactive adaptation and proactive strategy has never been thinner. PW Consulting’s latest Footwear Market research study is designed to cut through the noise, delivering a rigorous, data-anchored framework that equips executives, investors, and product leaders with the intelligence needed to make decisive moves throughout 2026 and the forecast horizon through 2032.
This article outlines the study’s analytical architecture, highlights the structural forces reshaping the sector, and demonstrates how decision-makers can translate macro-level market intelligence into operational advantage. The complete dataset, granular segmentation breakdowns, and proprietary competitive matrices are reserved for the full report. What follows is a strategic preview of the terrain ahead.
Market Architecture: A Trajectory of Measured Expansion
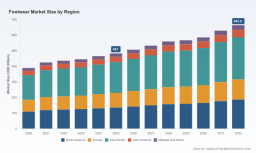
Historical performance from 2020 through 2025 illustrates a sector that has consistently weathered macroeconomic headwinds while expanding its revenue footprint. The market progressed from a base of $389.5 billion in 2020 to $424.66 billion in 2021, steadied at $436.1 billion in 2022, and continued its upward march to $445.45 billion in 2023 and $465.26 billion in 2024. By 2025, total revenue reached $483.0 billion, establishing a robust foundation for the forecast period.
Looking ahead, the trajectory projects sustained, compounding growth. The market is expected to cross $506.5 billion in 2026, advance to $532.4 billion in 2027, and approach $559.8 billion by 2028. Continued expansion is anticipated through 2029 ($566.9 billion), 2030 ($585.9 billion), 2031 ($628.9 billion), and culminating at $663.9 billion in 2032. Across the 2025–2032 forecast window, the sector is positioned to deliver a compound annual growth rate of 4.7 percent in USD terms.
Sports Footwear Market
This growth profile is neither explosive nor stagnant; it is structural. The consistent upward slope suggests that underlying demand drivers—fitness participation, casualization trends, and durable replacement cycles—are compounding even as pricing pressures and supply chain realignments introduce volatility. Our research deciphers where that growth concentrates, which customer cohorts are accelerating or decelerating, and how the balance of power is shifting across geographies and product architectures.
The Strategic Terrain: Dynamics Shaping 2026 Decision-Making
Three intersecting forces define the current operating environment for footwear manufacturers, distributors, and retailers. Understanding their interplay is essential for building resilient portfolios and defensible margin structures.
Trade Policy and Cost Architecture
Regulatory and tariff environments have transitioned from peripheral considerations to central boardroom topics. U.S. footwear tariffs average approximately 23.6 percent, with specific categories facing duties exceeding 48 percent. In 2025 alone, industry participants remitted $6.221 billion in tariffs, a figure that underscores how trade policy now functions as a direct line item in cost structures and pricing strategies. Global brands and suppliers have responded by recalibrating sourcing footprints, with acquisition activity increasing in 2025 as companies seek to offset cost impacts and secure domestic or nearshore capacity. McKinsey’s latest outlook also projects low single-digit growth for the broader global fashion industry in 2026, with footwear identified as a key subsector navigating tariff uncertainty.
For strategic planners, the implication is clear: cost modeling must incorporate dynamic duty scenarios, and supply chain flexibility is no longer a premium feature but a baseline requirement. The analysis in our study maps how these pressures interact with segment-level pricing power and margin retention strategies, without exposing the proprietary allocation figures that would enable direct benchmarking.
Sustainability Mandates and Product Traceability
Regulatory frameworks are increasingly tying market access to verifiable sustainability performance. The EU Ecodesign for Sustainable Products Regulation mandates Digital Product Passports for footwear by 2027, a requirement designed to enhance traceability, material transparency, and lifecycle accountability. Compliance will affect everything from design specifications and supplier qualification to consumer-facing claims and inventory management systems.
Simultaneously, product innovation is converging with sustainability. Recent trade show activity, including the Footwear Show New York Expo held in June 2026, showcased sustainable innovations, sculptural heels, and minimalist sneakers as focal points for buyer engagement. Similarly, the 26th International Shoes & Leather Exhibition in Ho Chi Minh City, scheduled for July 2026, is positioned to highlight new machinery, advanced materials, and sustainable footwear initiatives across the Asia-Pacific production ecosystem. These signals suggest that sustainability is transitioning from a compliance checkbox to a product differentiation lever and a procurement prerequisite. Our report dissects how leading manufacturers are operationalizing these mandates and which material and process innovations are gaining commercial traction.
Consumer Behavior and Demand Realignment
Consumer spending patterns continue to reflect a nuanced recovery. Footwear and accessories led outdoor retail sales growth in 2024 according to Outdoor Industry Association data, with a modest rebound extending into 2025. This trend highlights the resilience of activity-driven purchasing, even as broader discretionary spending remains selective. At the same time, category preferences are shifting: athletic and lifestyle products are competing more aggressively for share, casual comfort is consolidating its everyday role, and formal segments are recalibrating around occasion-driven demand.
Demand is also fragmenting across demographics and use cases, requiring more granular assortment planning and inventory positioning. The study evaluates which consumer cohorts are expanding spend, how occasion and activity segmentation influences repeat purchase behavior, and where channel mix is reshaping fulfillment economics. These insights are structured to inform assortment strategy, promotional cadence, and regional prioritization without disclosing the exact allocation values that form the backbone of the full dataset.
Competitive Landscape: Concentration, Positioning, and Ecosystem Evolution
The footwear market operates with moderate but meaningful concentration. The top three players account for approximately 52 percent of market revenue, while the top five collectively represent around 58 percent. This structure creates a landscape where scale advantages coexist with specialized niches, and where competitive differentiation increasingly depends on design velocity, comfort engineering, vertical integration, and compliance capability.
The competitive field spans multiple strategic archetypes. Global athletic and lifestyle franchises—including Nike, Inc., Puma SE, adidas America, Inc., ASICS America, and New Balance—continue to anchor the performance and lifestyle segments, each pursuing distinct design philosophies, distribution models, and brand ecosystems. In the casual and comfort space, Crocs, Inc., Skechers USA Inc., and Clarks maintain strong consumer recognition, while ECCO Sko A/S and Geox S.p.A. emphasize premium casual positioning and breathable comfort technologies, respectively. Rieker Shoes and Belleville Boot Company further illustrate the breadth of specialization, with orthopedic comfort and tactical/military applications representing distinct demand pools.
Beyond consumer-facing brands, a parallel ecosystem of work, outdoor, safety, and military-focused manufacturers underscores the strategic importance of compliance and durability. Timberland LLC, Danner Shoe Manufacturing Company, Red Wing Shoe Company, and Wolverine World Wide Inc. anchor the work and outdoor categories, while McRae Industries and Belleville Boot Company highlight Berry Amendment-compliant military combat boot production, a niche where regulatory adherence and supply chain reliability are as critical as product performance. Steinberg Systems contributes additional depth in work and safety footwear manufacturing. Brooks Running specializes in running and performance athletic footwear, reinforcing the segmentation between mass-market lifestyle lines and application-specific engineering. A newer generation of innovators, including Made Plus, is entering the field with next-generation performance footwear that pairs advanced design with sustainability mandates, signaling how product architecture is evolving to meet both consumer expectation and regulatory scrutiny.
Recent membership and ecosystem developments further illustrate how the competitive landscape is being reshaped by supply chain localization and capacity expansion. In May 2026, McRae Industries was welcomed as the newest USFMA manufacturer member, reinforcing its legacy in Berry Amendment-compliant military combat boots. In April 2026, YKK Americas joined USFMA to expand national capacity for military boot production following the acquisition of Collt’s Manufacturing. In February 2026, Gusbi, Autec Automation, and Robot System Automation were added as Italian footwear machinery leaders to enhance U.S. production capacity for domestic manufacturers. These movements point to a broader shift: capabilities in compliant manufacturing, automation, and domestic sourcing are becoming strategic differentiators, not just operational utilities. The full report provides a comparative analysis of how key players are aligning product portfolios, sourcing strategies, and compliance capabilities to protect share and capture growth.
Inside the Study: Analytical Depth Built for Executive Action
This research is structured to move beyond surface-level trend summaries and deliver an operational intelligence toolkit. The study integrates historical performance, forward-looking forecasts, and multi-dimensional segmentation to give decision-makers a coherent view of where value is created and how competitive advantage is sustained.
Coverage Architecture
The report maps the market across a defined historical window and a seven-year forecast horizon, providing continuity between past performance and future expectation. It decomposes total market revenue across product type, consumer application, and regional demand patterns, enabling readers to identify where structural growth is most durable and where cyclical vulnerabilities may emerge. Rather than presenting isolated statistics, the analysis connects segmentation behavior to pricing dynamics, channel economics, and competitive positioning.
Operational Components
Strategic users will find several layers of actionable content:
- Macro and segment-level growth pathways that link historical momentum to forecast assumptions, allowing teams to stress-test planning scenarios.
- Competitive positioning frameworks that map how leading players differentiate across design, performance, comfort, compliance, and distribution, with attention to the structural advantages implied by market concentration.
- Regulatory and trade impact analysis that translates tariff exposure, sustainability mandates, and traceability requirements into strategic implications for sourcing, product design, and cost architecture.
- Consumer and channel dynamics that contextualize demand shifts across activity-driven, lifestyle, and occasion-based purchasing, helping brands refine assortment strategy and inventory allocation logic.
- Ecosystem and capacity developments that track machinery investment, domestic production expansion, and membership-driven supply chain realignment, offering early signals of where operational bottlenecks may ease or intensify.
Each component is designed to be integrated into existing strategic planning processes. The report’s format supports scenario modeling, competitive benchmarking, and investment prioritization, while the underlying methodology ensures consistency between historical baselines and forward projections.
Why the Full Dataset Matters
Market intelligence reaches its full value only when it is granular enough to inform specific decisions. Segment-level allocation figures, regional demand patterns, and type- and application-level revenue splits form the operational backbone that allows teams to compare internal performance against market structures, identify white-space opportunities, and calibrate entry or expansion strategies. These details are central to the complete study and are intentionally held back from this preview so that the full report delivers its intended strategic ROI. Readers seeking to benchmark their portfolio, evaluate acquisition targets, or validate regional prioritization will find those answers in the comprehensive dataset.
Turning Intelligence into Advantage in 2026
The 2026 operating environment rewards organizations that can align product strategy with regulatory reality, cost architecture, and demand fragmentation. Tariff volatility and sustainability mandates are no longer isolated risk registers; they are design, sourcing, and pricing constraints that shape what can be built, where it can be sourced, and how it can be positioned. At the same time, consumer demand continues to reward performance, comfort, and credible sustainability, while discretionary spending remains disciplined enough to punish misaligned assortments.
Footwear Market
In this context, the 4.7 percent compound annual growth trajectory through 2032 should be read not as a guarantee of easy expansion, but as a signal that structural demand is intact and that competitive gains will accrue to those who can navigate complexity with precision. Organizations that understand where growth concentrates, how concentration influences pricing and margin behavior, and how compliance and supply chain capacity are evolving will be better positioned to defend share and capture incremental value.
PW Consulting’s Footwear Market study is built for that moment. It offers a rigorous, integrated view of market size, growth pathways, competitive architecture, and the regulatory and consumer dynamics that will define execution in the years ahead. The complete report contains the detailed segmentation splits, regional revenue distributions, and company-level comparative analysis required for direct strategic application.
For executives, category leaders, and investors preparing for 2026 planning cycles, the study provides the foundation to move from awareness to action: prioritize the right segments, anticipate compliance-driven redesign, align sourcing with cost resilience, and position portfolios where demand is most durable. The full intelligence package is available through our research portal, where detailed datasets, methodology notes, and scenario-ready breakdowns can be accessed and integrated into your strategic workflow.
For detailed analysis of this topic, please visit the official page: Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com