

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Eddy Current Sensor Market to Hit $1.86B by 2032 with 6.5% CAGR

Charting Precision: Strategic Intelligence for the Eddy Current Sensor Market in 2026 and Beyond
In an industrial landscape defined by tightening tolerances, automation acceleration, and non-destructive testing mandates, proximity and displacement sensing have quietly become critical infrastructure. Eddy current sensors occupy a unique niche in this ecosystem, offering sub-micron resolution, immunity to dust and oil contamination, and reliable performance in environments where optical or capacitive alternatives falter. As manufacturing footprints fragment across regions and precision requirements escalate, the strategic value of high-fidelity market intelligence cannot be overstated.
This analysis introduces a newly published market research study that maps the trajectory of the global eddy current sensor market from a 2025 base year through a seven-year forecast window extending to 2032. The study is designed not as a static snapshot but as a decision-support instrument for engineering leaders, procurement directors, and corporate strategy teams preparing for the competitive and operational realities of 2026. Below, we outline the strategic architecture of the report, the forces reshaping supply and demand, and the competitive dynamics that will separate market leaders from followers.
From Baseline to 2032: A Revenue Trajectory Built for Scenario Planning
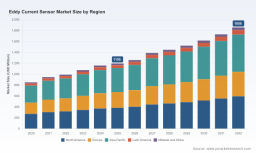
The report anchors its forward-looking assessments in a rigorously back-tested historical series spanning 2020 through 2025, followed by a forecast period that runs from 2026 through 2032. Over the historical window, the market demonstrated consistent expansion, moving from a baseline just above the mid-800-million-dollar range in 2020 to a position approaching 1.2 billion U.S. dollars by 2025. This climb reflects compounding demand drivers: more stringent equipment monitoring in turbomachinery, broader adoption of non-contact measurement on automated production lines, and rising inspection requirements in aerospace, defense, and petrochemical operations.
Looking ahead, the forecast models project a compound annual growth rate of approximately 6.5 percent across the full 2026–2032 horizon. In absolute terms, this translates into a measured but meaningful upward arc: the market is expected to cross the 1.25-billion-dollar threshold in 2026 and continue ascending toward the 1.8-billion-dollar range by 2032. Importantly, these figures are presented in the report as scenario-ready ranges rather than single-point predictions. Decision-makers can stress-test capex plans, production allocations, and inventory strategies against base, upside, and downside cases, adjusting assumptions around cycle times, capital availability, and regional demand timing.
The report deliberately refrains from presenting headline aggregate numbers as the centerpiece. Instead, it uses the macro trajectory to frame a deeper question: where, how, and with whom will the next phase of value creation occur? That framing is what transforms raw sizing data into strategic optionality for 2026 planning cycles.
Inside the Report: Operational Intelligence for Engineering and Commercial Teams
A market study earns its shelf space only when it converts data into action. This report is structured to serve multiple stakeholder functions simultaneously, balancing quantitative rigor with qualitative context. The analytical architecture includes the following core components:
- Segment-Level Demand Architecture. The study disaggregates the market along multiple axes, including product architectures, end-use verticals, and geographic regions. Rather than offering static splits, each segment view is accompanied by demand elasticity commentary, adoption curve positioning, and indicators that signal which sub-segments are likely to outpace or underperform the market average.
- Competitive Benchmarking and Strategic Group Mapping. Company profiles are paired with an assessment of positioning, technology differentiation, and commercial model. The analysis surfaces which players compete primarily on precision and integration, which compete on application-specific inspection configurations, and which are leveraging scale and channel depth to defend share.
- Technology Roadmap and Application Scenarios. The report examines how sensor form factors, measurement ranges, signal-processing capabilities, and environmental ratings are evolving in response to factory automation, turbomachinery monitoring, and NDT inspection requirements. It identifies where engineering trade-offs—accuracy versus robustness, integrated versus split configurations, manual inspection versus automated array-based NDT—are reshaping buyer preferences.
- Supply-Side and Cost Structure Dynamics. Beyond demand, the study traces the upstream factors that influence margin structures and availability. Material inputs, qualification requirements, and trade policy exposure are mapped to the segments and regions they affect most, giving procurement and operations teams early visibility into cost volatility and sourcing constraints.
- Regulatory and Standards Context. Compliance frameworks and personnel qualification standards are analyzed not as abstract policy but as operational determinants that influence inspection throughput, service models, and competitive barriers in specific regions and verticals.
- Scenario and Sensitivity Layers. The report provides a structured basis for exploring how shifts in capital spending, automation adoption, export controls, and commodity prices could alter the pace and geography of growth through 2032.
The practical output is a document that supports product roadmapping, channel strategy, M&A targeting, and client-facing positioning. It is equally useful for a sensor OEM assessing where to invest in next-generation measurement suites, a system integrator evaluating which sensing technologies to specify in automation deployments, and a service provider planning NDT inspection capacity in regulated industries.
Forces Reshaping the Market: Technology, Trade, Materials, and Standards
Market growth at this stage of the cycle is rarely the result of a single driver. In the eddy current sensor space, the forward trajectory is being shaped by a convergence of technical and structural forces that the report examines in detail.
Precision, Durability, and Integration as Competitive Axes
Buyers across factory automation and rotating equipment monitoring are increasingly selecting sensors not only for measurement accuracy, but also for survivability in harsh environments and ease of integration into broader control architectures. Recent product activity underscores this direction. In early 2025, one European specialist introduced a new eddy current displacement sensor series engineered for submicron accuracy combined with IP69K-rated protection, targeting environments where cleaning regimes, humidity, and contamination would compromise less rugged designs. Around the same period, industrial automation players moved to bundle sensing capabilities into broader factory automation ecosystems. A notable example involved a partnership aimed at jointly developing advanced eddy current displacement sensors for high-volume factory automation deployments, with initial targets referencing thousands of installations. In late 2024, a major turbomachinery instrumentation supplier updated specifications for a 5 mm eddy current sensor intended for radial and axial shaft displacement monitoring, reflecting continued emphasis on predictive maintenance and condition monitoring in critical rotating assets.
These developments illustrate a broader shift: sensors are no longer viewed as isolated components but as integrated measurement nodes whose value depends on interoperability, environmental resilience, and the quality of the signal chain behind them.
Non-Destructive Testing as a Structural Demand Engine
NDT remains a foundational application domain for eddy current technology, particularly for crack detection, material sorting, and surface inspection. Demand here is shaped by both regulatory expectations and operational economics. Personnel qualification standards, including ISO 18436-1, require certification for NDT inspectors, reinforcing the value of standardized, repeatable measurement instruments and structured inspection processes. In parallel, the rise of eddy current array probes and advanced NDT instrumentation has expanded inspection coverage and throughput, enabling more efficient defect detection and reducing reliance on labor-intensive point-by-point methods.
The strategic significance of this segment intensified with a major corporate development in early 2026, when a large industrial group completed the acquisition of an eddy current array and NDT specialist. The transaction signals that established industrial portfolios are actively consolidating advanced inspection capabilities, reinforcing the notion that NDT is moving from a peripheral capability to a strategically integrated offering within broader industrial technology and fabrication ecosystems.
Eddy Current Sensor Market
Input Costs, Materials, and Trade Policy as Margin and Availability Variables
On the supply side, margin planning and availability are increasingly-sensitive variables. Copper wire coils used in eddy current probes have faced rising material costs tied to commodity volatility, affecting cost structures across multiple sensor configurations. At the same time, high-frequency sensor designs that depend on magnet assemblies with rare earth materials have encountered export limits originating from China, constraining certain supply chains and prompting reassessment of sourcing strategies. In addition, U.S. tariffs on China-origin sensors have affected supply chain costs for North American manufacturers, adding a trade-policy dimension to regional sourcing decisions.
These dynamics are not merely procurement concerns; they influence where and how products are designed, which specifications become commercially viable at scale, and which customer segments are most exposed to price pressure. The report maps these pressures to the segments and geographies most likely to feel them first, enabling teams to anticipate rather than react.
Competitive Landscape: Strategic Groups and Differentiated Playbooks
The eddy current sensor market is not a monolith. It is a collection of overlapping competitive theaters, each with its own technical priorities, buying committees, and differentiation logic. The report profiles a set of companies that together illustrate the strategic variety in the space and clarify how value is being contested.
Precision Measurement Specialists in Factory Automation and Displacement Sensing
Among the companies shaping the displacement and proximity measurement segment, several are competing on measurement fidelity, robustness, and system-level integration. A German specialist is known for its eddyNCDT series of eddy current displacement sensors, which emphasize high-precision non-contact measurement and have been extended into newer series engineered for demanding industrial conditions. In the United States, another specialist has built its reputation around ECL-series eddy current linear encoders and displacement sensors, positioning close to factory automation and precision motion control applications. A Japanese measurement systems company integrates eddy current displacement sensors into broader measurement platforms, leveraging system-level reach and a wide customer base to scale adoption.
For these players, strategic advantage is often built on control over the measurement chain—signal stability, environmental resilience, calibration consistency, and the ability to integrate cleanly with controllers, HMIs, and automation architectures. Competition here tends to reward incremental precision gains, ruggedization, and application-specific tuning.
NDT-Focused Players and the Inspection Technology Tier
A second strategic group is oriented more directly around inspection and non-destructive testing. A Canadian company has gained recognition for eddy current array probes and instruments designed for NDT inspections, where coverage, scan efficiency, and data interpretation are central value drivers. A German test instrument manufacturer focuses on eddy current test instruments and probes for crack detection and material sorting, emphasizing reliability in inspection workflows. A Chinese supplier has expanded its presence in eddy current detectors and testing systems for NDT applications, reflecting broader momentum in cost-sensitive inspection markets and regional industrial growth.
In this tier, differentiation frequently comes from probe geometry, array coverage, portability, software-enabled interpretation, and the ability to meet application-specific inspection standards. The 2026 acquisition of a leading NDT-focused eddy current array company by a larger industrial corporation illustrates how this part of the market is attracting strategic consolidation from buyers seeking to embed advanced inspection capability into broader industrial offerings.
Turbomachinery, Vibration, and Asset Monitoring Specialists
A third group competes closer to rotating equipment and asset condition monitoring, where displacement, vibration, and proximity measurement support predictive maintenance and machinery protection. A major industrial instrumentation company has extended its portfolio with eddy current sensors such as the AMS EZ 1000 series, aimed at turbomachinery radial and axial displacement and vibration monitoring. A U.S.-based precision instruments company offers eddy current proximity probes for displacement and vibration measurement, serving customers who depend on continuous machinery health data in critical installations.
Here the buying center often spans reliability engineering, maintenance operations, and instrumentation procurement, and the value proposition ties directly to uptime, alarm accuracy, and integration with asset management systems. The competitive bar is shaped by long service life, proven reliability in harsh rotating equipment environments, and the ability to support standardized maintenance processes.
Taken together, these profiles show that the market is being contested on multiple fronts simultaneously. Some companies are winning through precision and integration; others through inspection-domain specialization; others through sector-specific reliability and channel reach. The report’s competitive analysis is designed to help organizations identify which strategic group their offerings align with, where substitution risk is highest, and which competitor moves should be monitored most closely in 2026.
Eddy Current NDT Equipment Market
Geographic and Segment Signals Without Data Overload
The report’s geographic and application segmentation is presented not as a wall of percentages, but as a set of directional signals that inform where growth is concentrating and where competitive intensity is likely to rise. Regionally, the analysis examines how mature industrial automation markets compare with faster-growing inspection and manufacturing regions, and how trade policy, sourcing exposure, and standards environments alter the growth calculus in each geography. It also addresses how different regions are positioned relative to key applications, from factory automation and displacement measurement to aerospace, defense, power generation, and petrochemical inspection.
On the application side, the report traces where demand is being reinforced by structural factors—such as rotating equipment monitoring in power generation and turbomachinery, inspection mandates in aerospace and defense, and process-related monitoring in petrochemical operations—versus where growth is more cyclical or discretionary. By separating structurally supported demand from more volatile demand pockets, the study helps leaders prioritize investments and allocate commercial resources more deliberately.
This approach avoids the trap of treating segmentation as a formatting exercise. Instead, it uses segment context to answer strategic questions: which applications are likely to sustain multi-year sensor spending, which customer groups face the stiffest cost or qualification pressures, and which geographic markets present the most attractive combinations of demand growth and manageable risk.
Concentration, Barriers, and Where Competitive Advantage Is Being Built
Market structure matters because it reveals how difficult it is to enter, scale, and defend share. The report notes a moderately concentrated competitive environment, with the top three participants holding a meaningful combined share and the top five extending that position further. Such concentration typically reflects accumulated advantages in measurement performance, application expertise, qualification credibility, distribution reach, and long-term customer relationships in demanding industrial settings.
At the same time, concentration is not uniform across all segments. In some application areas, specialization and inspection-specific know-how can create effective local leadership even where overall market share is modest. In others, integration capability and channel scale can compensate for narrower technical specialization. The report maps these dynamics so that companies can see not just who leads today, but what kinds of capabilities are likely to determine leadership tomorrow.
For incumbents, the strategic imperative is to reinforce the attributes that make substitution costly: proven accuracy under real operating conditions, robust environmental ratings, reliable calibration and service support, and integration paths that reduce total cost of ownership. For challengers and new entrants, the opportunity often lies in targeted segments where a specific technical advantage, lower-cost architecture, or software-enabled workflow can convert into a defensible position before scale competitors respond.
How to Use This Intelligence for 2026 Decision-Making
The report is designed to be used, not merely read. In practice, it can support several high-priority 2026 decisions:
- Product and engineering roadmapping. Teams can align sensor development investments with the configurations, environmental ratings, and application requirements most likely to drive differentiated demand, rather than reacting to generalized market narratives.
- Commercial and channel strategy. Sales leaders can prioritize geographies and application segments where demand momentum and competitive positioning are most favorable, and adjust messaging to match the procurement and engineering priorities of each buying center.
- Procurement and supply resilience. Operations and sourcing teams can anticipate where material volatility, rare earth exposure, and trade-policy friction are most likely to affect cost and availability, and can diversify or reconfigure supply accordingly.
- M&A and partnership evaluation. Corporate development teams can use the competitive and technology mapping to identify capability gaps, acquisition targets, and partnership opportunities, especially in NDT, automation integration, and turbomachinery instrumentation.
- Investment and scenario planning. Finance and strategy teams can use the forecast architecture to test capital allocation decisions against multiple growth paths, ensuring that commitments are robust to variation in demand timing and regional performance.
The underlying message is consistent: the most valuable insights are not the headline numbers alone, but the structured reasoning behind them and the operational implications they imply. A 6.5 percent growth trajectory, for example, becomes actionable only when it is linked to which applications are expanding fastest, which product types are gaining share, and which supply-side constraints might shape margin outcomes.
Why the Full Study Matters and How to Access It
This article has outlined the strategic logic, competitive architecture, and demand-supply forces that define the eddy current sensor market heading into 2026. It has also indicated why the complete study is more than a data set: it is a decision framework that connects market sizing, segmentation context, competitive profiling, recent product and corporate developments, and structural risk factors into a coherent basis for planning.
To support rigorous decision-making, the full report goes further. It provides detailed segment-level breakdowns, company-specific positioning assessments, application-by-application demand commentary, regional growth context, and scenario-ready forecast structures. It also examines how recent product launches, partnerships, specification updates, and acquisitions are reshaping competitive expectations in real time.
For strategy, engineering, procurement, and commercial leaders who need to move beyond directional market narratives and into specific allocation, sourcing, and positioning choices, the complete study is the appropriate reference point. The full intelligence package, including segment splits, regional and application detail, and the complete competitive set, is available through the official report page. We invite interested teams to review the full publication and use it as a foundation for 2026 strategy development.
For detailed analysis of this topic, please visit the official page: Eddy Current Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com