

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Commercial Boilers Market Hits $10.03B in 2025, Poised for 4.2% CAGR Through 2032

Commercial Boilers Market Outlook 2026: Strategic Insights for Enterprise Decision-Making
The global commercial boilers market stands at a pivotal juncture as we move through 2026. With a projected market valuation of USD 10,431.92 Million in 2026 and a forecasted expansion to USD 13,126.2 Million by 2032, the sector is experiencing a compound annual growth rate of 4.2 percent. These figures represent more than statistical milestones; they signal a structural transformation in how commercial enterprises approach thermal energy management, regulatory compliance, and operational efficiency. For corporate strategists, procurement leaders, and capital allocation committees, understanding the underlying drivers of this growth trajectory is no longer optional. It is a prerequisite for maintaining competitive advantage in an increasingly regulated and cost-sensitive environment.
Our latest market research initiative moves beyond surface-level projections to deliver an actionable intelligence framework. This report is designed to equip decision-makers with the nuanced understanding required to navigate fuel transitions, technological adoption curves, and shifting end-use demand patterns. What follows is a strategic preview of the insights contained within the full study, illustrating why this analysis should occupy a central position in your 2026 planning cycle.
Macro Growth Trajectory and Structural Market Drivers
The historical data spanning 2020 through 2025 reveals a market that has demonstrated remarkable resilience and steady appreciation. Revenue expanded from USD 8,125.8 Million in 2020 to USD 10,029.1 Million by 2025, reflecting a consistent upward momentum that has accelerated as regulatory frameworks tighten and efficiency mandates become more rigorous. The forecast period from 2026 through 2032 projects continued expansion, with intermediate valuation checkpoints at USD 11,186.8 Million in 2027, USD 11,352.66 Million in 2028, and further increments culminating in the 2032 target figure. This trajectory is underpinned by several converging forces: aging infrastructure requiring modernization, tightening emission standards that favor high-efficiency configurations, and the growing commercialization of modular and condensing technologies that reduce operational expenditures over asset lifecycles.
Enterprise leaders must recognize that these growth figures are not uniformly distributed across all market dimensions. The expansion is being shaped by distinct fuel preferences, capacity utilization patterns, and regional deployment strategies that create differentiated opportunities for suppliers, integrators, and end-users. Our research dissects these variables with granular precision, enabling organizations to identify where capital deployment will yield the highest risk-adjusted returns.
Fuel, Technology, and Capacity Dynamics Reshaping Procurement Strategies
The fuel mix landscape continues to be dominated by natural gas infrastructure, which maintains a substantial share of total market revenue. However, the strategic conversation among commercial operators is increasingly focused on the sustainability implications of long-term fuel dependence and the economic case for transitioning toward biomass, hybrid systems, and electrification pathways where operational feasibility permits. Oil and coal segments retain relevance in specific industrial and legacy applications, while emerging alternative fuel configurations are gaining traction in targeted niches where regulatory incentives and local resource availability align favorably.
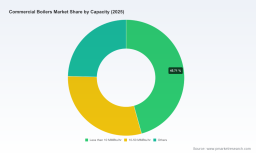
On the technology front, the market is characterized by a persistent tension between established non-condensing systems and the accelerating adoption of condensing boilers that capture latent heat from exhaust gases. Condensing technologies are becoming increasingly attractive to facilities seeking to meet stricter combustion efficiency benchmarks while reducing fuel consumption. Capacity segmentation further complicates the procurement calculus, with smaller-scale units below 10 MMBtu/hr maintaining strong demand in distributed commercial settings, mid-range systems between 10 and 50 MMBtu/hr serving aggregated heating loads, and larger configurations supporting intensive process heating requirements. Our analysis maps these technology and capacity vectors against real-world operational parameters, providing a framework for aligning equipment specifications with actual facility profiles rather than generic industry assumptions.
End-Use Sector Opportunities: Healthcare, Commercial Real Estate, Education, and Lodging
The deployment of commercial boilers across end-use verticals reveals distinct demand signatures that require tailored market engagement strategies. Healthcare facilities represent a critical segment where uninterrupted hot water and steam delivery directly impacts patient care standards and regulatory compliance. Offices and educational institutions form a substantial demand block driven by campus expansion, retrofit programs, and the replacement of aging heating infrastructure. The lodging sector continues to prioritize reliability and energy cost control as core requirements for maintaining occupancy rates and margin profiles. Additionally, a diverse group of other commercial applications contributes meaningful volume to the aggregate demand picture, often presenting specialized requirements that reward suppliers capable of delivering customized integration solutions.
Understanding the operational rhythms, budget cycles, and compliance obligations of each end-use category is essential for developing effective go-to-market strategies and for end-users evaluating vendor partnerships. The full research report provides a detailed mapping of these sector-specific dynamics, including procurement timelines, specification trends, and the competitive positioning of equipment manufacturers within each vertical.
Competitive Landscape: Key Players and Strategic Positioning
The commercial boilers market is shaped by a cohort of established manufacturers whose product portfolios, geographic reach, and technical capabilities define the competitive baseline. Cleaver-Brooks, headquartered in Thomasville, Georgia, has built a reputation around complete boiler room solutions, firetube boiler configurations, and integrated systems engineered for commercial and industrial environments including food processing and dairy operations. Fulton Companies, based in Pulaski, New York, offers high-efficiency steam and hydronic boilers alongside thermal fluid heaters and custom heat transfer systems designed for demanding commercial applications. Hurst Boiler & Welding Co., Inc., operating from Coolidge, Georgia, provides a broad fuel-flexible lineup encompassing gas, oil, biomass, and hybrid steam and hot water boilers that serve both commercial and industrial users.
Lochinvar, located in Lebanon, Tennessee, has emerged as a notable specialist in high-efficiency condensing boilers and water heating solutions tailored for commercial deployments. AERCO, operating as a Watts brand from Blauvelt, New York, delivers condensing commercial boilers and high-efficiency water heaters that align with stringent efficiency mandates. Miura Boiler, with its Hunt Valley, Maryland presence, focuses on modular low NOx steam boilers engineered for commercial food processing and industrial applications where emissions compliance and space efficiency are paramount. Burnham Commercial Boilers, based in Lancaster, Pennsylvania, supplies commercial-grade boilers and heating systems that bridge residential and commercial use cases. Laars Heating Systems, situated in Hartford, Connecticut, addresses HVAC and process heating requirements through a portfolio of commercial boilers and water heaters optimized for integrated building systems.
Market concentration metrics indicate a relatively fragmented competitive environment, with the top three firms collectively holding approximately 28.5 percent of total market revenue and the top five firms accounting for roughly 38.0 percent. This concentration profile suggests that while scale players command meaningful share, there remains substantial room for specialized providers, regional champions, and technology-focused entrants to capture value through differentiated offerings, service excellence, and application-specific expertise. Our competitive analysis evaluates each major player across dimensions including product breadth, technological differentiation, channel strength, and recent strategic moves that signal future market direction.
Regulatory and Operational Dynamics Influencing 2026 Investment Decisions
The commercial boilers market does not operate in a policy vacuum. Recent regulatory and operational developments are reshaping the cost-benefit calculus for equipment selection, installation, and ongoing compliance. In the food processing sector, Arla Foods Ingredients documented the installation of a new e-boiler at its Danmark Protein whey processing facility in February 2025. This 16 MW capacity system replaces traditional gas boilers and enables 72-hour unsupervised operation, illustrating how electrification and automation are converging to redefine operational resilience in commercial thermal applications.
Subsidy frameworks are also altering adoption economics. A Danish dairy facility secured a DKK 4.5 million subsidy for a 2 MW biomass boiler, achieving annual natural gas replacement savings of 505,000 cubic meters and a payback period of 3.77 years, according to an IEA Bioenergy case study from December 2025. Such incentive structures demonstrate that sustainability investments can deliver compelling financial returns when aligned with appropriate policy support and facility-specific energy profiles.
Regulatory oversight of inspection and compliance costs continues to evolve. The Washington State Department of Labor & Industries amended boiler rules effective July 1, 2025, increasing fees by the fiscal growth factor rate of 6.41 percent for boiler and pressure vessel inspections. This adjustment underscores the importance of factoring total lifecycle compliance costs into procurement decisions rather than focusing solely on upfront equipment pricing. Meanwhile, utility and energy efficiency programs are reinforcing combustion efficiency standards. The Illinois Ameren program, as of December 2025, requires post-tune-up checks and compliance verification for greenhouse boiler installations, highlighting the growing expectation that operators maintain documented efficiency performance throughout equipment lifespans.
Commercial Boilers Market
Additionally, sector-specific technical references such as the Focus on Energy 2025 Technical Reference Manual provide incremental measure cost estimates for dairy farm water heating applications, reflecting the increasing granularity with which operators are evaluating efficiency upgrades. These dynamics collectively signal that the commercial boilers market is being reshaped not only by technology and demand but also by a complex matrix of compliance obligations, incentive structures, and operational benchmarking standards.
What the Full Research Report Delivers
This strategic preview is intended to demonstrate the analytical rigor and practical relevance of our comprehensive Commercial Boilers Market study. The complete report extends far beyond the macro indicators and competitive snapshots outlined here. It provides executives with a structured intelligence toolkit that includes detailed segmentation analysis across fuel types, technology configurations, capacity ranges, and end-use verticals, presented in a format that supports direct integration into capital planning, vendor evaluation, and market entry strategies.
Readers will find in-depth profiles of the key market participants, including assessments of product portfolio alignment, regional coverage, technological differentiation, and strategic positioning relative to evolving efficiency and emissions standards. The report also incorporates an examination of the regulatory and subsidy landscape, translating policy developments into actionable implications for procurement timing, technology selection, and total cost of ownership calculations. Market concentration analysis is calibrated to help both incumbents and new entrants understand the share distribution dynamics that influence pricing power, partnership opportunities, and competitive threat assessment.
Furthermore, the study contextualizes historical performance data alongside forward-looking projections to help organizations distinguish between short-term cyclical fluctuations and durable structural shifts. This distinction is critical for avoiding misaligned investments and for building resilient strategies that can adapt as fuel markets, regulatory frameworks, and technology adoption curves continue to evolve through the end of the decade.
Strategic Imperative for 2026 and Beyond
As the commercial boilers market advances toward its 2032 valuation targets, the organizations that will thrive are those that treat market intelligence as a continuous input to strategic decision-making rather than a periodic reference exercise. The convergence of efficiency mandates, fuel transition incentives, electrification pilots, and compliance cost adjustments is creating a environment where generic procurement approaches carry escalating risk. Precision matters. Understanding which technology pathways align with specific facility profiles, which regulatory developments will affect operating costs, and which competitive players are best positioned to deliver reliable integration and service support can determine whether a capital investment delivers expected returns or becomes a source of operational friction.
Steam Boiler System Market
Our full market research report is designed to close the information gap between high-level industry awareness and the detailed, operationally relevant intelligence that enterprise leaders require. By synthesizing macro growth data, segmentation insights, competitive profiling, and regulatory context into a cohesive analytical framework, the study provides a foundation for informed decision-making across procurement, engineering, financial planning, and market strategy functions. We invite stakeholders to access the complete report to obtain the full depth of segmentation data, competitive assessments, and forward-looking projections that will support confident strategic action throughout 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Commercial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com