

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting SPD Market Hits $215M in 2025, Projects 6.98% CAGR Through 2032

Strategic Resilience: Navigating the Surge Protection Device Market Outlook 2026-2032
The global electrical infrastructure landscape is undergoing a fundamental transformation. As electrification accelerates across industrial, commercial, and residential sectors, the vulnerability of sensitive electronic assets to transient voltage spikes has become a critical board-level concern. Surge Protection Devices (SPDs) are shifting from passive compliance components to active, intelligent elements of broader power management strategies. For executives planning capital allocation and risk mitigation in 2026 and beyond, understanding the trajectory of this market is no longer optional—it is a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research dedicated to the Surge Protection Device (SPD) Market. This study is designed to equip decision-makers with the granular intelligence required to navigate a moderately growing yet highly fragmented competitive landscape. By analyzing historical performance from 2020 through 2025 and projecting forward to 2032, this report offers a robust framework for assessing market health, competitive positioning, and emerging risk factors.
Market Trajectory and Macro Economic Signals
The baseline data indicates a market in steady expansion, driven by infrastructure modernization and heightened awareness of electrical safety standards. Valued at approximately 163.15 Million USD in 2020, the market has demonstrated consistent upward momentum, reaching an estimated 215.0 Million USD by 2025. This growth reflects a compound annual growth rate that underscores the sector's resilience against broader economic fluctuations.
Our forecast model projects continued expansion through the end of the decade. Starting from a 2026 baseline of 223.3 Million USD, the market is expected to climb steadily, reaching significant milestones by 2032. The trajectory suggests a healthy CAGR of approximately 6.98 percent over the forecast period. This rate indicates sustained demand without the volatile boom-and-bust cycles seen in some technology sectors. For investors and corporate strategists, this stability suggests that SPDs represent a reliable component of a diversified clean-tech or industrial portfolio. However, raw revenue figures only tell part of the story. The real value lies in understanding the velocity of adoption across different product categories and the pricing power held by major manufacturers amidst changing raw material costs.
Product and Type Segmentation: The Shift Toward Integration
The market is not monolithic. Our analysis dissects the revenue streams into distinct product architectures, revealing where the volume lies and where innovation is concentrated. The Hard-Wired segment continues to command the largest share of market revenue, reflecting its entrenched position in industrial and heavy commercial infrastructure. However, the Plug-In segment remains a vital dynamic area, particularly for retrofit markets and rapid deployment scenarios. Line Cord and Power Control Device categories, while smaller in total volume, serve specific niche requirements that often carry higher margin potential due to specialized application needs.
Furthermore, the classification by device type reveals a complex hierarchy of protection levels. Type 1 devices maintain a strong presence, primarily driven by mandatory installation requirements in certain jurisdictions for service entrance protection. Type 2 devices represent a critical layer for distribution panels and are often the largest volume drivers in commercial renovations. Type 3 devices, catering to point-of-use protection, complete the layered defense strategy. Understanding the interplay between these types is essential for suppliers who must advise end-users on comprehensive system design rather than selling isolated components. The revenue distribution across these categories highlights where competitive pressure is highest and where differentiation opportunities exist.
Discharge Current and End-User Dynamics
Performance specifications remain a key battleground. The market is segmented by discharge current capacity, ranging from Below 10 kA to Above 25 kA. The 10-25 kA segment currently represents a significant portion of revenue, balancing performance requirements with cost constraints for typical commercial applications. High-capacity units above 25 kA are crucial for industrial settings where surge energy is substantial, while lower ratings serve sensitive electronic equipment in residential or light commercial contexts. Our report details how shifts in equipment sensitivity are influencing these capacity requirements.
End-user segmentation further clarifies demand drivers. The Industrial sector accounts for the largest share of revenue, reflecting the high cost of downtime and equipment damage in manufacturing environments. This segment demands robust solutions with high Short Circuit Current Ratings (SCCR) and compliance with stringent international standards. Commercial applications follow, driven by building code updates and the proliferation of IT infrastructure in office and retail spaces. The Residential segment, while smaller in total revenue, is experiencing evolving dynamics due to insurance incentives and smart home integration. Each end-user group presents distinct buying behaviors, procurement cycles, and sensitivity to price increases in raw materials.
Regional Landscape and Competitive Concentration
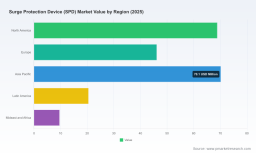
Geographically, the market exhibits a diversified footprint. North America and Asia Pacific represent significant revenue centers, reflecting strong industrial bases and active regulatory environments in these regions. Europe maintains a steady presence, heavily influenced by IEC standards and stringent building codes. Latin America and the Mideast and Africa regions offer growth potential, though often subject to different economic volatility and infrastructure investment cycles. Our full report provides the detailed regional breakdown necessary to assess market entry risks or expansion opportunities, without revealing the specific proportional splits that competitors might exploit.
The competitive landscape is moderately concentrated. The top three players hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This fragmentation suggests that while established players dominate, there is room for specialized challengers or regional specialists to gain traction through innovation or niche service offerings. The market is not a duopoly; it is a contested arena where technological differentiation and compliance certification are the primary barriers to entry.
Competitive Profiles: Leaders and Strategic Moves
Several key companies define the current competitive equilibrium. Schneider Electric SE continues to strengthen its position with integrated solutions. Their recent focus on the Acti9 iPRD integrated Type 2+3 plug-in SPDs for commercial and industrial panels demonstrates a strategy of embedding protection directly into distribution boards. With End-of-Line monitoring and remote indication capabilities, Schneider is moving toward service-oriented value propositions.
ABB Ltd maintains a broad portfolio across Type 1, Type 2, and Type 3 categories. Their modular and industrial OVR ranges are designed for compliance with both IEC 61643 and UL 1449, catering to global projects requiring multi-standard certification. This flexibility allows ABB to serve multinational clients with harmonized specifications.
Siemens AG leverages its strong foothold in low-voltage switchgear with the BoltShield family. By integrating ground reference monitoring directly into panels, Siemens reduces installation complexity and enhances system visibility. This integration aligns with broader trends in digitalization and panel-level intelligence.
Eaton Corporation plc focuses on high-integrity solutions within power distribution systems, UPS, and switchgear. Their emphasis on high SCCR ratings and UL 1449 compliance targets safety-critical applications where failure is not an option. Eaton's product strategy often centers on reliability and integration with broader power management ecosystems.
Mersen SA distinguishes itself through specialized technology like the Surge-Trap TPMOV series. With thermal protection and fail-safe disconnection features, Mersen addresses the longevity and safety concerns of industrial and residential users. Their recent updates to technical documentation reflect a commitment to staying aligned with the latest UL 1449 5th Edition and NEC requirements.
Phoenix Contact GmbH & Co. KG targets the precision end of the market with the TERMITRAB Complete series. These ultra-narrow, pluggable modular SPDs are optimized for measurement and control signals, MCR technology, and industrial Ethernet. Their recent extensions for SPE and APL applications in hazardous areas highlight the growing need for surge protection in process automation and extreme environments.
Surge Protection Device (SPD) Market
Recent Developments and Corporate Momentum
The period leading into 2026 has seen active product development among these leaders. In October 2025, Schneider Electric launched their integrated iPRD Type 2+3 SPD for Acti9 and KQ loadcentre distribution boards. This product was designed as plug-in ready, eliminating the need for bolt-on enclosures or upstream MCBs, which streamlines installation and reduces labor costs.
Earlier in the year, Phoenix Contact extended their TERMITRAB Complete surge protection range in March 2025. The new versions are optimized for Single Pair Ethernet (SPE) and Advanced Physical Layer (APL) applications, specifically addressing the needs of process automation and hazardous area environments. This move signals a response to the increasing connectivity demands in industrial IoT.
In February 2026, Mersen updated their Surge-Trap UL/CSA Surge Protective Devices brochure and National Electrical Code Requirements flyer. This update ensures customers have the latest guidance on UL 1449 5th Edition and NEC compliance, reinforcing Mersen's focus on regulatory adherence as a competitive advantage.
Worldwide Ethernet Surge Protector Market
Industry Dynamics: Regulations, Costs, and Maintenance
Market growth is not occurring in a vacuum. Regulatory frameworks are tightening, influencing both product design and adoption rates. The UL 1449 5th Edition remains a critical standard, requiring SPDs to provide clear end-of-life status visibility. This mandate shifts the value proposition from simple hardware sales to lifecycle management, enabling proactive maintenance planning. Similarly, the IEC 61643-11:2025 standard establishes updated AC SPD performance parameters for low-voltage applications, requiring manufacturers to continuously validate their testing protocols.
Cost pressures are also shaping the market. Increased costs of energy and raw materials are being passed down to end-users. This inflationary environment has the potential to slow the adoption of premium surge protection solutions, particularly in price-sensitive residential or retrofit sectors. Stakeholders must weigh the upfront cost against the long-term risk of equipment damage. Additionally, installation labor costs remain a barrier. Professional electrician installation for whole-house SPDs can add significant expense per unit, acting as a friction point for residential adoption.
Maintenance economics are another critical factor. The increased maintenance cost of SPDs due to required periodic checking and replacement of components such as gas discharge tubes and MOVs adds to the total cost of ownership. Companies that offer solutions with easier maintenance access or longer component life may gain a competitive edge in segments where operational expenditure is closely scrutinized.
The Strategic Value of This Report
In a market driven by technical specifications, regulatory compliance, and shifting cost structures, intuition is not enough. This report provides the detailed segmentation data, company profiles, and dynamic analysis needed to make informed decisions. We delve into the specific revenue contributions of each product type, the precise market share held by key regions, and the granular breakdown of end-user demand.
Stakeholders in procurement, product development, and strategy will find actionable intelligence on where the market is heading. Whether you are assessing a new manufacturing line, evaluating a potential acquisition, or planning a market entry strategy, the depth of analysis contained in this study offers a distinct advantage. We have mapped the competitive moves, analyzed the regulatory tailwinds, and quantified the growth vectors.
To access the full dataset, including specific regional revenue splits, detailed product segment breakdowns, and comprehensive competitor benchmarking, we invite you to visit the source webpage for this market research. The complete intelligence package is available there for download, providing the precise numbers required to finalize 2026 planning and secure your position in the evolving Surge Protection Device Market.
For detailed analysis of this topic, please visit the official page: Surge Protection Device (SPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com