

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Massage Chair Market to Hit $344.8M by 2032, Driven by 6.98% CAGR

The Massage Chair Market in 2026: Strategic Imperatives for Market Leaders
The global landscape for therapeutic seating has entered a defining phase. As organizations navigate the transition from 2025 into the 2026 fiscal cycle, the massage chair market presents a compelling intersection of wellness consumerism, engineering innovation, and shifting supply-chain realities. For executives, investors, and product strategists, the question is no longer whether the category will expand, but how to position portfolios, pricing architectures, and channel strategies to capture disproportionate value in a rapidly maturing ecosystem. Our latest market research delivers a granular, forward-looking blueprint designed specifically to inform high-stakes decision-making throughout the 2026 planning horizon.
This analysis is structured as a strategic preview rather than a static data dump. We will map the macro trajectory, unpack the competitive architecture, and highlight the operational dynamics that will dictate margin performance and market share allocation. Yet the true foundation of this intelligence lies in the complete dataset, segment-level breakdowns, and scenario models that follow. What appears here is the analytical scaffolding; the full structural load-bearing capacity is reserved for stakeholders who access the comprehensive report.
The Macro Trajectory and Structural Momentum
The historical record sets a clear baseline. Between 2020 and 2025, the category navigated exceptional volatility before settling into a robust recovery and expansion cycle. Initial pandemic-era disruptions gave way to sustained demand as home wellness investments matured into long-term lifestyle priorities. By 2025, the total market had climbed to 215.0 million USD, reflecting a decisive rebound from earlier contractionary pressures and establishing a solid launchpad for the coming forecast window.
Looking ahead to 2026 and beyond, the trajectory maintains disciplined acceleration. The market is projected to reach 232.09 million USD in 2026, with growth compounding steadily through the end of the decade and into the early 2030s. By 2032, the sector is positioned to approach 344.8 million USD, underpinned by a forecast-period CAGR of 6.98 percent. This is not speculative optimism; it is a mathematically anchored projection derived from multi-year historical inputs, validated adoption curves, and forward-looking demand modeling that accounts for both consumer behavior and enterprise procurement cycles.
The strategic implication for leadership teams is clear. A near-seven-percent annualized expansion over a six-to-seven-year horizon creates both opportunity and risk. Early movers who align product roadmaps, inventory positioning, and regional go-to-market tactics with this growth cadence will capture compounding advantages. Laggards, conversely, will face escalating acquisition costs and compressed differentiation windows as the competitive field tightens around high-margin segments.
Segment Architecture and the Shift Toward Intelligent Wellness
beneath the aggregate numbers lies a structural transformation in how therapeutic seating is engineered, positioned, and adopted. The category has evolved beyond conventional mechanical roller systems into intelligent, sensor-driven platforms that blend ergonomic precision with adaptive wellness protocols. Traditional designs continue to anchor a substantial portion of baseline demand, particularly in price-sensitive and utility-focused applications. Yet the growth engine is unmistakably oriented toward advanced robotic and AI-integrated configurations that deliver personalized massage sequences, automated body mapping, and enhanced user-clinical alignment.
Application dynamics further illustrate this bifurcation. Residential deployments remain a dominant consumption vector, driven by sustained home wellness adoption, aging demographics, and premium lifestyle upgrades. At the same time, commercial utilization is carving out a credible, high-value niche. Hospitality operators, premium wellness centers, corporate relaxation zones, and specialized therapy clinics are increasingly integrating advanced seating into guest experience and employee well-being programs. The interplay between these two application streams creates distinct pricing tiers, channel requirements, and service expectations that must be navigated with precision.
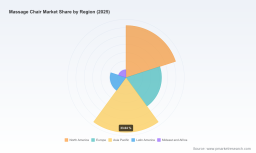
Equally critical is the geographic dispersion of demand. North America continues to command a formidable share, reinforced by established premium wellness purchasing patterns and a mature retail ecosystem. Europe maintains a substantial footprint shaped by varying regulatory environments and localized health-and-wellness preferences. Asia Pacific represents a high-velocity growth corridor, where rising disposable income, urbanization, and expanding domestic manufacturing capabilities are accelerating both consumption and export competitiveness. Latin America and the Middle East and Africa, while currently smaller in absolute terms, are emerging as strategic considerations for forward-looking players evaluating diversification and long-term footprint expansion.
The strategic takeaway is that market leadership in 2026 will not be earned through volume alone. It will be secured by players who can align product complexity, regional compliance readiness, and channel execution with the specific demand rhythms of each segment. Generic positioning will increasingly yield to segment-specific architectures that balance innovation with accessibility.
Competitive Architecture: A Field Defined by Differentiation
The competitive landscape is characterized by concentrated leadership and highly differentiated value propositions. Market concentration remains meaningful, with the top three players accounting for an estimated 48.5 percent of total share and the top five expanding that footprint to approximately 57.8 percent. This concentration signals a market where scale, brand trust, and proprietary engineering create formidable moats. Yet it also leaves clear entry and expansion pathways for manufacturers that can leverage specialized technology, regional partnerships, or targeted premium positioning to carve out defensible niches.
Several established players exemplify the strategic directions currently reshaping the field. Human Touch, headquartered in Long Beach, California, has built its identity around state-of-the-art robotic massage chairs, zero-gravity recliners, and wellness solutions anchored in patented technologies such as CirQlation and HT Flex. Their recent showcase of the Novo XT and Super Novo X at CES 2026 highlighted whole-body massage innovations and practical design features like teardrop doors, signaling a continued emphasis on user accessibility alongside advanced therapeutic capability.
Massage Chair Market
Osaki, operating from Japan, has positioned itself at the premium intersection of full-body massage and intelligent health detection. Its portfolio features 4D and 5D configurations, SL Flex track mechanisms, and automated body-scan programs that adapt delivery to individual anatomical profiles. The company’s continued presence at high-profile events such as the Las Vegas Furniture Market 2026, where it exhibited models including the Platinum Escape Duo 4D and OS-Pro 4D+3D, underscores a deliberate strategy of maintaining visibility in both consumer-facing and trade-oriented channels.
OSIM, based in Singapore, brings an extensive patent portfolio of over 250 technologies to the category, including signature innovations like V-Hand and Tui-Na gliding mechanisms. Its full-body shiatsu and zero-gravity offerings have earned endorsement from the American Chiropractic Association, a credential that reinforces clinical credibility and supports premium pricing in health-conscious consumer segments. Body Friend Co., Ltd., from South Korea, has pursued a similarly technology-forward path, combining 4D full-body massage with patented walking-leg technology, zero-gravity design, heat integration, airbag compression, and foot rollers. Its January 2026 CES showcase of the 733 massage chair and Pharaoh Q AI massage chair reflected a clear push toward AI-enhanced health solutions and robotic precision.
Additional players deepen the competitive mosaic. FAMILY INADA, rooted in Osaka, Japan, has built a legacy around high-performance shiatsu massage chairs and was recognized for introducing the first automatic shiatsu chair, maintaining a focus on specialized wellness therapy solutions. Ceragem, also headquartered in South Korea, leans into luxury positioning with zero-gravity designs, SPINE-Tech spinal therapy, Pro Dual Engine architecture, and custom automatic modes that appeal to consumers seeking clinically adjacent comfort. Ogawa, operating from Switzerland, emphasizes luxury massage chairs and zero-gravity recliners with advanced wellness features tailored for both home environments and professional settings.
The competitive lesson is straightforward. The market rewards precision engineering, credible wellness claims, and differentiated user experiences. It penalizes undifferentiated me-too products that compete solely on price. In 2026, manufacturers will need to decide whether to lead through technology depth, brand heritage, clinical alignment, or regional specialization—and then commit resources accordingly.
Operational Dynamics: Regulation, Supply Chain, and Pricing Realities
Beyond product and competition, market performance in 2026 will be shaped by an ecosystem of operational forces that demand proactive management. Regulatory compliance is no longer a background concern. In North America, massage chairs must satisfy CPSC safety standards and FTC advertising guidelines governing electrical products, establishing clear boundaries for product design, labeling, and promotional claims. Firms that treat compliance as an afterthought risk delays, reputational exposure, and channel friction; those that embed it into development cycles gain speed-to-market advantages and retailer confidence.
Trade policy and import dynamics add another layer of complexity. Recent sector analysis indicates that tariffs on Chinese-origin massage chairs in the 15 to 20 percent range have been absorbed largely through supply-chain adaptations rather than passed fully to consumers. This suggests that strategic sourcing decisions, tariff engineering, and logistics reconfiguration are actively reshaping cost structures and margin profiles. Companies that rely on rigid sourcing models without contingency planning may find their pricing competitiveness eroded over time, while those with diversified supplier networks and flexible logistics architectures can maintain margin resilience.
Luxury Massage Chair Market
On the macro side, industry projections point to continued expansion in the North American premium segment, with projected growth in the 5 to 7 percent CAGR range driven by AI-integrated wellness features. This signals that premiumization is not a transient trend but a structural shift tied to consumer expectations for personalization, predictive health insights, and elevated experiential design. At the same time, labor cost dynamics and advanced engineering portfolios continue to support premium pricing among Japanese manufacturers, reinforcing the value of patent density and design heritage in high-margin wellness models.
Financing and access mechanisms also influence purchasing behavior. Certain models from established brands qualify for HSA and FSA eligibility, enabling tax-advantaged wellness purchases that can meaningfully lower the effective price barrier for consumers. This creates a subtle but real differentiator in price-sensitive premium segments and underscores the importance of aligning product classification, documentation, and channel messaging with reimbursement pathways where applicable.
What the Full Study Delivers for 2026 Decision-Making
The insights outlined here are intended to establish analytical credibility and frame the strategic questions that leadership teams must answer. But the complete research deliverable goes far beyond this preview. The full report provides a multi-layered architecture of actionable intelligence designed to support product planning, pricing strategy, channel allocation, and competitive response throughout the 2026 to 2032 forecast window.
Stakeholders who access the complete study will find detailed historical reconstructions, validated forward projections, and segment-level demand modeling that clarify where growth is concentrated and how it is likely to evolve. The analysis dissects type-specific adoption patterns, application-driven purchasing behavior, and regional momentum with the granularity required to inform capital allocation and go-to-market sequencing. It maps competitive positioning with depth, examining technology differentiation, patent leverage, channel strength, and brand credibility across the leading manufacturers and emerging challengers. It also integrates operational dynamics—regulatory requirements, import and tariff considerations, premiumization economics, and financing accessibility—into a practical framework for margin management and risk mitigation.
Equally important, the full report is structured for execution. It translates market signals into decision-ready guidance, helping teams evaluate product roadmap priorities, identify underserved segment opportunities, anticipate competitive moves, and calibrate pricing and inventory strategies against realistic demand scenarios. Rather than offering abstract commentary, it equips executives with the evidentiary foundation needed to justify investment choices, reduce forecasting uncertainty, and align cross-functional teams around a shared market view.
Strategic Positioning for the Next Cycle
The massage chair market in 2026 is not simply expanding; it is maturing into a technology-intensive, regulation-aware, and segment-differentiated category. Growth is real, but it is uneven across types, applications, and regions. Competitive advantage will accrue to organizations that treat the category with strategic seriousness: investing in differentiated engineering, aligning compliance and supply-chain strategies with shifting trade realities, and deploying channel and pricing models that reflect the distinct economics of residential versus commercial demand.
This preview offers the strategic contours. The complete market research provides the operational blueprint. For decision-makers who require precise segment intelligence, validated growth projections, and competitive scenario analysis to guide 2026 planning, the full study is the essential next step. Access the comprehensive report to convert market visibility into executable advantage.
For detailed analysis of this topic, please visit the official page: Massage Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com