

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vitamin C Market Hits $187M in 2025, Poised for Steady 5.35% CAGR Through 2032

Strategic Intelligence for the Ascorbic Acid Market: Navigating Growth, Volatility, and Competitive Shifts in 2026
Executive Perspective: Why This Analysis Matters Now
The global Vitamin C (Ascorbic Acid) market is entering a decisive phase. After years of sharp capacity expansion, pricing turbulence, and supply chain realignment, industry participants are pivoting from volume-driven growth to value-based positioning. For executives, procurement leaders, and strategy teams, the decisions made in 2026 will shape margin resilience, sourcing security, and competitive positioning through the end of the decade. Our latest market research delivers a structured, evidence-based view of this transition, giving decision-makers the clarity required to act with confidence.
The market's trajectory reflects a complex interplay of production economics, regional dynamics, and application-specific demand. The research framework captures these forces in a single, actionable architecture, enabling stakeholders to benchmark their exposure, anticipate inflection points, and align investment or sourcing strategies accordingly. This introduction outlines the strategic value of the study, previews its analytical scope, and explains how the findings translate into concrete 2026 planning priorities.
Macro Trajectory: Framing the Growth Narrative Without the Noise
Understanding where the Vitamin C market is headed begins with a disciplined read of its historical arc and forward path. The market has expanded steadily from its base period through the most recent baseline year, reflecting consistent demand pull from food and beverage fortification, personal care innovation, and pharmaceutical formulation requirements. Our forecast window projects continued expansion, anchored by a compound annual growth rate that underscores durable, mid-single-digit momentum rather than speculative spikes.
This growth profile matters because it defines the operating environment for 2026 strategy. A stable expansion trajectory suggests that headline volume will continue to reward scale players, but it also signals that incremental share gains will increasingly come from differentiation, not mere capacity. The research translates this macro view into scenario-ready intelligence, allowing users to test how shifts in feedstock costs, trade policy, or formulation trends might alter their own demand-supply balance. Rather than presenting a static snapshot, the analysis maps the conditional pathways that determine whether a company captures the upside of growth or absorbs its friction.
Inside the Study: Practical Intelligence for Sourcing, Pricing, and Portfolio Decisions
This report is built for execution, not abstraction. It combines quantified market sizing with qualitative market mechanics, producing a reference that can be directly embedded into sourcing reviews, R&D prioritization, and regional expansion evaluations. The study is organized to give cross-functional teams a shared language for discussing Vitamin C procurement and development.
- Comprehensive market sizing across the historical period and the full forecast horizon, with transparent methodology notes that support internal validation and board-level reporting.
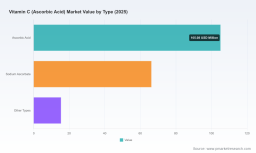
- Granular segmentation analysis that dissects demand by type, application, and region, enabling stakeholders to identify where concentration risk, growth pockets, and substitution pressure are most pronounced.
- Competitive profiling of leading producers, including their production footprints, grade specializations, and strategic repositioning in response to recent market events.
- Event-driven market dynamics tracking, covering feedstock movements, price normalization patterns, regulatory recognition of sustainable production, and trade policy exposures that influence landed cost and supply availability.
- Practical guidance on interpreting price signals, assessing supplier reliability, and evaluating the strategic implications of premium-grade formulations versus bulk standard offerings.
Each section is designed to answer a specific decision question. For procurement teams, the emphasis is on cost drivers, contract timing, and supplier diversification logic. For commercial and R&D leaders, the focus shifts to application momentum, formulation trends, and the premiumization pathways that justify higher-margin positioning. For corporate strategy, the report provides the structural view needed to assess entry, expansion, partnership, or divestiture options with a clear sense of where value is being created and eroded.
Competitive Landscape: Strategic Differentiation Among Core Players
The competitive structure of the Vitamin C market is defined by a mix of Western specialty positioning, large-scale Chinese manufacturing, and targeted product innovation in stabilized or sustainable formats. Understanding these strategic postures is essential for evaluating supplier risk, negotiating terms, and identifying partnership opportunities. The research profiles several central participants whose actions are reshaping the market's equilibrium.
dsm-firmenich has concentrated its Vitamin C strategy on premium-grade positioning through its Quali-C ascorbic acid offering, produced exclusively at its Dalry, Scotland facility. As the sole Western manufacturer of this grade, the company anchors its value proposition in pharmaceutical-grade and high-purity applications where traceability, consistency, and regulatory confidence carry premium weight. The company's decision to divest its Jiangshan Vitamin C plant in China and refocus on Scotland reflects a deliberate shift from broad-volume exposure toward differentiated, higher-trust supply. More recently, the company has observed a broader industry transition among Chinese producers toward value-over-volume focus, with pricing stabilization and gradual upward movement following an extended period of volatility.
BASF SE employs a bio-based and standard ascorbic acid approach, leveraging production capabilities in China and collaborating on joint developments with ADMI. Its orientation toward nutraceutical and sustainable applications signals a strategy built on ingredient credibility and environmentally aligned sourcing narratives, which are increasingly relevant for consumer-facing brands and formulation teams seeking cleaner-label or sustainability-supported inputs.
Several Chinese producers remain central to global supply, each with distinct strategic emphases. CSPC Pharmaceutical Group Ltd focuses on bulk ascorbic acid and derivatives with strong alignment to pharmaceutical and food-grade standards. Northeast Pharmaceutical Group Co., Ltd integrates large-scale ascorbic acid output with peptide and API lines, positioning the ingredient within broader pharmaceutical value chains. Zhejiang NHU Co., Ltd is recognized for capacity-leading production spanning food, feed, and industrial uses, making scale and breadth of application a defining feature of its market role. Shandong Luwei Pharmaceutical Co., Ltd produces ascorbic acid, sodium ascorbate, and calcium ascorbate with an explicit focus on waste recycling and resource efficiency, an orientation that has received external recognition for comprehensive utilization of fermentation waste. North China Pharmaceutical Group Co., Ltd supports global supply through standard ascorbic acid production, reinforcing the role of established Chinese manufacturers in maintaining baseline availability across multiple downstream channels.
In the premium and specialty segment, Evonik Operations GmbH distinguishes itself through stabilized ascorbic acid forms, including its Golden C NG line developed for cosmetics. This positioning illustrates how formulation performance, stability, and bioavailability are becoming differentiators in personal care applications where efficacy claims and sensory performance increasingly drive ingredient selection.
Vitamin C (Ascorbic Acid) Market
Market Dynamics: Cost, Trade, and Sustainability Signals Shaping 2026
Beyond company-level strategy, the market is being reshaped by a set of operational and policy dynamics that directly affect pricing behavior, sourcing choices, and regional competitiveness. These forces do not operate in isolation; they interact to create the short-term volatility and longer-term structural shifts that decision-makers must monitor.
One of the most immediate influences on manufacturing economics is the movement of upstream feedstock costs. In the first quarter of 2026, glucose feedstock prices declined, reducing production costs at key ascorbic acid plants. This input relief has contributed to a broader price normalization pattern: ascorbic acid prices declined steadily into early 2026, moving from the prior year's level to approximately 2.95 USD per kilogram, compared with 3.58 USD per kilogram a year earlier. The decline reflects Chinese supply normalization and softer demand conditions, creating a buying environment that differs markedly from the volatility of the preceding 18 months. For sourcing teams, the strategic question is not simply whether prices are lower, but how long the current equilibrium is likely to persist and which suppliers can sustain reliability if conditions reverse.
Trade policy remains a material factor, particularly for markets exposed to Chinese-origin supply. Vitamin C imports from China face a 30 percent tariff rate in the US market, following the expiration of a temporary truce in August 2024. This tariff environment affects landed costs, supplier selection, and the economic calculus of regional diversification. Companies dependent on China-linked supply chains must weigh the short-term appeal of normalized pricing against the structural risk of tariff exposure and potential policy re escalation.
Sustainability and regulatory recognition are also becoming strategic signals rather than peripheral considerations. In March 2025, Shandong Luwei Pharmaceutical Group received the High-quality Development Benchmark Enterprise Award for its pilot project on comprehensive utilization of waste from Vitamin C fermentation. This kind of recognition matters because it reflects operational efficiency, environmental compliance, and the growing relevance of waste-to-resource models in fermentation-based manufacturing. For buyers and partners, such benchmarks can serve as indicators of process maturity and long-term operational resilience.
Product-level innovation continues to reinforce segmentation. Evonik's introduction of Golden C NG in early 2025, a premium gold-stabilized ascorbic acid form designed for high-performance cosmetics, highlights how stability and bioavailability enhancements are enabling premiumization in personal care formulations. Similarly, SEIWA KASEI's launch of iVC 3GA-green, a plant-derived sustainable anti-aging vitamin C ingredient for cosmetics, underscores a broader trend toward bio-based, sustainability-positioned ingredients in the cosmetics channel. These developments indicate that application-level differentiation is increasingly tied to ingredient form, origin narrative, and performance claims, not just bulk price.
Where Value Is Created: Strategic Implications for 2026 Decision-Making
The convergence of these dynamics creates a clear strategic message for 2026. First, pricing relief and input cost declines should not be mistaken for a permanent reset. They represent a window in which procurement strategy, contract structure, and supplier diversification can be reassessed with greater leverage. Second, segmentation is deepening: players competing on bulk commodity terms face a different set of risks and rewards than those competing on pharmaceutical-grade purity, stabilized cosmetic forms, or sustainability credentials. Third, geographic and trade exposure must be modeled explicitly, particularly where tariff structures and supply normalization intersect.
For organizations evaluating supplier relationships, the research provides the context needed to distinguish between temporary price advantages and durable sourcing reliability. For product developers, it clarifies where application demand is strongest and how ingredient form innovation is reshaping formulation choices. For investors and corporate strategists, it maps the concentration and competitive posture of the market, helping to identify where consolidation, capacity adjustment, or premiumization is most likely to alter share and margin dynamics.
Conclusion: Turning Market Intelligence into Advantage
The Vitamin C market is not defined by a single trend, but by the interaction of cost cycles, regional supply shifts, application-specific demand, and strategic repositioning among leading producers. In this environment, generic market narratives are insufficient. Decision-makers need a rigorous, scenario-ready view of how sizing, segmentation, competition, and dynamics fit together, and how each lever affects their own operating context.
This study is designed to provide exactly that view. It synthesizes historical performance, forward projections, competitive profiles, and event-driven market intelligence into a coherent framework for 2026 strategy. By foregrounding the structural forces that shape pricing, supply security, and segmentation, it enables organizations to move beyond reactive responses and toward deliberate positioning.
3-O-Ethyl-L-Ascorbic Acid Market
For the full analysis, including detailed segmentation breakdowns, competitive benchmarking, and scenario-based interpretation, please refer to the complete report. The complete market research provides the depth required to translate these strategic signals into concrete sourcing, investment, and product decisions across the forecast period.
For detailed analysis of this topic, please visit the official page: Vitamin C (Ascorbic Acid) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com