

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Modified Starch Market to Hit $17.17 Billion by 2032, Driven by 3.5% CAGR

Navigating the Starch Shift: Strategic Intelligence for the 2026 Modified Starch Market
The modified starch industry stands at a critical inflection point as global supply chains recalibrate and formulation demands grow increasingly complex. For corporate strategists, procurement leaders, and product development executives, the ability to anticipate market velocity, understand competitive positioning, and navigate regulatory friction is no longer optional—it is a fundamental requirement for margin preservation and market share expansion. Our latest Modified Starch Market research delivers a rigorous, forward-looking assessment designed specifically to inform enterprise decisions across the 2026–2032 horizon. This executive briefing outlines the structural forces shaping the sector and demonstrates how scenario-based intelligence translates into actionable strategy.
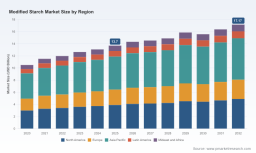
The market has moved through a sustained expansion phase over the past half-decade, with total industry revenue climbing from approximately $10.5 billion in 2020 to roughly $13.7 billion at the close of the 2025 base year. Our baseline trajectory projects continued growth through the end of the forecast window, with the total addressable market reaching an estimated $17.17 billion by 2032. Embedded within this macro arc is a compound annual growth rate of 3.5 percent, a figure that appears measured on the surface but masks significant variation across product categories, application verticals, and regional ecosystems. Executing effectively in 2026 requires understanding where value is concentrating, which pricing mechanisms are stabilizing or distorting margins, and how leading players are reallocating capital toward higher-margin functional ingredients and specialty applications.
Why 2026 Demands a Strategic Reset
The opening months of this year have already introduced several compounding pressures that will define competitive outcomes for the remainder of the decade. Raw material volatility remains the most immediate concern. Tapioca starch, a cornerstone input for numerous modified formulations, experienced a continuous upward price trajectory and tightening supply conditions heading into 2026, pushing benchmark pricing near the $490 per ton threshold. Concurrently, U.S. potato starch export values displayed broad dispersion throughout 2025, ranging from $0.40 to $5.74 per kilogram depending on grade, origin, and end-use specification. These divergences are not isolated noise; they signal structural shifts in agricultural yield expectations, logistics constraints, and demand-side competition between food-grade and industrial-grade users. Companies that rely on static sourcing models will face margin compression, while those equipped with cross-commodity substitution frameworks and forward-buying intelligence will secure a meaningful cost advantage.
Regulatory evolution is equally disruptive. Updated FDA labeling guidance has accelerated demand for label-friendly modified starches that do not require E-number designations or complex chemical nomenclature on packaging. Simultaneously, the European Union has introduced CN code refinements and duty adjustments for HS 35051090, reshaping landed-cost calculations for exporters and importers operating in or transiting through European markets. On the trade policy front, 2025 U.S. tariff adjustments on modified starch products have already transmitted direct price impacts across import channels, altering the relative competitiveness of domestic versus foreign supply. These overlapping regulatory and fiscal shifts are rewriting the rules of market entry, pricing architecture, and formulation strategy. A static view of compliance is now a strategic liability.
What the Deep Dive Delivers
Our research methodology combines top-down macroeconomic reconciliation with bottom-up segmentation mapping, channel-level consumption analysis, and primary intelligence from industry participants, formulation laboratories, and supply chain operators. The resulting report is engineered to support multi-departmental decision-making rather than serving as a generic market overview.
The analysis is structured around several practical modules. Segmentation mapping dissects demand by product type, application category, and geography, isolating where volume growth, pricing power, and margin expansion are converging. Competitive benchmarking profiles established multinational producers alongside regional specialists, examining capacity footprints, product portfolios, distribution reach, and recent moves in innovation, acquisitions, and contract wins. Supply chain and raw material tracing evaluates feedstock availability, conversion economics, and logistics bottlenecks that influence pricing stability and lead times. Regulatory and trade scenario modeling quantifies the potential impact of labeling mandates, duty adjustments, and tariff regimes under multiple adoption speeds. Forecast modeling extends deterministic projections alongside sensitivity cases to help planners test assumptions around volume elasticity, input cost shocks, and competitive entry timing.
Each section is designed to answer operational questions rather than academic ones. Where should a food manufacturer prioritize reformulation efforts to align with clean-label momentum? Which industrial application segments offer the most defensible growth given current capacity deployment? How do regional demand profiles diverge in their preference for physically modified, chemically modified, or enzymatically modified variants? The report provides the analytical scaffolding to answer these questions without oversimplifying the trade-offs.
Competitive Landscape: Precision Over Noise
The modified starch ecosystem is defined by a concentrated core of large-scale, globally integrated players and a broader tier of specialized manufacturers that compete on regional proximity, niche functionality, or specific feedstock expertise. Concentration metrics indicate that the top three firms command roughly 35 percent of industry revenue, while the top five extend their share to approximately 45 percent. This structure creates a dual dynamic: scale players benefit from cross-category leverage, global distribution, and sustained R&D investment, while mid-tier and regional producers compete through customization, shorter supply chains, and rapid response to local regulatory or formulation requirements.
Among the scale leaders, Cargill continues to reinforce its position across personal care, food and beverage, and industrial applications, with recent product introductions highlighting first-of-its-kind dent-corn modified starch designed to enhance sauce color and texture, complemented by a pectin replacer. Ingredion remains a central force in texturizing, thickening, and stabilizing solutions spanning food, beverage, and non-food uses, leveraging extensive application laboratories to accelerate customer adoption. Roquette Frères draws on a diversified feedstock base—corn, wheat, potatoes, tapioca, and peas—and maintains an extensive catalog of variant formulations, giving it flexibility across multiple end markets. Tate & Lyle emphasizes clean-label positioning and specialty portfolios, aligning product development with consumer-facing transparency trends. Grain Processing Corporation rounds out the diversified competitive set with acid-modified, oxidized, pregelatinized, and cationic starch types serving both industrial and food-grade specifications.
The regional specialist tier adds further texture to the competitive map. Indian manufacturers including Premier Starch, Angel Starch & Food Pvt. Ltd., Jay Dinesh Chemicals, Vinayak Ingredients, and SPAC Starch Products India Private Limited serve demand across packaging adhesives, paper, paints, textiles, and functional food ingredients, with several firms leveraging decades of chemical modification experience or specialized export channels. SMS Corporation Company Limited has emerged as a notable tapioca starch player, presenting high-performance modified solutions at recent international trade events and earning recognition for plant-based manufacturing innovation. AEBE U.A. and Global Bio-Chem Technology Group Company Limited extend the competitive fabric in European and Chinese contexts respectively, each addressing food and industrial demand with regionally optimized portfolios.
Vigilance around commercial activations is essential. Recent activity underscores how quickly advantage can shift. SMS Corporation deployed high-performance modified starch solutions at Fi Europe 2025 and presented modified tapioca starch innovations while securing Plant-Based Manufacturing of the Year at Gulfood Manufacturing 2025. Cargill’s March 2025 product innovation announcement demonstrated how targeted formulation breakthroughs can reshape competitive expectations within specific application categories. These moves illustrate the importance of tracking not only installed capacity and historical revenue but also pipeline momentum, trade-show positioning, and application-specific claim development.
Modified Starch Market
Corn Starch Market
Where Decision-Makers Will Find Immediate Leverage
Translating market intelligence into operational advantage requires focusing on the intersections where demand, regulation, and input economics intersect. Several pressure points deserve particular attention in 2026 planning cycles.
- Label-friendly reformulation pathways. Updated expectations around ingredient declaration are accelerating the search for modified starches that preserve functionality without triggering consumer skepticism. Companies that can map functionality requirements to label-compatible options will reduce time-to-market for reformulated SKUs while protecting brand equity.
- Feedstock diversification and substitution logic. With tapioca pricing under upward pressure and potato starch values fluctuating widely by grade, procurement strategies must incorporate cross-feedstock flexibility. Decision-makers benefit from understanding which physical, chemical, or enzymatic modification routes preserve performance when switching base materials.
- Regional tariff and duty navigation. EU duty adjustments and U.S. tariff impacts on imports require dynamic landed-cost modeling. Firms that integrate trade-policy scenarios into sourcing and pricing decisions will avoid margin surprises and position themselves to capture arbitrage where feasible.
- Application-specific margin profiles. Food and beverage formulations continue to drive substantial demand, but industrial segments including paper, textiles, and animal feed each present different volume-to-value ratios, cyclicality patterns, and specification sensitivity. Allocation of commercial resources should reflect these structural differences rather than treating the market as a monolith.
- Competitive signaling and innovation cadence. Recent trade-show deployments, product launches, and award recognitions reveal where leading players are placing bets. Monitoring these signals helps anticipate shifts in availability, pricing negotiation leverage, and customer expectations in key accounts.
The 2026 Playbook: From Intelligence to Execution
Strategy in this market is not about predicting a single outcome; it is about building the organizational agility to respond as conditions evolve. The most effective 2026 playbooks integrate scenario-driven sourcing, formulation flexibility, and competitive awareness into daily operating rhythms rather than treating them as annual planning exercises. Procurement teams should test multiple feedstock pathways against margin targets, sales and marketing groups should align value propositions with label and regulatory realities in each target geography, and product development should maintain a library of functionally equivalent options that can be swapped as input economics or compliance requirements change.
Execution also depends on knowing which questions to ask and where the answers reside. The full research report provides the granular segmentation detail, company-level profiling, scenario quantification, and regional breakdowns necessary to convert high-level strategy into investment decisions, pricing frameworks, and channel priorities. Markets of this scale and complexity reward analytical precision, and the difference between reactive positioning and proactive advantage often comes down to the quality of the underlying intelligence.
Decisions made in the coming quarters will influence cost structures, formulation roadmaps, and competitive exposure well beyond the immediate fiscal year. Organizations that equip themselves with robust, forward-looking market intelligence will be better positioned to navigate raw material volatility, regulatory change, and competitive innovation with confidence. The complete study offers the depth required to act decisively—unlocking the segment-level dynamics, competitive benchmarks, and scenario models that can shape profitable strategy across the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Modified Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com