

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vacuum Pump Market Hits $6.7B in 2025, Projected to Reach $9.91B by 2032 at 5.74% CAGR

Precision Low Pressure Determining Profits: A 2030 Strategy Outlook for Vacuum Pumps Market
The global industrial landscape is defined by an increasing demand for process precision. From semiconductor fabrication to pharmaceutical purification, the ability to control atmospheric conditions is no longer a utility but a core competency. As we move through 2026, the Vacuum Pumps Market has solidified its reputation as a critical enabler of modern manufacturing and scientific advancement. This analysis provides an executive preview of the upcoming comprehensive market intelligence report, detailing the strategic value electromagnetic in navigating the next seven years of growth.
For senior executives and strategic planners, the 2026 fiscal year represents a pivotal checkpoint. While the market has demonstrated resilience through the volatile 2020 to 2025 period, the forecast period from 2026 to 2032 requires a nuanced understanding of technological shifts and regulatory pressures. The complete study offers an exhaustive examination of these variables, but this overview highlights the foundational data and strategic imperatives that every stakeholder must consider immediately.
Macro Trend Analysis Revenue Trajectory And CAGR Implications
The overarching financial narrative for the vacuum pump industry is one of steady, compounding growth grounded in industrial modernization. Market intelligence derived from historical performance between 2020 and 2025 indicates a mature expansion phase. In 2020, the total revenue landscape stood at 4900.0 Million USD. By the base year of 2025, this figure has grown to 6700.0 Million USD. This historical momentum sets the stage for the forecast period, which projects the market to reach approximately 9910.0 Million USD by 2032.
The Compound Annual Growth Rate (CAGR) for the 2026 to 2032 period is calculated at 5.74 percent. This rate signals a healthy expansion that outpaces general industrial inflation in several key sectors. It implies that demand is being driven not merely by population growth or replacement cycles, but by new applications requiring precise pressure environments. For decision makers, this CAGR suggests that investing in vacuum technology supply chains now will yield substantial returns by the end of the decade. However, realizing this potential requires distinguishing between broad market growth and segment-specific opportunities.
The transition from 2026 to 2032 is not linear. There are inflection points expected around 2028 and 2030 where capacity expansions in emerging economies and technology adoption in developed markets will converge. Our detailed modeling accounts for these variances, ensuring that financial planning is based on realistic scenario analysis rather than simple extrapolation. The data indicates that while the headline numbers are robust, the path to achieving them involves navigating specific technological and regulatory hurdles that will define market winners and losers.
Automotive Vacuum Pump Market
Regional And Segment Diversity Driving The Base Year
Understanding the composition of the 6700.0 Million USD base year revenue is essential for identifying where growth originates. The market is geographically distributed across five key regions, each contributing differently to the cumulative total. The Asia Pacific region stands as a dominant force, contributing 3270.09 Million USD, reflecting the concentration of manufacturing and semiconductor assets in this area. North America follows with a substantial contribution of 1320.91 Million USD, driven by advanced research facilities and established industrial bases.
Europe represents a mature market with a revenue contribution of 1315.48 Million USD, characterized by high regulatory standards and specialized application requirements. The remaining share is divided between Latin America at 412.81 Million USD and Mideast and Africa at 380.71 Million USD. These figures illustrate that while Asia Pacific leads in volume, the developed markets in North America and Europe maintain significant value due to higher technology adoption rates and stricter compliance needs. Strategic allocation of resources must respect these regional weightings while anticipating shifts in manufacturing gravity.
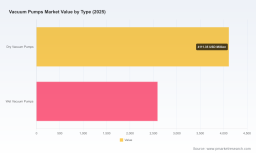
Beyond geography, the market is bifurcated by technology type and application sector. In terms of technology, Dry Vacuum Pumps account for 4111.35 Million USD, whereas Wet Vacuum Pumps contribute 2588.65 Million USD. This split highlights a prevailing preference for dry technologies in applications where oil contamination is a critical risk factor, such as in high purity processes. The application segment is equally diverse. Semiconductor Manufacturing leads significantly with 3059.07 Million USD, underscoring the industry's reliance on vacuum environments for lithography and etching.
Other significant sectors include Chemical and Petrochemical at 1352.93 Million USD, Food and Beverage at 670.55 Million USD, and Pharmaceutical at 666.4 Million USD. The Others category rounds out the landscape with 951.05 Million USD. These figures confirm that while semiconductors are the primary growth engine, the market is diversified enough to absorb shocks in any single sector. A robust portfolio strategy should acknowledge this balance. The full report provides granular breakdowns of these splits, but the macro composition clearly indicates where the largest revenue pools reside in 2026.
Competitive Dynamics And Concentration Risk
The industry structure reveals a moderately concentrated landscape where scale and technological expertise create barriers to entry. Market concentration data indicates a CR3 of 45.0 percent and a CR5 of 57.0 percent. This means that the top three players control nearly half of the market value, while the top five control more than half. For new entrants or smaller players, this suggests that competing on price alone is insufficient; differentiation through service, reliability, and specific application engineering is required to capture share from these incumbents.
Key players shaping this dynamic include Edwards Vacuum, headquartered in Burgess Hill, United Kingdom. Their focus remains on highly specialized offerings for critical industrial processes. The Busch Group, based in Germany, continues to leverage its engineering heritage to dominate specific niches within the dry pump segment. Atlas Copco of Sweden maintains a strong presence through its broad industrial portfolio, recently reinforcing its quality and safety standards with ISO 9001:2015, ISO 45001:2018, and ISO 14001:2015 certifications applicable to vacuum pumps production, marketing, and installation as of January 2026.
German engineering continues to feature prominently with companies such as Pfeiffer Vacuum, Becker Pumps, Leybold, KNF Neuberger, and VACUUBRAND. Each brings distinct technological advantages, ranging from laboratory scale solutions to heavy industrial throughput. In the USA, Gast Manufacturing provides critical domestic capacity, while Alcatel Vacuum Technology in France adds to the European technical depth. The presence of EVP Vacuum Solution, which exhibited at the 2025 18th International Vacuum Exhibition in Shanghai showcasing vacuum pumps, valves, and coating systems, highlights the active engagement of specialized players in regional trade ecosystems.
Recent corporate activities illustrate the competitive intensity. Edwards Vacuum attended the K Show 2025 to demonstrate vacuum pumps' role in plastics degassing applications, signaling expansion into packaging material processing. Similarly, The Busch Group presented the MINK MH series vacuum pumps and blowers at the Hannover Trade Show 2025, emphasizing continuous innovation in product lines. These developments suggest that competition is not static; it is driven by active product launches and demonstration of applicability in emerging use cases. Our report analyzes these moves in detail to predict future market share shifts.
Regulatory Tailwinds And Technical Standards Shaping Dynamics
Regulatory and standards frameworks are becoming as influential as demand drivers in the vacuum pump market. Compliance is no longer just a legal requirement; it is a product specification requirement that dictates market access. In the United States, the Harmonized Tariff Schedule for 2026 covers semiconductor vacuum pumps with flat panel display use under HS code 84141015. This classification affects cost structures and supply chain logistics for manufacturers targeting the US semiconductor market, requiring precise customs and tariff planning.
Vacuum Pumps Market
Environmental regulations are also reshaping equipment requirements. A2L refrigerant standards in 2026 mandate certified spark-resistant vacuum pumps and recovery machines for HVAC systems. This regulatory shift creates a specific sub-demand for safety-certified equipment, separating compliant manufacturers from those without necessary certifications. In the UK, the BSI MCE/8 committee is developing UK input into ISO/TC112 vacuum technology standards for vacuum pumps. This standardization effort aims to harmonize technical specifications, potentially lowering barriers to trade while raising the baseline for technical performance.
Environmental compliance extends beyond HVAC. Eureka Patsnap analysis shows that vacuum pumps enhance advanced catalytic converter production under tightening environmental regulations. This link between vacuum technology and emissions control equipment opens new revenue streams in the automotive aftermarket and industrial exhaust treatment sectors. Furthermore, biosafety requirements are influencing procurement in healthcare and research. US BSL-3 laboratory design standards specify central vacuum pumps in negatively pressurized rooms. This specification ensures a stable demand from government and private research institutions upgrading their containment capabilities. These regulatory factors are integrated into our market forecasts to assess their Quantitative impact on volume and pricing.
Operational Scope And Value Of The Complete Intelligence Report
This overview serves as a strategic primer, but the full Vacuum Pumps Market research report provides the depth required for execution. The complete study goes beyond historical data and totals. It includes a comprehensive survey of technological innovations affecting pump efficiency, noise reduction, and longevity. It analyzes the supply chain dynamics, including raw material availability and manufacturing capacity constraints that could impact lead times in 2026 and beyond.
The report details distribution channels, identifying whether direct sales or distributor networks dominate in specific regions and application sectors. It also examines pricing trends, distinguishing between premium segments where performance justifies higher costs and commoditized segments where margin compression is a risk. For investors and corporate strategists, the report includes an analysis of M&A activity, potential partnership opportunities, and risk factors related to geopolitical tensions affecting cross-border trade of industrial machinery.
By downloading the full report, stakeholders gain access to detailed segmentation data that allows for precise market sizing in specific niches. It offers a competitor benchmarking section that compares the product portfolios and strategic focus of the key companies mentioned earlier. This allows for a clear identification of gaps in the market that your organization can exploit. The study is designed to be a living reference for capital allocation, R&D prioritization, and market entry strategies throughout the forecast period.
Conclusion For The 2026 Decision Makers
The Vacuum Pumps Market is positioned for significant growth, but the value creation opportunities are unevenly distributed. The 5.74 percent CAGR to 2032 is attractive, but capturing it requires navigating a landscape defined by high regulatory standards, concentrated competition, and specific technological demands. The base year of 2025 set a strong foundation with 6700.0 Million USD in revenue, and the trajectory toward nearly 10000 Million USD by 2032 is clear.
However, the difference between average performance and market leadership lies in the details. Understanding which applications will drive the highest margins, which regions offer the fastest growth relative to risk, and how regulatory changes like the A2L standards or BSL-3 requirements will alter procurement specs is essential. The macro numbers provide confidence in the market direction, but the strategic execution depends on granular intelligence. This report provides the necessary tools to move from observation to action. We invite you to access the full intelligence suite to secure your strategic advantage in this vital industrial sector.
For detailed analysis of this topic, please visit the official page: Vacuum Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com