

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Transceiver Market Hits $13.9B in 2025, 13.5% CAGR to 2032

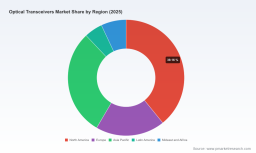
Illuminating the Path: Strategic Intelligence in the 2026 Optical Transceivers Market
The optical transceiver sector has evolved from a commoditized component market into a critical technology battlefield defining the pace of digital infrastructure. As enterprises confront the simultaneous pressures of artificial intelligence workloads, cloud migration, and geopolitical supply chain realignment, the decisions made in 2026 will determine competitive positioning for the remainder of the decade. This market research report delivers a comprehensive strategic framework for navigating a landscape where speed, power efficiency, and supply resilience now supersede pure cost leadership. By synthesizing five years of historical trajectory with a disciplined forecast horizon, the analysis equips procurement leaders, product strategists, and capital allocators with the clarity required to act decisively in an environment of unprecedented technical inflection.
The opening sections of this briefing establish the foundation for understanding why optical transceivers now command boardroom attention. The narrative moves beyond surface-level hardware metrics to examine how signal integrity, thermal constraints, and packaging innovation are reshaping architectural choices across hyperscale facilities and enterprise campuses alike. Readers will encounter a structured methodology that separates transient market noise from durable demand drivers, ensuring that strategic plans rest on verifiable trends rather than speculative headlines. This approach matters because the deployment cycles of high-speed connectivity equipment now exceed those of traditional IT refresh programs, making accurate foresight a direct determinant of operational continuity and capital efficiency.
A Market in Accelerated Expansion: From HistoricalMomentum to the 2032 Horizon
The demand curve for optical transceivers has demonstrated remarkable consistency over the past five years. Beginning at a baseline of approximately 7.25 billion USD in 2020, the sector advanced through successive growth cycles to reach an estimated 12.33 billion USD in 2024 and 13.90 billion USD in 2025. This sustained escalation reflects more than cyclical IT spending. It captures a structural shift in how data is routed, processed, and stored across globally distributed computing environments. The transition from legacy interconnect architectures to high-density, high-bandwidth optical solutions has become a prerequisite for supporting the throughput requirements of modern applications.
Projections for the coming years extend this trajectory with considerable confidence. The market is expected to surpass 15.70 billion USD in 2026, climb past 17.70 billion USD in 2027, and approach 20.95 billion USD by 2028. The forecast continues its ascent through the remainder of the decade, culminating in an estimated valuation near 33.79 billion USD by 2032. Underpinning this growth path is a compound annual growth rate of 13.5 percent across the forecast window. Such a rate places optical transceivers among the faster-expanding segments of the broader networking hardware ecosystem. The implication for corporate planners is straightforward: demand will not plateau at current generation speeds, and capacity planning must accommodate iterative bandwidth upgrades rather than single-cycle procurement events.
This growth profile is not uniform across all deployment contexts. The analysis distinguishes between near-term volume drivers and longer-cycle infrastructure buildouts, allowing decision-makers to align inventory strategy with realistic consumption curves. By focusing on the aggregate expansion while reserving segment-level granularity for the full report, the document preserves strategic focus without diluting the precision required for operational execution. Executives who internalize this top-line velocity can better anticipate supply agreement timelines, evaluate manufacturing partnership risks, and sequence capital deployment in alignment with actual market absorption rather than optimistic projections.
Architecture of the Analysis: What the Report Delivers
The research is constructed to function as a working instrument rather than a static snapshot. Its structure is designed to answer three recurring questions that confront industry players: where demand is concentrating, which technology families are gaining displacement advantage, and how competitive positioning will evolve as manufacturing footprints and regulatory frameworks shift. Each section integrates quantitative modeling with qualitative assessment of product roadmaps, partnership activity, and regional policy direction, creating a multi-dimensional view that supports scenario planning.
A central pillar of the report examines the segmentation of the market across geographic regions, product type families, and end-use application categories. Rather than presenting these dimensions as isolated tables, the analysis traces how they interact. For example, the distribution of demand across regions is evaluated alongside local manufacturing incentives, spectrum and deployment regulation, and logistics constraints that influence lead times and unit economics. The type-family review maps the evolving share of established form factors against emerging high-density packages that are being optimized for artificial intelligence clusters and high-performance computing environments. Application-level assessment differentiates between facilities driven by centralized compute aggregation, carrier-grade transport requirements, and enterprise networking refresh cycles. This layered approach enables buyers to identify which combinations of region, type, and application present the most favorable risk-reward profile for their specific deployment objectives.
Beyond segmentation, the report provides an operational toolkit for procurement and product strategy teams. It includes supplier capability mapping, technology readiness assessments, and an evaluation of component-level bottlenecks that affect yield and pricing stability. The document also incorporates a structured review of recent product launches, demonstrations, and corporate transactions that signal changes in competitive momentum. By translating these events into strategic implications, the report helps readers distinguish between marketing announcements and meaningful shifts in supply capability. This distinction is particularly valuable in a sector where announcement cycles move quickly and technical validation lags behind press releases, making disciplined analysis a safeguard against misaligned investment decisions.
Competitive Dynamics: Leaders, Challengers, and Emerging Vectors
The competitive landscape is defined by a concentrated group of established players and a growing cohort of specialized manufacturers racing to capture share in high-speed transceiver categories. The report profiles a set of core companies whose product architectures, manufacturing footprints, and partnership strategies are reshaping the market hierarchy. Coherent Corp. has emphasized vertically integrated silicon photonics and advanced VCSEL arrays, including coherent transceiver demonstrations targeting hyperscale data center and enterprise interconnect requirements. Broadcom Inc. has directed its efforts toward co-packaged optics platforms and optical I/O engines that integrate photonics more directly with compute silicon, a direction that is increasingly relevant for artificial intelligence infrastructure. Cisco Systems, Inc. continues to leverage its comprehensive portfolio of pluggable transceivers spanning 100G to 800G and beyond, reinforcing its position across data center and metro networking environments.
In the component and module supply chain, Lumentum Holdings Inc. and Applied Optoelectronics, Inc. represent manufacturers focused on high-volume datacom transceivers and high-speed form factors, including 800G and 1.6T solutions. Accelink Technology Co., Ltd. and Eoptolink Technology Inc. illustrate the expanding capacity of regional manufacturers supplying silicon photonics-based transceivers and active optical cables for cloud and data center applications. Huawei Technologies Co., Ltd. maintains its emphasis on pluggable optical modules aligned with intelligent computing and data center interconnect scenarios. Sumitomo Electric Industries, Ltd. contributes expertise in compact, low-power transceiver designs for high-speed communications, while Source Photonics, Inc. and NeoPhotonics Corporation advance photonic integrated circuit-based transceivers for demanding connectivity applications. Infinera Corporation rounds out the competitive picture with intelligent coherent pluggable transceivers designed for long-haul and metro optical networks.
Recent corporate activity underscores the velocity of strategic repositioning. Broadcom announced the shipment of an industry-first 102.4 Tbps co-packaged optics Ethernet switch with 200 Gbps per channel performance, signaling a major step in switch-level optical integration. Coherent demonstrated its 1.6T-SR8 optical transceiver based on advanced 200G VCSEL technology, reinforcing progress in short-reach high-density transmission. Cisco completed the acquisition of CoreOptics, expanding its optical networking engineering capabilities across Europe and Asia. Credo Technology Group Holding Ltd introduced its ZeroFlap optical transceiver line for secure high-speed connectivity across 400G, 800G, and 1.6T configurations. Jabil launched 1.6T transceivers targeting AI, high-performance computing, and high-speed data center interconnects. Each of these developments carries implications for supply availability, performance ceilings, and partnership opportunities. The report translates such events into actionable strategic readouts rather than isolated news items.
Market concentration remains a defining feature of this landscape. The analysis notes a high degree of consolidation among leading participants, with a significant share of revenue attributed to a small group of dominant firms. This concentration amplifies the importance of supplier diversification, qualification strategy, and long-term sourcing agreements. Buyers that depend on a narrow supplier base face elevated exposure to capacity constraints and pricing volatility, while those that construct multi-source pathways can improve negotiation leverage and resilience. The report evaluates these concentration dynamics in a way that supports both tactical procurement decisions and broader risk management frameworks.
Structural Forces Shaping the 2026 Decision Environment
Strategic planning in this market cannot be separated from the operational and regulatory pressures that influence cost structures and availability. Manufacturing complexity remains a persistent constraint. Precision photonic components, including laser diodes and photodetectors, require stringent manufacturing tolerances, and the associated production demands contribute to elevated unit costs for 400G and 800G modules. High manufacturing costs and component supply chain vulnerabilities are not abstract concerns; they directly affect lead-time predictability, inventory carrying requirements, and the economics of multi-generation deployment plans. The report examines these cost drivers in detail, helping organizations distinguish between temporary margin pressure and structural price floors that will shape long-term budgeting.
Geopolitical and regulatory forces add another layer of complexity. US-China technology export restrictions are disrupting supply chains for key optical components, altering the geography of available sourcing options and increasing the importance of compliance-aware procurement strategies. At the same time, the EU’s push for digital sovereignty is stimulating local manufacturing and innovation in optical transceivers, encouraging regional capacity expansion and creating new partnership possibilities for organizations operating in or serving European markets. Harmonized regulation under the European Electronic Communications Code is also streamlining spectrum allocation and infrastructure deployment approvals, reducing friction in certain rollout scenarios while reinforcing the strategic value of regionally aligned supply chains.
These dynamics intersect with technology roadmaps in ways that matter for 2026 planning. The transition toward higher per-lane data rates, more compact packaging, and improved power efficiency is accelerating, but the pace of adoption differs across application contexts. Hyperscale environments are pushing the frontier of co-packaged and highly integrated optical solutions, while telecommunications and enterprise networks are balancing performance upgrades against total cost of ownership and deployment complexity. The report maps these divergences carefully, enabling readers to align technology adoption timing with the specific performance, power, and cost constraints of their own environments.
Why This Report Is a Strategic Imperative
Organizations evaluating optical transceiver procurement, product planning, or investment allocation face a market that rewards foresight and penalizes reactive decision-making. The combination of rapid bandwidth escalation, concentrated supplier influence, and shifting regulatory conditions means that strategy must be informed by both market-level trajectory and the operational realities of component supply. This research report provides that foundation by integrating historical performance, forward-looking growth modeling, competitive intelligence, and structural risk assessment into a single coherent framework.
Optical Transceivers Market
High Speed Optical Transceiver Market
The full study expands on every dimension introduced here. It delivers detailed segmentation analysis across regions, type families, and application categories, along with supplier profiles, technology readiness assessments, and scenario-based guidance for procurement and product strategy. For decision-makers who require confidence in their 2026 planning, the complete report offers the depth required to move from general market awareness to precise strategic action. The trajectory is clear, the competitive stakes are rising, and the organizations that act with informed precision will be best positioned to capture the value created by the next phase of optical interconnect expansion.
For detailed analysis of this topic, please visit the official page: Optical Transceivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com