

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Prostaglandin Market Hits $4.47B in 2025, Targets $6.9B by 2032 at 6.5% CAGR

Strategic Intelligence for the Prostaglandin Market: Navigating the 2026–2032 Horizon
At PW Consulting, we recognize that decisions made in 2026 ripple through balance sheets, R&D roadmaps, and supply chain resilience well beyond the next fiscal cycle. The prostaglandin market sits at a critical inflection point: therapeutic demand continues to expand, manufacturing footprints are being reconfigured under new tariff and regulatory regimes, and scientific breakthroughs are reshaping how these potent lipid mediators are produced and delivered. Our latest Prostaglandin Market study is designed to convert this complexity into a clear, actionable strategic framework for executives, procurement leaders, and competitive intelligence teams.
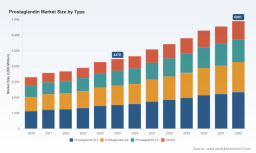
The analysis draws on verified market intelligence covering the historical window from 2020 through 2025 and extends a disciplined forecast out to 2032. Across this horizon, the market is projected to grow at a compound annual growth rate of 6.5 percent, measured in millions of U.S. dollars. The top-line trajectory reflects sustained momentum: valuation rose from 3.3 billion U.S. dollars in 2020 to approximately 4.47 billion U.S. dollars by 2025, and is positioned to reach roughly 4.65 billion U.S. dollars in 2026 before climbing further toward 6.9 billion U.S. dollars by 2032. These figures establish a robust baseline, but the real strategic value lies beneath the aggregate: the structural forces, competitive moves, and policy shifts that will determine which organizations capture margin, which face input-cost exposure, and which reposition successfully as the landscape changes.
This article previews the analytical depth and practical utility embedded in the full report. It is intentionally designed as a strategic trailer—demonstrating the rigor and relevance of our methodology while preserving the granular segmentation, proprietary modeling outputs, and detailed scenario tables for the complete publication.
Why 2026 Is a Pivotal Year for Prostaglandin Strategy
The 2026 decision environment is shaped by the convergence of three forces. First, therapeutic demand continues to be anchored by established and emerging ophthalmic therapies, while adjacent indications sustain steady utilization across gynecology, obstetrics, and cardiovascular applications. Second, the manufacturing ecosystem is undergoing a visible stress test. Concentration in API production has created dependency dynamics that are now intersecting with trade policy, logistics recalibration, and regional capacity expansion. Third, regulatory and scientific developments are altering both the competitive field and the technical pathways available to producers.
Our study frames these dynamics not as isolated headlines but as interconnected vectors that feed into supply planning, pricing strategy, portfolio prioritization, and market-entry decisions. For executives, the question is no longer whether the market is growing—it is where durable advantage can be built, and how to structure operations so that growth translates into resilient profitability rather than exposure to input volatility or compliance friction.
Market Trajectory and the Architecture of Demand
The prostaglandin market has demonstrated consistent compounding growth over the past half-decade, with the 6.5 percent CAGR extending predictably into the forecast window. This trajectory is underpinned by mature therapeutic categories as well as incremental adoption in specialized indications. The analysis decomposes this top-line expansion across multiple analytical dimensions—product type, application, and geography—to reveal where growth is concentrated, where substitution risks are emerging, and where structural undercurrents may alter regional and segment-level outcomes.
Readers of the full report will find an integrated view of these dimensions, including the relative contribution of different prostaglandin formulations to overall therapeutic demand and the way application categories interact with regional healthcare access, reimbursement design, and formulation innovation. Rather than presenting segmentation as static tables, the study situates each dimension within the strategic choices it implies: which therapeutic segments are most sensitive to pricing pressure, which geographies reflect expanding access versus saturation, and where cross-segment dynamics create either opportunity or competitive overlap.
Competitive Dynamics and the Concentration Imperative
Industry structure is a central focus of the analysis. Combined market share among the top three participants stands at 58.5 percent, and the top five account for 68.2 percent—a concentration profile that signals both the strength of incumbent scale and the potential for differentiated positioning by specialized manufacturers. The competitive field is represented by a diverse set of players with distinct value propositions and regional footprints.
The study profiles organizations such as Sanofi CEPiA, whose manufacturing capability for prostaglandin active pharmaceutical ingredients anchors its pharmaceutical offering; Kyowa Hakko Pharma, with its focus on commercial prostaglandin compounds; and Cayman Chemical, a key supplier of research and laboratory reagents that supports the broader scientific and discovery ecosystem. Yonsung Fine Chemicals and Johnson Matthey contribute specialized synthesis, catalyst, and intermediate capabilities, while Chirogate and Everlight Chemical participate through analogs and fine chemical manufacturing respectively. The field also includes ANVI Pharma and Manus Aktteva Biopharma LLP as API suppliers for research and commercial production, along with AUSUN Pharmaceutical and Aspen Biopharma Labs, which extend the manufacturing and formulation continuum. Pfizer’s CentreOne operations sustain API production for human and veterinary applications, while EUROAPI and LGM Pharma round out the competitive fabric through API supply and export activity for clinical and commercial use.
Worldwide Prostaglandins and Related Drugs Market
Rather than treating these profiles as static descriptions, the report maps each company’s positioning to strategic implications—where scale confers defensibility, where specialized intermediates or analogs create differentiated risk-adjusted opportunities, and where regional manufacturing footprints intersect with trade and sourcing pressures. The full publication includes comparative strategic assessments and scenario-based placement of each competitive profile within the evolving market structure.
Recent Developments Rewriting the Competitive Playbook
The strategy landscape is being actively reshaped by product launches, regulatory approvals, and scientific advances that alter both demand patterns and production economics. In early 2026, Glaukos received U.S. FDA approval for an NDA supplement enabling re-administration of its iDose TR intracameral implant for patients with open-angle glaucoma or ocular hypertension—a move that reinforces the strategic importance of sustained drug delivery platforms in ophthalmology. During the preceding year, Bausch Health Companies introduced a fixed-dose combination eye drop pairing a prostaglandin analog with a beta-blocker, expanding therapeutic options and addressing adherence considerations. Santen Pharmaceutical’s launch of SETANEO Ophthalmic Solution in Japan further illustrates the ongoing expansion of prostaglandin-based ophthalmic therapies in key markets.
Beyond commercial launches, scientific progress is creating fresh production possibilities. A March 2026 publication in Nature Communications described improved de novo production of prostaglandin F2α from glucose using engineered Yarrowia lipolytica strains—an advance that underscores the potential of biotechnological pathways to influence future cost structures and supply diversification. Together, these developments signal that the competitive field will reward organizations capable of integrating formulation innovation, delivery science, and manufacturing flexibility.
Dynamics That Redefine Supply, Compliance, and Cost
Strategic planning in the prostaglandin market must now account for a set of operating conditions that are materially different from those of the prior cycle. Supply chain concentration remains a defining feature: a substantial share of global API production for prostaglandin analogs is situated in India and China, creating dependency dynamics that link Western manufacturers to source-region economics, logistics realities, and geopolitical considerations. This concentration is not merely an operational detail; it is a strategic risk variable that affects landed cost, continuity planning, and scenario design.
Trade policy has intensified this exposure. The expansion of U.S. Section 301 tariffs on Chinese pharmaceutical imports in early 2025 raised duty rates in certain cases to levels as high as 25 percent, directly increasing landed costs for importers of prostaglandin API. New pharmaceutical tariff measures enacted in early 2025 are also prompting manufacturers to redesign global drug supply chains to mitigate import-cost increases and reduce API sourcing risk. For executives, this means the cost of goods sold cannot be treated as a stable input; it must be modeled under multiple trade and sourcing scenarios, with contingency sourcing, inventory strategy, and regional capacity considerations explicitly integrated.
Regulatory developments add another layer of complexity. The European Chemicals Agency’s SCCS issued an opinion in February 2026 classifying prostaglandin analogues as unsafe for use in cosmetic lash serums due to reproductive toxicity concerns, triggering reformulation requirements across the supply chain. This determination affects more than cosmetic applications; it imposes compliance scrutiny, formulation change requirements, and potential reputational considerations that ripple through ingredient sourcing and downstream product design. Meanwhile, reimbursement infrastructure continues to evolve, with Medicare and Medicaid payment updates that support separate reimbursement under OPPS for CPT codes associated with the iDose TR intracameral implant procedure—an indicator that procedural reimbursement design can materially influence the economics of advanced delivery systems.
Our report integrates these dynamics into a structured “market dynamics” view that ties together supply concentration, tariff exposure, regulatory risk, and reimbursement design. The result is a decision-support framework that helps leaders anticipate disruption, allocate mitigation resources, and identify where proactive reformulation, dual-sourcing, or regional capacity investment can convert risk into competitive insulation.
What the Full Report Delivers for Decision-Makers
The complete Prostaglandin Market study is built for practitioners who need more than directional trends. It combines a rigorous historical-to-forecast model with segment-level analysis, competitive profiling, and scenario-based interpretation. The report is organized to support a range of strategic functions:
- Executive market sizing and trajectory analysis, connecting historical performance with forecast pathways and clarifying the basis for the 6.5 percent CAGR and the forward valuation path to 2032
- Segment mapping across product types, applications, and regions, used to identify where growth, substitution risk, and access dynamics shape strategic priorities
- Competitive positioning analysis for the companies active in API production, intermediates, analogs, fine chemicals, reagents, formulation, and commercial supply, with implications for scale, specialization, and market access
- Integrated dynamics assessment covering supply chain concentration, tariff and trade exposure, regulatory developments, and reimbursement design, with practical guidance on mitigation and adaptation
- Scenario-informed commentary on recent product launches, approvals, and scientific advances, translating external events into strategic implications for R&D, sourcing, and portfolio direction
Throughout, the analysis remains anchored in actionable insight. Rather than enumerating numbers in isolation, the report connects quantitative structure to operational consequences—how a shift in sourcing geography changes cost modeling, how a regulatory determination alters formulation timelines, how a new approval can reposition competitive expectations, and how concentration dynamics influence negotiation leverage and continuity planning.
How to Use This Intelligence in 2026
For 2026 planning cycles, the study is designed to support several core decisions. Procurement and supply chain leaders can use the concentration and trade-policy analysis to strengthen sourcing resilience, evaluate dual-sourcing options, and model landed-cost sensitivity under tariff scenarios. R&D and product strategy teams can leverage the application- and formulation-level perspective to prioritize indications with favorable demand and reimbursement dynamics, while aligning development activity with emerging delivery-science opportunities. Commercial and competitive intelligence teams can use the company profiles and structural concentration data to anticipate positioning shifts, assess market-access implications, and identify where specialized manufacturing capabilities may create differentiated influence.
Crucially, the full report preserves the granular segmentation detail, scenario tables, and proprietary modeling outputs that allow these decisions to be made with precision. The preview presented here is intended to establish confidence in the analytical foundation and the strategic relevance of the findings, while directing readers to the complete publication for the specific breakdowns that underpin execution-level planning.
Prostaglandin Market
Conclusion
The prostaglandin market offers meaningful growth potential, but capturing that potential in 2026 and beyond will require more than confidence in the top-line trajectory. It will require clarity on where concentration creates exposure, where regulation and trade policy alter cost structures, where scientific and formulation advances reshape competitive expectations, and where reimbursement design affects the economics of advanced therapies. PW Consulting’s Prostaglandin Market study provides the structured intelligence needed to navigate these intersecting forces with discipline and foresight.
To access the full segmentation detail, competitive profiles, scenario analysis, and integrated dynamics framework, we invite executives and strategy teams to consult the complete report on the PW Consulting platform. The publication delivers the depth, precision, and applied perspective required to turn market intelligence into durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Prostaglandin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com