

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Micro-Lens Arrays Market Hits $215M in 2025, Projects 6.49% CAGR to 2032

Strategic Imperatives in the Micro-Lens Arrays Market: Forecasting Growth and Operational Resilience Through 2032
The global micro-lens arrays market stands at a critical inflection point as it moves through the second half of the 2020s. For enterprise strategists, optical engineers, and supply chain leaders, understanding the trajectory of this sector is no longer an academic exercise. It is a prerequisite for capital allocation, partnership structuring, and competitive positioning across telecommunications, advanced imaging, and industrial photonics. Our latest market research publication delivers a comprehensive, data-grounded assessment of the micro-lens arrays industry, mapping historical performance, quantifying near-term momentum, and projecting structural shifts that will define the competitive landscape through 2032.
The Macro Trajectory: Tracking Value Creation Across the 2020–2032 Horizon
The market has demonstrated consistent expansion over the past half-decade, with revenue climbing from approximately 163.15 million USD in 2020 to 215.0 million USD in 2025. This progression reflects a steady institutionalization of micro-optics across high-volume manufacturing lines, where precision beam shaping, homogenization, and fiber coupling have transitioned from niche prototypes to embedded production requirements. The momentum carries forward into the forecast window, with the market expected to reach 226.16 million USD in 2026 and continue its upward course toward 344.8 million USD by 2032. The implied compound annual growth rate of 6.49 percent across the 2026–2032 period signals a market that is expanding at a measured but durable pace, driven by application penetration rather than speculative hype.
This trajectory matters for decision-makers because it reveals a sector where incremental volume gains compound with technological refinement. Companies evaluating capacity investments, wafer-level production partnerships, or custom optical design engagements need to see how baseline demand scales against process maturity, material availability, and regional sourcing shifts. Our study isolates these variables, presenting them in a structured framework that connects outright revenue pathways to the operational conditions that enable them.
A Closer Look at the Strategic Content Within the Report
The research was engineered to function as an operational handbook rather than a static statistical summary. It begins with a detailed segmentation architecture that breaks down the micro-lens arrays market across material profiles, optical configurations, application domains, and geographic footprints. Each dimension is examined for its contribution to aggregate revenue, its sensitivity to production economics, and its exposure to evolving end-user requirements. Readers will find granular assessments of aspherical and spherical microlens arrays alongside alternative configurations, with attention to how design geometry interacts with coupling efficiency, pitch accuracy, and system-level integration complexity.
Equally important is the depth of the application analysis. Telecommunications and IT continue to anchor a substantial share of demand, reflecting the sector's reliance on micro-optics for high-density data routing, fiber coupling, and photonic integration. Automotive lighting and sensing applications represent a second major vector, where qualification standards, thermal resilience, and volume scalability shape procurement strategies. Renewable energy, medical imaging, and specialized industrial instrumentation each introduce distinct performance thresholds, and the report dissects how these verticals influence pricing, lead times, and supplier selection criteria. By mapping these application pathways without reducing them to oversimplified rankings, the study equips leaders with the context needed to anticipate cross-vertical competition for capacity and engineering talent.
The forecasting model extends beyond top-line projections. It incorporates sensitivity considerations tied to raw material availability, labor intensity in high-precision polishing and alignment workflows, and the strategic consequences of tariff frameworks that have recently reshaped the economics of imported fused silica substrates and finished arrays. These elements are treated as integral drivers of cost structure and supply continuity, allowing readers to test how their own sourcing strategies would perform under different disruption scenarios.
Competitive Landscape: Capabilities That Define Market Leadership
The industry remains decidedly fragmented, with a competitive field spanning specialized photonics innovators, glass and silica processing experts, and broader optical component suppliers. Our analysis highlights organizations whose manufacturing profiles, design services, and application focus illustrate the strategic diversity of the sector. AGC Inc. leverages high-precision glass microfabrication, molding, and composite technologies to serve applications spanning coherent optical modules, digital cameras, high-brightness LEDs, and OLED systems. This positions the company at the intersection of consumer imaging and high-performance photonic hardware. Holographix LLC has strengthened its role in custom photonics solutions, including a January 2025 launch of dedicated design services for microlens array devices aimed at next-generation photonic technologies. That move underscores a broader market theme: competitive advantage increasingly depends on the ability to translate application-specific optical requirements into reliable, cost-effective manufacturing outcomes.
Axetris AG brings wafer-scale execution to the conversation, producing custom silicon and fused silica microlens arrays on 150mm and 200mm wafers for telecom, datacom, automotive, and consumer markets. Its emphasis on high pitch accuracy and coupling efficiency aligns with the needs of integrated optical systems where alignment tolerances are exceptionally tight. Nanoscribe GmbH complements this landscape with two-photon polymerization-based 3D microfabrication, enabling additively manufactured microlens arrays and complex micro-optics, including freeform and hybrid designs on fibers and chips. That capability matters as system architects explore unconventional optical geometries that cannot be produced through conventional lithographic or molding routes.
Other firms reinforce the breadth of the competitive field. SUSS MicroOptics SA focuses on wafer-level microlens arrays for automotive lighting applications, fiber coupling, photonic integrated circuits, and semiconductor workflows, emphasizing industrial qualification frameworks relevant to automotive supply chains. PowerPhotonic Ltd. specializes in standard and custom one-dimensional and two-dimensional micro lens arrays in high-grade fused silica, supporting fiber coupling with spheric, aspheric, and freeform profiles. Avantier Inc. emphasizes precision-engineered arrays built through high-precision polishing and alignment for machine vision, laser systems, and optical sensing. Thorlabs, Inc. and Edmund Optics Inc. round out the landscape by supplying microlens arrays for light homogenization, beam shaping, high-power LEDs, and broader research or industrial instrumentation. Together, these players illustrate a market where specialization, scale, and service orientation compete simultaneously.
Competitive concentration remains moderate, with the top three and top five firms accounting for a combined share that reflects the fragmented yet increasingly disciplined nature of the sector. The report examines how these concentration levels interact with sourcing concentration risk, particularly where high-precision glass production is clustered in a small number of industrial ecosystems. For procurement and strategy teams, this is not just a market structure observation; it is a stress-test input for evaluating dependency on specific regional supply bases.
Micro-Lens Arrays Market
Market Dynamics Shaping Cost, Continuity, and Sourcing Strategy
Several structural forces are now shaping the economics of micro-lens array production. On the materials side, supply constraints for specialty optical glasses containing rare-earth dopants can introduce periodic shortages that inflate costs and extend lead times during periods of elevated demand. These dynamics intersect with a manufacturing process that depends on highly specialized labor, where precision polishing and alignment requirements drive elevated unit pricing at higher volumes due to stringent process control demands. The result is a cost environment in which volume scaling does not automatically translate into proportionate margin relief.
Trade policy has also become a defining variable. New U.S. tariff measures have imposed additional duties on imported fused silica substrates and finished microlens arrays, altering global supply chain calculations and prompting strategic reorientation toward localized production or alternative sourcing channels. In practice, these measures have accelerated investment in regional manufacturing footprints and diversified supplier portfolios, making supply chain resilience a board-level concern rather than a procurement-side workaround. At the same time, supply chain concentration risk in high-precision glass production ecosystems remains a vulnerability, exposing global supply to geopolitical disruption, natural disaster exposure, and potential export control expansions.
For executives, the practical implication is that micro-lens arrays procurement can no longer be optimized purely on unit price. Sourcing models must account for qualification lead times, regional tariff exposure, material dopant availability, and the capacity of suppliers to sustain process control across ramp cycles. The report translates these pressures into decision frameworks that help organizations distinguish between transient cost fluctuations and structural shifts in the cost base.
Optical Lenses Market
Why This Research Matters for 2026 Decision-Making
As organizations finalize capital plans and supplier strategies for 2026, the micro-lens arrays market presents both opportunity and complexity. Demand is expanding at a durable pace, but the revenue pathway is being shaped by a combination of application migration, material economics, regional trade dynamics, and the growing importance of custom design services. In that environment, strategic advantage belongs to organizations that can read the market with enough granularity to act early and with enough discipline to avoid overcommitting to a single supply chain assumption.
This study was built for that moment. It provides forecast clarity, competitive profiling, segmentation context, and scenario-aware commentary on the forces that will influence pricing, lead times, and sourcing feasibility over the forecast period. It does not simply report where the market has been. It explains how the underlying mechanics of production, qualification, and geopolitical trade policy are likely to shape where the market goes next.
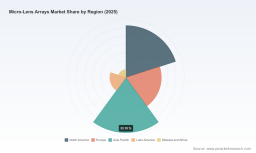
The full publication contains the detailed segmentations, regional revenue distributions, application-level revenue splits, and company-level profiles that decision-makers need to operationalize these insights. Those specifics are reserved for the complete report framework, where they can be examined in the context of the full dataset and the supporting methodology. Readers seeking the complete intelligence set will find the downloadable market research available through our official market research page. This overview is intended to demonstrate the analytical rigor and strategic relevance of the study so that leadership teams can assess its fit for their planning cycle before diving into the full dataset.
For teams evaluating optical supply strategies, capacity partnerships, or photonics-linked product roadmaps, this research provides the structured visibility required to move from intuition to evidence. The micro-lens arrays sector is expanding within a landscape that rewards precision in planning as much as precision in optics. Our analysis is designed to help organizations make that alignment explicit, actionable, and resilient.
For detailed analysis of this topic, please visit the official page: Micro-Lens Arrays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com