

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PA66 Market to Hit $5.95B by 2032, CAGR 2.4% Led by Asia Pacific & Automotive

Strategic Imperatives in the PA66 Engineering Plastics Market: Navigating Growth, Volatility, and Sustainability Through 2032
The global landscape for polyamide 66 engineering plastics is entering a decisive phase. As industries confront supply chain restructuring, intensifying sustainability mandates, and accelerating material substitution pressures, decision-makers require more than macroeconomic snapshots. They need foresight anchored in granular demand trajectories, competitive positioning, and actionable entry strategies. This report delivers precisely that intelligence, mapping the evolution of the PA66 sector from its 2025 baseline through 2032. Built for executives, procurement leaders, and strategic planners, the analysis transforms market complexity into clear operational pathways.
The Trajectory: From Baseline to 2032 Outlook
Over the past half-decade, the PA66 engineering plastics market has demonstrated remarkable resilience amid macroeconomic headwinds and feedstock volatility. Historical consumption patterns reveal a steady upward march, reflecting the material's entrenched role in high-performance applications where thermal stability, mechanical strength, and chemical resistance are non-negotiable. The sector has consistently expanded, with annual valuations climbing through the early 2020s and surpassing mid-five-figure milestones by 2025.
PA66 Engineering Plastics Market
Looking ahead, the forecast period through 2032 presents a nuanced growth narrative. Rather than a straightforward linear ascent, the market is shaped by shifting regional demand centers, evolving application requirements, and structural adjustments in feedstock economics. Premiumization trends continue to drive volume and value metrics upward, while cost pressures in certain geographies introduce tactical complexity for manufacturers and converters alike. The report synthesizes these forces into a cohesive forward-looking framework, enabling stakeholders to anticipate inflection points rather than react to them.
Strategic timing is everything. Understanding where the market stands today, how it has evolved, and where it is headed allows organizations to align capacity planning, partnership development, and product development roadmaps with actual market momentum. This report provides the structural clarity required to make those decisions with confidence.
Sustainability as a Core Competitive Lever
The era of treating environmental compliance as a peripheral concern has ended. In the PA66 sector, sustainability has become a fundamental driver of product differentiation, customer procurement criteria, and long-term market share allocation. Recent developments underscore this transformation. Leading producers have successfully demonstrated the commercial viability of bio-circular feedstocks, achieving measurable reductions in carbon intensity while maintaining performance parity with conventional grades. Certification milestones such as ISCC Plus compliance have transitioned from optional credentials to baseline expectations in key end markets.
Simultaneously, chemical recycling innovations are reshaping the waste-to-value calculus. Proprietary depolymerization pathways now enable closed-loop recovery of nylon 66, positioning circularity not as a theoretical aspiration but as an emerging supply chain reality. Meanwhile, formulation advancements continue to push performance boundaries, with new additive architectures enhancing thermal stability and mechanical endurance for demanding engineering environments. These developments carry direct implications for sourcing strategies, brand positioning, and regulatory preparedness.
Executives who integrate sustainability into their core strategy will capture premium positioning and secure preferential access to increasingly selective downstream customers. Those who treat it as a compliance checkbox risk margin erosion and competitive displacement. The report dissects these dynamics with operational specificity, linking sustainability initiatives to tangible market outcomes.
Engineering Plastics (PBT, PA6 & PA66) Market
Industry Volatility and Tactical Responsiveness
Pricing fluctuations, regulatory adjustments, and feedstock economics remain central to short-term market navigation. Recent price movements highlight the sensitivity of PA66 economics to regional supply-demand imbalances and upstream cost structures. In Asia, market pricing has experienced measurable shifts, reflecting broader commodity dynamics and localized production adjustments. In North America, periodic price revisions by major suppliers have forced downstream stakeholders to recalibrate budgeting assumptions and contract structures.
These pressures are compounded by the foundational chemistry of the material itself. PA66 engineering plastics rely on key upstream intermediates, and any disruption or cost escalation in those supply chains reverberates through the entire value chain. Understanding these linkages is essential for procurement teams, pricing strategists, and production planners who must balance cost containment with supply reliability.
This report does not merely catalog volatility. It contextualizes it. By mapping price behaviors to regional demand patterns, regulatory timelines, and raw material trajectories, the analysis equips decision-makers with the situational awareness needed to structure resilient sourcing agreements, optimize inventory strategies, and anticipate supplier pricing logic before it impacts margin profiles.
Competitive Architecture and Market Concentration
The PA66 engineering plastics market operates within a highly consolidated competitive structure. A relatively small cohort of globally integrated producers dominates value capture, with the top three participants accounting for a substantial share of total industry revenue and the top five commanding an even larger proportion. This concentration reflects the capital intensity of integrated production, the technical barriers to grade development, and the long-term contractual relationships that characterize downstream procurement.
Leading players span multiple geographies and bring distinct strategic advantages to the market. Fully integrated producers with vertically aligned supply chains maintain cost and quality control advantages that translate into pricing stability and grade consistency. Global polymer specialists leverage broad application expertise and extensive compound portfolios to serve demanding sectors. Regional and specialty producers compete through targeted grade optimization, regional proximity, and niche performance claims. Each archetype navigates the market differently, and understanding these distinctions is critical for partnership evaluation, competitive benchmarking, and market entry planning.
Recent strategic actions by key participants illustrate how the competitive landscape is evolving in real time. Capacity and feedstock innovation initiatives are being paired with sustainability certifications to reinforce market positioning. Product launches targeting thermal stability, heat resistance, and electric vehicle requirements demonstrate how grade differentiation is increasingly tied to application-specific performance rather than commodity pricing. These moves are not isolated events. They signal broader shifts in how leading companies are aligning R&D, feedstock strategy, and end-market focus to defend and expand their positions.
The report provides a comprehensive competitive assessment that goes beyond corporate profiles. It evaluates strategic intent, capability positioning, and likely market responses, enabling stakeholders to map competitor behavior against their own strategic priorities.
What the Full Report Delivers
This market research is structured to support decision-making at multiple organizational levels. Rather than offering a static data compilation, the report integrates market sizing, segmentation analysis, competitive intelligence, and forward-looking scenario mapping into a cohesive strategic toolkit. Key components include:
- Comprehensive historical and forecast market sizing across the full assessment period, providing a clear baseline for growth modeling and investment prioritization.
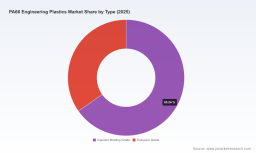
- Segment-level analysis that breaks down demand dynamics by type, application, and regional consumption patterns, enabling targeted market planning without exposing readers to incomplete or misleading micro-data.
- Competitive landscape evaluation covering market concentration, corporate positioning, strategic initiatives, and recent product and capacity developments among leading global producers.
- Industry context mapping that connects raw material economics, pricing behaviors, regulatory developments, and sustainability advancements to practical procurement and production implications.
- Strategic recommendations designed to help manufacturers, converters, and end-market stakeholders align product development, sourcing, and market expansion with actual demand trajectories.
The analysis is built for practitioners. Every section is designed to answer the questions that matter most: where growth is materializing, how competitive pressures are shifting, what sustainability requirements will shape procurement criteria, and how volatility should be managed tactically. The full report delivers the depth required to turn these insights into action.
Why This Research Matters for 2026 Decision-Making
The year 2026 represents a pivotal planning horizon. Organizations finalizing product roadmaps, capacity investments, supplier contracts, and regional expansion strategies need intelligence that balances near-term operational realities with longer-term structural trends. This report is designed for that exact moment.
For producers and compounders, the analysis clarifies where grade differentiation and sustainability credentials will determine competitive outcomes. For converters and downstream manufacturers, it highlights application demand shifts, pricing risk factors, and supplier evaluation criteria that will shape sourcing decisions. For investors and corporate strategists, it provides the market architecture needed to assess entry opportunities, partnership potential, and consolidation dynamics with discipline.
The PA66 engineering plastics market will not be won by those who react to trends after they have matured. It will be shaped by organizations that anticipate demand shifts, align feedstock and product strategies with emerging requirements, and build supply chain resilience before volatility forces reactive adjustments. This research provides the strategic foundation to do exactly that.
Conclusion: Converting Insight into Advantage
The global PA66 engineering plastics market is moving through a period of structural transition. Growth remains anchored in enduring application demand, but the path forward is increasingly defined by sustainability performance, feedstock innovation, competitive consolidation, and tactical price management. Organizations that understand these forces in detail will be positioned to capture premium segments, secure resilient supply relationships, and align their portfolios with the next wave of engineering material requirements.
This report offers the comprehensive intelligence required to navigate that landscape with precision. To access the full dataset, segmentation analysis, competitive assessments, and strategic recommendations that support confident 2026 planning, explore the complete research publication. The depth of insight available there is built to turn market complexity into strategic clarity.
For detailed analysis of this topic, please visit the official page: PA66 Engineering Plastics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com