

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Ion Battery Binder Market Hits $5.63B in 2025, Projects 15.8% CAGR Through 2032

Strategic Navigation for the 2026 Lithium Ion Battery Binder Landscape
As the global energy transition accelerates, the supply chain supporting lithium ion batteries faces a critical inflection point. Binders, often underestimated as ancillary components, have become strategic determinants of electrode performance, manufacturing sustainability, and total cost of ownership. Our latest market research on Binders for Lithium Ion Batteries provides executive leaders with the architectural map needed to navigate a sector defined by rapid capacity expansion, shifting regulatory mandates, and intense raw material volatility. For stakeholders preparing capital allocation and sourcing decisions across 2026 and beyond, this intelligence bridges the gap between macro market momentum and the granular operational realities that ultimately drive competitive advantage.
Macro Trajectory and Market Architecture
The sector has demonstrated sustained structural growth driven by electric vehicle adoption, grid-scale energy storage deployments, and evolving consumer electronics requirements. Base year valuation for 2025 reached 5.63 billion USD, reflecting a compound trajectory from 2.7 billion USD in 2020. Our forecast model projects the market expanding to approximately 6.58 billion USD in 2026 and accelerating toward 15.72 billion USD by 2032, anchored by a robust 15.8 percent compound annual growth rate. This expansion is not merely a function of volume proliferation; it reflects a deeper transformation in product architecture as formulators balance electrochemical stability, mechanical integrity, and environmental compliance.
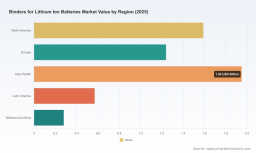
Market participants must recognize that growth is distributed unevenly across technology types and application domains. Cathode-dominant technologies continue to compete with emerging anode formulations, each demanding distinct rheological and adhesive characteristics. The segmentation analysis reveals a complex interplay where certain polymer families command premium positioning while aqueous systems gain regulatory tailwinds. To understand which product families will capture disproportionate value in specific geographies and end-use verticals, decision-makers require the comprehensive segmentation drill-downs contained in the full report. The detailed regional infrastructure maps and application-specific demand curves remain available exclusively through our complete dataset.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Competitive Dynamics and Strategic Positioning
The competitive environment reflects a mature industrial ecosystem with an evolving concentration profile. The top three players collectively account for approximately 29.4 percent of market revenue, while the top five extend to roughly 36.2 percent. This moderately fragmented landscape creates both partnership opportunities and competitive threats, particularly as specialized material science firms leverage proprietary formulations to secure long-term supply agreements with battery cell manufacturers and pack integrators.
Leading entity Zeon Corporation has carved a distinct niche as an exclusive manufacturer of water-based anode binders, emphasizing tensile strength and cycle performance specifically optimized for LFP cathode architectures. Kureha Corporation continues to reinforce its legacy in cathode binder production with KF Polymer PVDF grades engineered for adhesive strength and electrochemical stability dating back to early commercialization cycles. BASF SE has positioned itself as a scalable supplier of water-based anode binders, with its Licity platform providing SBR-based formulations compatible with graphite and silicon anode designs that demand enhanced capacity retention. Solvay S.A. maintains a broad PVDF portfolio spanning both anode and cathode applications, offering suspension and emulsion variants designed to extend cycle life and energy density. Arkema S.A. delivers Kynar-based PVDF solutions optimized for mechanical stability and electrolyte resistance across electrode architectures. Targray Technology International Inc. supplies battery-grade SBR and CMC grades alongside PAA formulations targeting high-silicon anode requirements for EV and energy storage deployments. Daikin Industries, Ltd. introduces functional enhancements into its NEOFLON VT PVDF portfolio, targeting flexibility, higher density, and gelation prevention. JSR Corporation focuses on advanced water-based systems for high-performance applications. Fujian Blue Ocean and Black Stone Technology specializes in sodium carboxymethyl cellulose binders for negative electrode applications. Mitsui Chemicals rounds out the competitive field with specialized binder formulations supporting automotive and industrial use cases.
Beyond static positioning, market intelligence must capture the tempo of operational expansion. March 2025 marked a significant capacity milestone as BASF SE expanded its US manufacturing footprint for Licity anode binders across Pennsylvania and Tennessee, directly supporting growing lithium ion battery demand through water-based SBR and CMC-compatible grades. In parallel, Zeon Corporation initiated preparations for a new lithium ion battery binder production line at its Texas facility in Pasadena, with operational readiness expected throughout 2026 to strengthen localized supply resilience. These infrastructure moves signal strategic intent to embed closer to demand centers, reduce logistics friction, and respond more nimbly to qualification cycles.
Operational Dynamics and Environmental Pressures
Raw material economics are dictating formulation strategy at an accelerating pace. PVDF binder raw material prices have exhibited notable volatility, with industry analysis pointing to fluctuations between 15 and 25 percent that directly influence binder production costs for lithium ion cathodes. Simultaneously, feedstock instability affecting cellulose and styrene derivatives has increased CMC and SBR material costs by 10 to 20 percent during 2025, compelling formulators to optimize co-binder ratios and reduce dependency on single-source inputs. This cost environment rewards procurement teams that anticipate price cycles and align supplier relationships with multi-year hedging strategies.
Binders for Lithium Ion Batteries Market
Regulatory and sustainability mandates are reshaping process architecture. Water-based binder processes are actively promoted under environmental initiatives designed to replace solvent-based systems, with potential to reduce NMP usage by up to 90 percent in electrode manufacturing. Policy tailwinds are reinforcing this transition; DOE-funded supply chain initiatives have supported domestic PVDF and SBR binder production expansions, including capacity additions approaching 35,000 tons in North America. These developments create both a compliance imperative and a competitive opportunity for organizations that can demonstrate sustainable manufacturing credentials while maintaining performance parity. Certification requirements are also tightening; new ISO standards for lithium ion binder formulations have become necessary for EV OEM qualification, with 2025 updates mandating enhanced electrolyte compatibility testing. Suppliers unable to demonstrate rigorous validation protocols risk exclusion from tier-one sourcing pipelines.
Content Architecture and Decision Utility
This market research is engineered for immediate operational deployment. The full document integrates historical performance mapping from 2020 through 2025 with an extended forecast window extending to 2032, enabling sensitivity analysis across multiple adoption scenarios. Our methodology combines top-down demand modeling with bottom-up supply verification to triangulate realistic growth pathways. Beyond aggregate sizing, the study delivers a segmented product family assessment that distinguishes performance profiles, cost drivers, and substitution risks across cathode-dominant and anode-facing binder families. Application-level analysis disaggregates demand patterns across electric vehicles, consumer electronics, energy storage systems, and industrial and marine devices, allowing sourcing leaders to align procurement strategies with the most rapid-growing verticals.
Regional coverage and competitive profiling provide the connective tissue between strategic intent and execution. The report reconstructs the manufacturing footprint and technology roadmaps of the key participants identified earlier, mapping capacity additions, geographic localization efforts, and formulation differentiation tactics. Interactive assumptions and scenario planning tools allow procurement, R&D, and strategy teams to stress-test sourcing configurations under varying raw material pricing conditions, regulatory timelines, and OEM qualification cycles. This level of actionable granularity ensures that market sizing is not treated as an abstract number but as a living input into capacity planning, supplier negotiation, and technology selection.
Strategic Imperatives for 2026 Decision-Makers
Organizational leaders entering 2026 should anchor their strategies around three pillars. First, secure formulation resilience by diversifying binder inputs and establishing co-binder optimization protocols that can absorb feedstock volatility without compromising electrochemical performance. Second, align manufacturing localization with qualification momentum; suppliers expanding capacity in proximity to demand centers will increasingly dictate lead times, sample availability, and technical support responsiveness. Third, invest in sustainable process readiness, because environmental mandates and ISO certification requirements are transitioning from optional differentiators to gatekeeping criteria for EV OEM partnerships. Organizations that anticipate these shifts will convert compliance into market access while positioning themselves to capture the disproportionate growth concentrated in high-volume application segments.
The complete valuation architecture, segmentation breaks, regional demand distribution, and supplier-by-supplier strategic assessment are detailed within the full Binders for Lithium Ion Batteries Market research. To obtain the quantitative segmentation splits, regional infrastructure mapping, and proprietary forecast models required for confident 2026 sourcing and investment decisions, access the complete intelligence package through our official research portal.
For detailed analysis of this topic, please visit the official page: Binders for Lithium Ion Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com