

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mercury Analyzer Market Hits $353.78M in 2025, Projects 6.58% CAGR to Reach $551.95M by 2032

Navigating the Mercury Analyzer Market: Strategic Intelligence for the 2026 Decision-Maker
The global mercury analyzer market stands at a critical inflection point. As environmental regulations tighten, industrial compliance becomes more complex, and analytical technologies evolve, organizations that fail to anticipate market shifts risk both regulatory exposure and missed commercial opportunities. Our latest research initiative delivers a comprehensive, data-driven view of the mercury analyzer landscape, designed specifically to equip executives, procurement leaders, and R&D strategists with the intelligence needed to navigate the 2026 planning cycle and beyond.
From a base year of 2025, the market has demonstrated consistent expansion, with total revenue climbing from approximately 258.75 million USD in 2020 to an estimated 353.78 million USD in 2025. The trajectory forward projects continued growth, with the market expected to reach 373.87 million USD in 2026 and scale to 551.95 million USD by the close of the forecast period in 2032. This represents a compound annual growth rate of 6.58 percent, a figure that underscores both the steady demand pull from regulated industries and the incremental innovation cycles reshaping instrument portfolios. For strategists, these aggregate numbers are more than historical record; they form the backbone of capacity planning, investment prioritization, and competitive positioning.
Why This Research Matters for 2026 Strategy
The 2026 operating environment introduces a complex mix of regulatory acceleration, regional divergence, and technological maturation. Organizations must decide where to invest in detection capabilities, which instrument architectures align with long-term compliance roadmaps, and how to anticipate competitor moves in a concentrated marketplace. Our report translates macro-level momentum into actionable intelligence, connecting market sizing with the operational realities that procurement teams, engineering directors, and sustainability officers face daily.
Rather than presenting a static snapshot, the study maps the interplay between regulatory catalysts, application-driven demand, and product-segment evolution. Decision-makers will find a structured framework for evaluating where growth concentrates, which end-use sectors are expanding fastest, and how regional enforcement patterns influence equipment refresh cycles. This is intelligence designed for real-world deployment: scenario planning, vendor selection, market entry assessment, and risk mitigation all benefit from the layered analysis contained in the full document.
What the Report Delivers
The study is constructed to serve as a practical reference for cross-functional strategy teams. It moves beyond headline figures to provide a granular exploration of the market architecture, enabling readers to align commercial objectives with technical and regulatory realities. Key components include:
- A detailed historical reconstruction covering 2020 through 2025, establishing trend baselines and growth inflection points that inform forward-looking assumptions.
- A multi-year forecast extending through 2032, structured to support budgeting cycles, capacity expansion decisions, and long-range technology roadmaps.
- An in-depth segmentation analysis that examines product architectures, application verticals, and regional demand patterns, helping leaders identify where opportunity density is highest without relying on superficial averages.
- A competitive landscape assessment that profiles leading manufacturers, maps their positioning, and evaluates recent commercial and strategic activities that signal shifts in market dynamics.
- A regulatory and standards review that contextualizes how evolving emission limits, elemental impurity guidelines, and international conventions shape procurement behavior and replacement cycles.
- Practical guidance for interpreting market concentration metrics, assessing barriers to entry, and anticipating consolidation or partnership activity among incumbent suppliers.
Each section is written with operational decision-making in mind. The intent is to equip teams with a shared language and evidence base so that product strategy, compliance planning, and commercial execution move in lockstep rather than in isolation.
Market Dynamics Shaping the Next Cycle
The mercury analyzer market does not expand in a vacuum. It responds directly to evolving policy frameworks, industrial compliance pressures, and the technical requirements of trace-level detection. Several dynamics are particularly consequential for 2026 planning:
Regulatory tightening remains a primary demand driver. Revised emission limit frameworks in Europe and sustained enforcement under national standards in China are accelerating the deployment of real-time mercury detection in waste incinerators and coal-fired facilities. These environments require instruments that can deliver continuous monitoring, withstand harsh process conditions, and integrate cleanly into existing compliance workflows. At the same time, global ratification and enforcement of the Minamata Convention continue to sustain instrument replacement cycles across regulated facilities in Europe, China, and Japan, reinforcing a recurring demand base that is less sensitive to short-term economic fluctuations.
Water Quality Analyzer Market
In the pharmaceutical and quality-control arena, elemental impurity guidelines such as ICH Q3D continue to anchor long-term demand from laboratories requiring trace mercury analysis. As quality standards become more rigorous and audit expectations rise, testing laboratories and production facilities are investing in instrumentation that offers robust sensitivity, reproducibility, and seamless integration into broader analytical platforms. This creates a stable, compliance-linked demand stream that complements the more cyclical industrial monitoring segment.
Not all regulatory signals point in the same direction, however. Recent changes to United States policy, including the 2026 repeal of strengthened mercury and air toxics standards, introduce a two-speed growth trajectory. While certain North American coal-utility upgrade projects face slowed momentum, other regions and application areas continue to expand, and the broader compliance infrastructure in many jurisdictions remains firmly in place. For strategists, this divergence highlights the importance of region-specific planning rather than blanket global assumptions. The ability to distinguish between accelerated, steady, and deferred demand pockets is essential for resource allocation and pipeline management.
Technology and Application Landscape
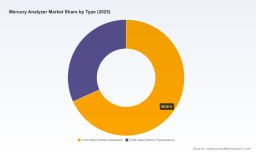
Mercury analyzers have diversified into multiple product architectures, each optimized for different detection environments, throughput requirements, and regulatory use cases. Cold vapor atomic absorption systems continue to account for the largest product segment share, a position driven by their high sensitivity, automation potential, and cost-effectiveness for routine laboratory and continuous emission monitoring applications. This architecture remains a workhorse for organizations that require reliable, high-volume testing with established method compliance.
Cold vapor atomic fluorescence systems represent a complementary segment, serving applications that demand distinct detection characteristics and specialized operational configurations. Together, these product families illustrate a market that is not defined by a single technological winner but by a portfolio of solutions tailored to specific compliance, throughput, and sensitivity requirements.
Application demand is similarly diversified. Environmental monitoring remains a central demand pillar, reflecting the ongoing need for emissions compliance, ambient sampling, and stack monitoring across industrial and municipal facilities. Food industry testing constitutes another significant demand avenue, where mercury screening supports safety assurance and regulatory adherence across supply chains. The oil, gas, and petrochemical sector contributes a distinct demand profile tied to process monitoring and compliance obligations, while healthcare applications and other specialized use cases round out the broader application landscape. Each vertical carries its own procurement rhythms, validation requirements, and technology preferences, which makes segmented analysis essential for targeted strategy development.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three competitors accounting for approximately 52.3 percent of revenue and the top five representing about 78.5 percent. This concentration level signals a landscape where incumbents hold meaningful share and where new entrants or expansion plays must navigate established relationships, method certifications, and service networks. At the same time, the presence of specialized manufacturers alongside broader analytical instrument providers creates a multidimensional competitive field in which differentiation can emerge from technology design, application focus, regional service capabilities, and regulatory method alignment.
Several leading companies define the current competitive architecture. Lumex Instruments, based in Mission, British Columbia, Canada, offers the RA-915M series Zeeman atomic absorption mercury analyzers alongside Light 915 portable models, supporting both laboratory-grade and field-deployable measurement needs. Mercury Instruments GmbH, headquartered in Karlsfeld, Germany, provides portable mercury analyzers, vapor monitors, and process instruments designed for environmental and industrial applications, with an emphasis on flexible deployment across compliance and operational settings. Teledyne Leeman Labs, located in Hudson, New Hampshire, USA, delivers Hydra II and QuickTrace mercury analyzers for laboratory and environmental elemental analysis, positioning its portfolio around robust sample handling and trace-level performance.
ENVEA GmbH, operating from France, contributes the SM-5 continuous mercury CEMS monitor and UT-3000 ultra-trace mercury analyzer, addressing industrial emissions compliance with a focus on continuous monitoring and ultra-trace detection. Nippon Instruments Corporation, based in Kyoto, Japan, supplies RA-7000A and MA-3000 direct mercury analyzers as well as PE/MA series systems that support regulatory compliance applications, combining direct analysis approaches with method-aligned configurations. Thermo Fisher Scientific Inc., headquartered in Waltham, Massachusetts, USA, offers the Mercury Freedom System for stack emissions monitoring in coal-fired and waste incinerator applications, integrating mercury measurement into broader emissions management workflows. PerkinElmer Inc., also based in Waltham, Massachusetts, USA, provides mercury analysis systems integrated into atomic spectroscopy and environmental testing platforms, appealing to laboratories that seek consolidated analytical ecosystems. Brooks Rand Instruments, located in Seattle, Washington, USA, delivers advanced mercury analyzers and speciation systems certified to US EPA methods, serving customers who require method-aligned speciation and compliance-ready performance.
Recent commercial activity reinforces the dynamic nature of this landscape. Lumex Instruments is scheduled to exhibit at analytica 2026 in Munich, signaling continued engagement with European analytical markets and application communities. The company also conducted a RA-915 series technical training course in Chile in November 2025, underscoring the importance of application support and user capability building in emerging deployment contexts. Nippon Instruments Corporation secured a US Geological Survey contract in September 2025 for delivery of an MA-1001 Model MA-2000 mercury analyzer, illustrating how public-sector and scientific procurement continues to validate technology choices and create reference points for broader adoption.
Regional Considerations and Deployment Logic
Demand patterns vary meaningfully across regions, reflecting differences in regulatory enforcement, industrial structure, laboratory capacity, and equipment refresh cycles. North America represents a substantial demand base, shaped by a mix of environmental monitoring requirements, laboratory testing activity, and industrial compliance applications. Europe contributes a strong and regulation-linked demand profile, supported by sustained enforcement frameworks and continuous monitoring requirements in key industrial sectors. Asia Pacific reflects a large and growing opportunity set, driven by expanding industrial activity, tightening local standards, and increasing adoption of analytical infrastructure across both environmental and industrial use cases. Latin America and the Middle East and Africa represent smaller but strategically relevant demand pockets, where targeted deployment, application support, and compliance-driven upgrades can create meaningful Positioning opportunities for suppliers with the right service and technical engagement models.
For market participants, regional nuance matters. The same instrument architecture may face very different adoption criteria depending on local method expectations, service availability, and the balance between portable, field-deployable solutions and fixed laboratory or continuous monitoring systems. A clear regional view helps leaders prioritize go-to-market effort, tailor application messaging, and anticipate where replacement cycles or new installation activity is likely to intensify.
Mercury Analyzer Market
Implications for Executive Decision-Making
The strategic value of this research lies in its ability to convert market structure into decision-ready insight. Executives can use the analysis to stress-test assumptions about demand durability, evaluate whether current product or service portfolios align with the fastest-moving application and regulatory drivers, and identify where competitor activity suggests shifting share dynamics. Procurement and operations leaders can use the segmentation and dynamic analysis to benchmark procurement timing, align instrument selection with compliance roadmaps, and reduce exposure to policy-driven demand volatility. R&D and product teams can use the technology and application mapping to prioritize development efforts that match real-world detection requirements rather than abstract market averages.
The concentration profile also carries practical implications. With a significant share held by a limited set of competitors, market entry or share-gain strategies must account for established method certifications, service networks, and customer relationships. Differentiation may come from application-specific performance, regional support strength, portability and deployment flexibility, or integration with broader analytical and emissions management ecosystems. Understanding where incumbents are actively engaging customers through exhibitions, training, and public-sector contracts provides early signals about where attention and capability investment are flowing.
Accessing the Full Intelligence
This overview is intended to demonstrate the depth and operational relevance of the full study while reserving the most detailed segmentation, regional breakdowns, and company-specific intelligence for the complete report. The aggregate market trajectory, the 6.58 percent compound annual growth rate, and the broad structural themes described here provide a credible foundation for strategic discussion. However, the precise regional splits, application-level demand distributions, product-segment magnitudes, and competitive micro-positioning that underpin execution-level decisions are developed in detail within the full document.
Leaders who require precise figures for budgeting, market-entry modeling, vendor negotiation, or investment justification will find the complete report structured to support those use cases directly. The study connects historical reconstruction, forward forecast, segmentation architecture, regulatory context, and competitive activity into a single coherent framework, enabling cross-functional teams to act on the same evidence base.
For organizations preparing for the 2026 planning cycle, the mercury analyzer market offers both compliance-driven certainty and strategic complexity. The companies that navigate it effectively will be those that pair regulatory awareness with technology judgment, regional sensitivity, and a clear view of where demand is genuinely expanding versus where it is merely shifting. Our research is designed to provide that view, giving decision-makers the clarity required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Mercury Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com