

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shipping Software Market Hits $2.19B in 2025, 8.5% CAGR to 2032

The 2026 Shipping Software Market: Strategic Intelligence for the Next Wave of Logistics Decision-Makers
The global shipping software market enters 2026 at a decisive inflection point. What was once a back-office functional purchase has evolved into a board-level strategic asset, directly influencing fulfillment speed, carrier cost optimization, customer retention, and supply chain resilience. Our newly released Shipping Software Market research delivers the empirical foundation and competitive intelligence that enterprise leaders, logistics operators, and technology procurement teams require to navigate the remainder of this decade. This introduction outlines the research framework, the strategic questions the study answers, and why institutional decision-makers should anchor their 2026 planning cycles to its findings before committing to vendor selection, architectural transitions, or capital allocation.
Why 2026 Is a Defining Year for Shipping Software Strategy
The historical trajectory of the shipping software sector tells a clear story of sustained, compounding growth. Between 2020 and 2025, the market expanded from approximately 1,500 million USD to 2,190 million USD, reflecting a compound annual growth rate (CAGR) of 8.5% across the forecast window through 2032. By 2032, the addressable market is projected to approach nearly 3,900 million USD. These headline figures are not abstract statistics; they signal a structural transformation in how shippers, forwarders, marketplaces, and postal operators orchestrate parcel movement, rate negotiation, label automation, and post-purchase experience.
Two forces converge in 2026 to make this growth particularly consequential. First, the operational complexity of multi-carrier fulfillment has outpaced the capabilities of legacy on-premises tooling, pushing a rapid architectural shift toward platform-native, API-driven ecosystems. Second, cost pressure across labor, infrastructure, and transactional processing means that software purchasing decisions are now scrutinized through the lens of unit economics and downtime exposure rather than feature checklists alone. Shipping software is no longer an isolated departmental purchase; it is the connective tissue between order management, warehouse execution, transportation negotiation, and customer communication.
Our research frames this transition in terms that matter to executives. The study dismantles the illusion of a monolithic market and instead maps the economic gravity of each deployment model, each application vertical, and each geographic cluster. It examines how the concentration of revenue among leading participants shapes pricing power, integration roadmaps, and the pace of innovation. For any organization evaluating a shipping software investment, the strategic question is no longer whether to modernize, but which modernization path preserves optionality, minimizes integration risk, and aligns with the realities of 2026 carrier networks and customer expectations.
Shipping Software Market
What the Research Delivers: Architecture, Execution, and the Full Operating Picture
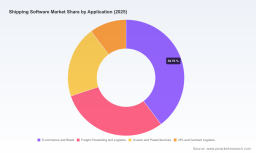
This market study is built for action, not passive reading. The report structure is designed to convert macroeconomic indicators into procurement-grade clarity. Readers will encounter a granular breakdown of the market by deployment model, application category, and regional footprint, each mapped to the operational realities that actually drive purchasing behavior. The analysis spans the core segments that dominate enterprise and mid-market demand: cloud-based and on-premises architectures; e-commerce and retail operations; freight forwarding and logistics; courier and postal services; and third-party logistics and contract logistics arrangements.
Beyond segmentation, the report provides a practical taxonomy of the technology landscape. It distinguishes pure-play shipping platforms, carrier-agnostic API integrations, enterprise multi-carrier management suites, ERP-anchored extensions, and specialized post-purchase experience tools. Each category is evaluated through a consistent lens of integration depth, scalability, automation maturity, and the operational use cases where each archetype delivers the strongest return. The study also explores how shipping software now intersects with adjacent systems such as warehouse management, order management, marketplace fulfillment, and returns orchestration, revealing where integration efficiency becomes a direct lever on total cost of ownership.
The report further extends into a competitive profile of the organizations shaping the market. It profiles established enterprise incumbents, fast-scaling technology specialists, and infrastructure-heavy global players. The objective is not to rank vendors for the reader, but to help procurement and IT leadership understand where each participant competes, how their solution philosophies differ, and what kind of organizational fit each represents. This is essential because shipping software selection is increasingly a multi-year relationship decision that influences carrier negotiation leverage, exception handling, and the ability to absorb volume spikes without operational degradation.
Competitive Dynamics: How the Field Is Shaping Strategy in 2026
The shipping software market is characterized by a layered competitive structure. A recognizable group of leaders captures meaningful share, while a broader field of specialists competes on integration breadth, developer experience, marketplace compatibility, and vertical-specific workflows. Our research dissects this structure through company profiles that span the full spectrum of solution philosophies. You will find analysis of multi-carrier rate comparison and label automation platforms designed for high-volume parcel operations, scalable e-commerce shipping environments with built-in inventory and fulfillment tooling, multi-channel shipping automation and post-purchase experience providers, and cloud-based shipping APIs that abstract carrier complexity for developers and platform operators.
The landscape also includes enterprise-oriented multi-carrier shipping suites with broker rating, peak-season capacity management, and deep carrier integrations, alongside versionless parcel fulfillment platforms that extend into less-than-truckload capabilities and ERP or warehouse management system connectivity. Larger ecosystem players are represented through supply chain and transportation management software with shipping execution modules, ERP-integrated shipping extensions delivered through partners, and cloud SCM integrations that connect shipping logic directly into enterprise financial and planning systems. The field further encompasses global shipment management software that unifies access to hundreds of carriers with brand-compliant delivery experiences, and logistics platforms tightly integrated with ERP for multi-carrier operations at scale.
Recent market moves underscore how competitive intensity is being translated into product evolution. Throughout 2025 and early 2026, leaders and challengers alike have reinforced their positions through executive appointments, recognition milestones, versioned software updates, and partnership integrations that widen the addressable enterprise footprint. The research synthesizes these developments into a coherent narrative: the market is consolidating capability rather than fragmenting into irrelevance. Carrier aggregation, automation rules, broker rating logic, and ERP-adjacent connectivity are becoming table stakes, and the differentiation frontier is shifting toward reliability under peak load, configuration agility, and the quality of post-purchase customer journeys.
The study also incorporates the cost and regulatory realities that now influence buying behavior. Infrastructure and cloud hosting expenses, API processing fees at scale, labor constraints in implementation and support, incident response costs during outages, and the imminent effect of EU Data Act requirements on cloud transfer pricing all affect how shipping software is evaluated on a total-cost and risk-adjusted basis. Rather than treating these as peripheral concerns, the report embeds them into the decision framework, showing how they reshape the economics of self-managed versus managed platform choices, the value of prebuilt carrier integrations, and the hidden costs of fragmented toolchains.
Strategic Questions the Report Helps You Answer
For organizations preparing 2026 budgets and multi-year technology roadmaps, the research is structured to support a specific set of strategic conversations. These include:
- How should procurement teams compare cloud-based and on-premises shipping software when total cost, integration load, and operational agility are weighted together?
- Which deployment model best aligns with an organization's volume profile, carrier mix, and internal integration capacity over the forecast horizon through 2032?
- How do the core application verticals differ in their purchasing logic, and what does that mean for positioning a solution to e-commerce, freight forwarding, postal operations, or third-party logistics scenarios?
- What competitive concentration levels imply for pricing negotiation, roadmap influence, and vendor lock-in risk over the next planning cycle?
- Where does shipping software need to connect with ERP, warehouse management, order management, marketplace fulfillment, and returns workflows to avoid duplicative spend and operational gaps?
- How should the market's recent product updates, partnership announcements, and leadership shifts be interpreted when evaluating vendor durability and execution capability?
Each of these questions is answered with evidence, not conjecture. The report connects market sizing to operational reality, and it treats the 2026 to 2032 period as a sequence of decision windows rather than a single moment. Buyers who understand the structural growth path, the competitive architecture, and the cost environment will be better positioned to negotiate integration commitments, evaluate migration timelines, and select partners that can scale with peak-season volatility.
Data You Will Not Find Here, and the Intelligence You Can Access
To serve institutional buyers, this introduction deliberately omits the detailed size breakdowns that define the value of the full study. The complete report contains segment-specific market values for each region, deployment model, and application category, along with the analytical commentary that explains how those figures translate into procurement implications. It also provides company-by-company profiling, recent development tracking, and the concentration metrics that reveal how revenue is distributed across leaders and challengers.
Real Estate Software Market
That deliberate restraint is intentional. The macro trajectory, growth rate, and structural composition of the market point in a clear direction, but the operational decisions your team faces require the granular supporting data, the vendor context, and the segmentation logic that only the full research package provides. Readers who rely on headline growth alone risk misjudging where the money is flowing, which deployment model is absorbing disproportionate share, and where the competitive advantage gaps are opening.
How to Use This Research in Your 2026 Planning Cycle
The highest-value use of this study is as a decision filter, not a one-time read. Procurement leaders can align internal scorecards to the segmentation logic before vendor demonstrations begin. IT and integration teams can use the deployment and application analysis to anticipate architecture dependencies and avoid under-scoping the effort required to connect shipping software with adjacent systems. Executive sponsors can use the market trajectory and concentration data to frame investment timing, budget sequencing, and the risk of delaying modernization while competitors move onto more capable platforms.
The report is equally useful for organizations evaluating build-versus-buy choices, multi-vendor consolidation, or staged migration from legacy tooling. By mapping the market to the practical realities of carrier integration, automation maturity, exception management, and post-purchase experience, the study helps teams separate marketing claims from operationally meaningful differentiation. In a market expanding at a steady mid-single-digit compound rate and projected to reach a substantially higher revenue base by 2032, the purchasing decisions made in 2026 will shape cost structure and service quality for years.
Closing Perspective
The shipping software market is large, structured, and accelerating in its strategic importance. The historical growth from 2020 through 2025, the 8.5% compound annual growth rate across the forecast period, and the projected market scale toward the end of the decade all point to an industry where software capability is becoming inseparable from fulfillment performance and customer experience. Yet the decisions that matter most in 2026 are not derived from top-line growth alone. They depend on which deployment model fits your operating model, which application vertical shapes your demand profile, which competitive dynamics affect your negotiating position, and how cost, regulation, and integration complexity alter the economics of each option.
Our Shipping Software Market research is designed to give enterprise leaders, logistics operators, and technology buyers the evidence base required to move beyond intuition and into disciplined, defensible decision-making. The full report contains the segment-level market values, the detailed regional and application breakdowns, the company profiles, and the recent development chronology that turn these macro signals into actionable intelligence. For teams preparing budgets, vendor evaluations, and multi-year transition plans, the complete study is the reference point that makes those choices sharper, faster, and more resilient.
For detailed analysis of this topic, please visit the official page: Shipping Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com