

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SSD Market to Hit $76.27 Billion by 2032, 19.9% CAGR

The SSD Market in 2026: Navigating a Compound Growth Curve Amid Capacity Constraints
The global landscape for Solid State Drives is undergoing a structural transformation. What began as a gradual migration from mechanical storage has accelerated into a defining infrastructure shift for enterprises, hyperscalers, and consumer platforms alike. At PW Consulting, we have synthesized multi-year historical data with forward-looking modeling to map this trajectory through the end of the decade. Our latest SSD Market research is designed not merely as a reference document, but as a decision-support instrument for leadership teams operating in an environment where storage architecture choices now directly influence cloud economics, AI workloads, and supply chain resilience.
The market's momentum is unmistakable. From a baseline of 10.0 billion USD in 2020, the sector reached 21.41 billion USD by 2025, reflecting sustained adoption across both enterprise and consumer segments. Forecasts extending through 2032 project the market to expand to 76.27 billion USD, implying a compound annual growth rate of 19.9 percent. This trajectory is not a purely organic extension of past trends. It is shaped by generational technology transitions, intensifying demand from data-intensive applications, and a supply environment that has become increasingly constrained and strategically contested. For executives planning capital allocation, procurement strategy, or product roadmaps in 2026, understanding the mechanics behind these figures is no longer optional.
Strategic Value of the 2026 Decision-Making Window
The period spanning 2026 through 2032 represents a decisive window for storage procurement and infrastructure planning. Organizations that approach SSD acquisition as a commodity transaction risk exposure to pricing volatility, supply delays, and architectural misalignment. Conversely, those that integrate market intelligence into sourcing, capacity planning, and technology selection can convert storage decisions into competitive leverage. Our research framework is built around this reality. It translates macro-level expansion into actionable guidance for procurement teams, IT architects, product managers, and strategic planners who must navigate a market where demand signals and supply constraints are moving at different speeds.
Several structural forces make the 2026 context particularly consequential. The proliferation of generative AI pipelines, the scaling of hyperscale and enterprise data centers, and the ongoing migration toward high-performance interfaces have collectively elevated SSDs from peripheral components to core infrastructure assets. At the same time, the raw material environment is introducing new complexities. Demand for NAND flash capacity has tightened to a degree that reshapes negotiation leverage, contract structures, and lead-time expectations. These dynamics mean that the strategic question is no longer simply which drive to buy, but how to structure partnerships, inventory posture, and technology roadmaps in a market where high-density NAND is increasingly difficult to secure.
Inside the Report: Operational Intelligence for Real-World Decision Making
Our SSD Market research is structured to provide layered insight without sacrificing practical usability. Rather than presenting a single narrative, the report is organized around the decision points that matter to different functional teams. The analysis begins with a comprehensive market sizing and forecast model, anchored in historical data from 2020 through 2025 and projected across the 2026 to 2032 horizon. This foundation supports scenario analysis for revenue planning, capacity requirements, and segment-level opportunity assessment.
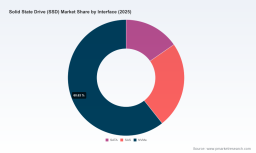
Beyond aggregate sizing, the report delivers a detailed segmentation lens across interface architectures, capacity tiers, and regional demand patterns. This breakdown allows readers to identify where growth is concentrated, which form factors and protocol ecosystems are gaining traction, and how application requirements are reshaping procurement preferences. Instead of treating the market as a monolith, the analysis isolates the drivers that distinguish high-performance enterprise deployments from cost-optimized bulk storage and consumer-grade product lines.
The operational heart of the report lies in its competitive and supply chain evaluation. We examine the strategic positioning of leading manufacturers, the role of controller and component suppliers in shaping architectural differentiation, and the contractual and sourcing developments that are redefining supply security. Recent industry moves, including multi-year supply agreements, extended controller partnerships, and the sampling of record-capacity drives, are analyzed not as isolated news items but as indicators of a market where relationships and forward commitments increasingly determine access.
The report also incorporates a dedicated assessment of market dynamics, with particular attention to NAND availability, pricing pressures, and the operational consequences of capacity tightness. By integrating supply-side signals with demand forecasts, the analysis provides a grounded view of what organizations should anticipate in terms of lead times, negotiation posture, and risk mitigation. The goal is to help readers move from awareness of volatility to concrete planning assumptions.
Worldwide SSD Memory Card Market
Competitive Landscape: Architectures of Leadership and Differentiation
The SSD market is defined by a concentrated competitive field in which a small group of manufacturers commands a substantial share of revenue, while a broader ecosystem of component suppliers, brand specialists, and enterprise-focused vendors contributes to product diversification and technology diffusion. Concentration at the top of the market underscores the strategic importance of scale, manufacturing capability, and direct relationships with large data center and enterprise customers. At the same time, technology differentiation remains a powerful competitive lever, particularly as interface performance, NAND architecture, and capacity ceilings continue to advance.
Among the leaders shaping enterprise and high-capacity segments, Samsung Electronics continues to emphasize performance leadership in data center and enterprise SSDs, including drives engineered for throughput-intensive workloads. SK hynix has reinforced its enterprise positioning through high-performance SSDs supported by advanced NAND architectures, reflecting the broader industry push toward capacity and efficiency gains. Micron Technology has expanded its high-capacity PCIe Gen5 portfolio, with drive variants targeting both standard and extremely high-capacity enterprise applications. Kioxia Corporation has advanced the envelope on maximum-capacity NVMe solutions, introducing industry-first drive configurations designed for generative AI and large-scale storage environments. Western Digital Corporation, together with its SanDisk-branded portfolio, maintains a broad enterprise and high-performance footprint spanning multiple use cases and performance tiers. Seagate Technology remains focused on enterprise NVMe offerings oriented toward data center and hyperscale deployments.
Solid State Drive (SSD) Market
A second tier of influential players illustrates how specialization and targeted architecture can shape competitive outcomes. Solidigm has carved out a strong position in high-capacity QLC PCIe SSDs designed for AI and data center workloads, signaling the growing relevance of density-optimized designs in large-scale environments. In the consumer and prosumer space, Corsair and Kingston Technology continue to compete on speed, reliability, and platform integration, while Crucial, as part of the Micron ecosystem, provides value-oriented NVMe and SATA options that extend advanced interface capabilities into broader buyer segments. ATP Electronics contributes compact NVMe PCIe Gen4 solutions with integrated supply chain control, and Apacer Technology addresses industrial and embedded applications that require durability and deterministic performance. ADATA Technology serves gaming and portable storage segments with USB and NVMe form factors, reflecting the continued importance of form-factor flexibility in consumer-adjacent markets.
The competitive picture is incomplete without acknowledging the enabling layer of controller and reference-design suppliers. Phison Electronics plays a critical role in this ecosystem, providing enterprise SSD controllers and reference designs that influence performance, efficiency, and time-to-market for drive manufacturers. This vertical structure matters because differentiation in SSDs increasingly depends on the integration of controllers, NAND architectures, firmware strategies, and thermal management, not on storage media alone.
Recent developments reinforce how competitive strategy is being redefined by supply commitments and product introductions. Kioxia's sampling of an industry-first 245.76 TB NVMe SSD in 2.5-inch and E3.L form factors for generative AI workloads highlights the race toward extreme capacities for AI-driven storage demands. Western Digital and SanDisk's multi-year supply agreements, extending up to five years for SSDs and HDDs, illustrate a shift toward long-horizon contracting aimed at securing capacity for AI and data center requirements. Solidigm's extension of a multi-year agreement with Broadcom for high-capacity SSD controllers further demonstrates how controller partnerships are becoming strategic assets for AI and data-intensive workloads. Micron's entry into customer sampling for its 6550 ION PCIe Gen5 NVMe SSD in E3.S form factor underscores the continued push toward higher capacities and next-generation interfaces in enterprise environments.
Market Dynamics: Supply, Regulation, and the Pricing Environment
The forward outlook for the SSD market cannot be understood without addressing the supply-side pressures that have emerged across the NAND ecosystem. Recent industry reporting indicates that the majority of 2026 NAND flash capacity is already committed, with high-density NAND effectively sold out in several channels and major cloud providers locking capacity for AI initiatives. Inventory levels at multiple module manufacturers are expected to be sufficient only through the first quarter of 2026, with stockouts projected to begin in March and shortages becoming more widespread after the second quarter. This environment has prompted some NAND foundries to require three-year cash prepayments from select customers, an arrangement that signals both the severity of demand pressure and the recalibration of supplier leverage.
Compounding these supply constraints, persistent NAND shortages are anticipated to extend through the third quarter of 2026. This is not merely a temporary bottleneck; it has structural implications for procurement planning, product availability, and cost forecasting. Organizations that rely on spot procurement or short-term contracting may face greater exposure to availability gaps and price volatility, while those that secure forward commitments and maintain diversified sourcing strategies may be better positioned to manage continuity. The strategic implication is clear: in a market where high-density NAND is constrained, supply assurance becomes a core component of competitive planning.
Regulatory developments add another layer of complexity. Ongoing U.S. export controls on advanced semiconductor manufacturing equipment and related items, including components used in NAND production, continue to affect access for certain entities and shape the geography of advanced manufacturing capacity. While the direct effects vary by organization and supply chain configuration, the broader consequence is an environment in which technology access, production location, and supply continuity must be evaluated together. For global enterprises, this reinforces the importance of mapping not only component availability but also the regulatory exposure embedded in the manufacturing base.
What Sets This Research Apart
Our SSD Market research is designed to connect high-level market trajectory with the operational questions that determine outcomes in 2026 and beyond. It combines a rigorous quantitative foundation with a qualitative assessment of competitive strategy, supply dynamics, and technology direction. The report is intended to help executives answer questions that generic market summaries cannot address: where growth is most durable, how interface and capacity shifts are changing procurement priorities, what the concentration of leading manufacturers means for negotiation and continuity, and how supply constraints and regulatory developments should be incorporated into sourcing assumptions.
The analysis is built for use across multiple planning functions. Procurement and supply chain teams can use the segmentation and dynamics sections to inform contracting strategy and inventory posture. Product and technology leaders can use the interface and capacity analysis to align roadmaps with demand trends. Competitive strategy teams can use the manufacturer and controller ecosystem assessment to understand where differentiation is being created and where scale advantages are most consequential. Because the research deliberately integrates market sizing with the forces that shape access to capacity, it serves as a practical bridge between strategic forecasting and day-to-day decision making.
Conclusion: Positioning for the Next Phase of SSD Growth
The SSD market is expanding at a pace that places storage at the center of infrastructure planning for the remainder of the decade. A compound annual growth rate of 19.9 percent and a projected 2032 market size of 76.27 billion USD indicate that the sector will continue to attract significant investment, innovation, and competitive intensity. Yet the strategic challenge is not simply to track growth, but to interpret it within a supply environment where high-density NAND is constrained, long-term agreements are becoming more common, and advanced manufacturing capacity is shaped by both technology and regulatory forces.
For organizations preparing for 2026, the most valuable intelligence is the kind that connects numbers with operational consequences. Our SSD Market research is built for that purpose. It provides the segmentation detail, competitive context, and supply-side assessment needed to move from broad market awareness to informed planning. Readers seeking the full segmentation breakdown, the complete manufacturer and controller ecosystem analysis, and the detailed dynamics assessment can access the full report through our website, where the complete intelligence package is available for teams that require a comprehensive basis for strategic decision making.
For detailed analysis of this topic, please visit the official page: Solid State Drive (SSD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com