

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial X-Ray Inspection Market to Hit $2.51B by 2032 With 8% CAGR

Industrial X-Ray Inspection Systems Market: Strategic Imperatives for 2026 and Beyond
Executive Summary: Navigating a High-Growth Non-Destructive Testing Landscape
The industrial X-ray inspection sector has transitioned from a niche quality assurance tool to a foundational pillar of modern manufacturing, aerospace validation, and advanced electronics production. As enterprises recalibrate capital allocation strategies for the 2026–2032 horizon, understanding the velocity, structural drivers, and competitive friction points within this market is no longer optional—it is a prerequisite for resilient operational planning. This comprehensive market research report delivers a rigorously modeled forecast, segmentation architecture, and competitive intelligence framework designed to equip engineering leaders, procurement directors, and corporate strategists with the clarity required to navigate an increasingly complex inspection ecosystem.
Drawing on a multi-year historical dataset spanning 2020 through 2025 and extending forecast projections through 2032, the analysis captures a sector experiencing sustained expansion. Revenue trajectories demonstrate consistent growth from a baseline market valuation that has compounded annually, reflecting heightened demand for non-destructive testing (NDT) capabilities across critical infrastructure, precision manufacturing, and regulated supply chains. The underlying growth narrative is not merely a function of volume; it is fundamentally tied to technological maturation, regulatory tightening, and the industrial shift toward automated, high-resolution inspection workflows that reduce human error while accelerating throughput.
For decision-makers evaluating 2026 capital expenditure plans, vendor partnerships, or regional deployment strategies, this report functions as a strategic compass. It contextualizes macro growth signals within actionable operational insights, enabling organizations to align inspection investments with production scalability, compliance mandates, and long-term product integrity goals. What follows is a structured examination of the forces shaping the market, the competitive architectures defining vendor positioning, and the practical research deliverables that translate raw data into executable strategy.
Macro Market Trajectory and Structural Growth Drivers
The historical evolution of the industrial X-ray inspection market from 2020 to 2025 reveals a sector that has consistently outpaced baseline industrial equipment growth rates. Revenue progression over this period demonstrates a clear upward inflection, driven by the dual pressures of manufacturing miniaturization and the escalating cost of undetected defects. As component geometries shrink and material tolerances tighten—particularly in semiconductor packaging, aerospace composite assemblies, and high-density battery structures—the limitations of conventional visual and tactile inspection methods have become operationally untenable. X-ray and computed tomography (CT) systems have consequently emerged as indispensable verification layers, bridging the gap between design intent and manufacturing reality.
The forward-looking forecast architecture projects continued expansion through 2032, with a compound annual growth rate (CAGR) that underscores the sector's structural resilience. This growth trajectory is not uniformly distributed across time; rather, it reflects phased adoption curves tied to capital replacement cycles, regulatory enforcement timelines, and the gradual integration of advanced detector technologies into mainstream production environments. Early-phase growth is heavily influenced by the modernization of legacy radiography infrastructure, while mid-to-late forecast periods accelerate as photon-counting architectures, direct conversion detectors, and automated robotic inspection platforms achieve broader commercial viability.
Strategically, this trajectory carries several implications for enterprise planning. First, the persistence of double-digit total market expansion suggests that inspection capability must be treated as a core operational competency rather than a discretionary quality checkpoint. Second, the transition toward higher-resolution, lower-latency imaging systems indicates that procurement decisions made today will likely dictate inspection throughput and defect-detection sensitivity for the next decade. Third, the forecasted revenue scale by 2032 reflects an industry that is consolidating around standardized software ecosystems, modular hardware architectures, and data-integrated quality management pipelines. Organizations that align their inspection roadmaps with these structural shifts will be best positioned to capture efficiency gains, reduce warranty exposure, and maintain compliance in highly regulated verticals.
Competitive Architecture and Executive Benchmarking
The industrial X-ray inspection landscape is characterized by a concentrated vendor ecosystem in which a limited number of established players command a substantial share of global revenue, while a secondary tier of specialized manufacturers competes through regional strength, application-specific customization, and emerging-market distribution advantages. Market concentration metrics indicate that a core group of global providers collectively accounts for an outsized proportion of total industry receipts, reinforcing the strategic importance of vendor selection, service agreement structuring, and lifecycle cost modeling. For enterprises evaluating inspection partnerships, the competitive architecture is not merely a price-comparison exercise; it is a capability-matching process that should weigh detector performance, system integration flexibility, regional service coverage, and software interoperability.
Industrial X-ray Inspection Systems Market
Leading global equipment manufacturers anchor the market's premium segment, offering high-end X-ray and CT system solutions engineered for demanding non-destructive testing applications across aerospace, automotive, electronics, and semiconductor environments. These providers have invested heavily in metrology-grade data output, robotic integration pathways, and modular detector configurations that support both inline production and offline failure analysis. Recent product developments from this cohort illustrate the pace of innovation: major metrology and imaging divisions have introduced compact-footprint X-ray and CT platforms with expanded inspection envelopes and enhanced data fidelity, specifically targeting electronics, additive manufacturing, and medical device validation workflows. Concurrently, detector specialists have rolled out mid-sized and large-format digital radiography panels optimized for isotope-based inspection, incorporating advanced scintillator materials to improve high-energy sensitivity and active-area coverage.
X-ray Inspection Systems Market
Complementing these global incumbents is a diversified set of regional and application-focused manufacturers that emphasize customization, rapid deployment, and cost-optimized system configurations. European and North American engineering firms continue to specialize in tailored inspection systems and software-driven NDT solutions for automotive, aerospace, and industrial quality assurance environments. Asian-based manufacturers have expanded their export footprint by providing industrial X-ray systems, high-voltage generators, and integrated inspection equipment targeted at quality control operations across emerging manufacturing hubs. Meanwhile, specialized engineering companies in Southern Europe and the United Kingdom contribute niche high-energy CT capabilities for large-scale aerospace castings and broad-spectrum manufacturing integrity verification.
For strategic buyers, this competitive landscape presents both opportunity and complexity. The presence of dominant global players ensures access to mature platforms, established service networks, and continuous R&D investment. Simultaneously, the availability of specialized and regionally embedded vendors enables organizations to tailor inspection architectures to specific throughput requirements, facility constraints, and compliance profiles. The report's competitive intelligence module maps these dynamics in detail, offering executive benchmarking frameworks that compare product portfolios, strategic positioning, and recent development activity across the core vendor set. This allows organizations to move beyond surface-level vendor characterization and instead evaluate which ecosystem aligns most closely with their inspection maturity curve, capital deployment timeline, and operational risk tolerance.
Regulatory Catalysts and Technological Transition Vectors
Regulatory frameworks and material-science advancements are two of the most potent accelerants shaping adoption patterns within the industrial X-ray inspection sector. On the compliance side, mandated inspection rigor across highly regulated industries is converting X-ray and CT systems from optional quality enhancements into operational necessities. In the food and beverage sector, stringent contaminant detection protocols enforced by agencies such as the U.S. Food and Drug Administration require manufacturers to identify foreign objects—including metallic fragments, glass shards, and dense packaging anomalies—with repeatable precision. X-ray inspection platforms have become the preferred verification mechanism in this environment, offering automated rejection integration, high-speed line throughput, and documentation trails that support audit readiness.
In aerospace and aviation, regulatory authorities on both sides of the Atlantic enforce rigorous reliability standards for critical components such as turbine blades, structural composite assemblies, and high-stress mechanical interfaces. The Federal Aviation Administration and the European Union Aviation Safety Agency maintain stringent certification and inspection expectations that directly elevate demand for high-fidelity NDT solutions capable of revealing internal porosity, delamination, and micro-fractures without compromising component integrity. These mandates extend beyond final assembly lines; they permeate supplier qualification processes, material receiving inspections, and in-service maintenance protocols, creating persistent demand for inspection systems that can deliver consistent, traceable, and defensible results across complex multi-tier supply chains.
Parallel to regulatory pressure, detector technology transitions are fundamentally reshaping the performance envelope of industrial X-ray systems. Industry data points to a measurable shift from conventional amorphous silicon flat-panel detectors toward amorphous selenium direct conversion architectures and photon-counting CT detectors. These technological migrations are not incremental; they alter the physics of signal capture, noise suppression, and spatial resolution in ways that directly affect defect detectability and inspection speed. Direct conversion detectors reduce scatter and improve contrast fidelity, while photon-counting architectures enable spectral discrimination that can differentiate material compositions with greater precision. For manufacturing organizations, this transition introduces a strategic planning variable: systems deployed today based on legacy detector generations may face obsolescence risk as higher-sensitivity, data-rich imaging platforms become cost-accessible and software-compatible with existing quality management environments.
The convergence of regulatory enforcement and detector evolution creates a compounding effect. Compliance requirements raise the baseline performance threshold that inspection systems must meet, while next-generation detectors expand the ceiling of what is technically achievable. Strategic procurement and facility planning must therefore account for both the immediate compliance floor and the forward-looking capability ceiling. Organizations that evaluate inspection investments solely against current operational needs risk underinvesting in systems that will struggle to meet emerging audit standards or integration expectations within a three-to-five-year window. Conversely, enterprises that understand the technology migration curve can time their hardware refreshes, detector upgrades, and software rollouts to maximize return on inspection infrastructure across the forecast period.
Report Deliverables and Operational Intelligence Assets
This research publication is structured to convert macro-level market signals into practical decision-support tools. Rather than functioning as a static data compilation, the report integrates modeled forecasts, segmentation architectures, competitive profiles, and regulatory context into a cohesive analytical framework that can be applied directly to capital planning, vendor evaluation, and regional deployment strategy. The following core deliverables form the operational backbone of the study:
- Multi-Period Market Modeling: A comprehensive historical reconstruction covering 2020 through 2025 establishes the baseline from which forward projections are derived. The forecast module extends through 2032, providing year-by-year revenue trajectories that enable organizations to align inspection budgeting with planned production scaling, facility expansion, or quality system modernization initiatives.
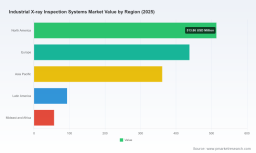
- Segmentation Architecture: The analysis disaggregates the market by region, system type, and end-use application, allowing readers to identify where demand intensity is concentrated and which operational verticals are driving the most substantial inspection investment cycles. This structure supports targeted planning by revealing the relative weight of different market constituents without reducing the analysis to superficial share comparisons.
- Competitive Profiling and Benchmarking: Detailed profiles of core global and regional equipment manufacturers are paired with recent product launch and update timelines to illustrate how vendor strategies are evolving. These profiles cover technology focus areas, application coverage, geographic footprints, and recent development activity, giving executives a structured basis for evaluating partnership candidates and assessing platform differentiation.
- Regulatory and Technology Context Mapping: The report integrates compliance-driven demand catalysts and detector technology transitions into the broader market narrative, ensuring that strategic recommendations reflect both the mandatory requirements shaping procurement and the technological shifts that will influence system longevity and performance expectations.
- Strategic Application Guidance: Beyond descriptive analysis, the report translates findings into actionable planning considerations for engineering, quality assurance, procurement, and executive leadership. This includes guidance on evaluating total cost of ownership, aligning inspection capabilities with production line architecture, and positioning inspection investments to satisfy both current compliance mandates and anticipated regulatory trajectories.
Each deliverable is designed to connect directly to a specific decision-making function. Procurement teams can use the competitive profiling and market modeling components to benchmark vendor proposals and forecast replacement cycles. Quality and engineering leaders can leverage the segmentation and regulatory context sections to align inspection protocols with product risk profiles and compliance exposure. Executive strategists can draw on the full framework to determine whether inspection capability should be centralized, decentralized, or structured as a hybrid model that balances standardization with application-specific flexibility.
Strategic Conclusions for the 2026 Decision Cycle
The industrial X-ray inspection market is entering a phase in which growth is sustained not by isolated demand spikes, but by durable structural shifts in manufacturing complexity, regulatory expectations, and imaging technology maturity. For organizations preparing 2026 investment plans, the strategic imperative is to treat inspection infrastructure as a long-horizon capability investment rather than a transactional equipment purchase. The insights contained in this report are intended to support that shift by providing a disciplined, data-informed view of market direction, competitive behavior, and the practical levers available to organizations seeking to strengthen product integrity while managing capital efficiency.
Complete segmentation breakdowns, competitive benchmarking matrices, and forward-looking scenario analysis are contained within the full research publication. Readers seeking the granular numerical architecture required for detailed budgeting, vendor negotiation, or regional expansion modeling are encouraged to access the complete report to obtain the full intelligence set necessary for confident strategic decision-making in the 2026–2032 period.
For detailed analysis of this topic, please visit the official page: Industrial X-ray Inspection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com