

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Graphite Electrodes Market Hits $17.3B in 2025, Forecast 4.8% CAGR to 2032

Navigating the Turning Point: Strategic Intelligence for the Graphite Electrodes Market 2026–2032
The global graphite electrodes industry stands at a critical inflection point as it moves through 2026. For executives, procurement leaders, and investors, the confluence of shifting trade regimes, raw material volatility, and accelerating adoption of ultra-high-power solutions demands more than surface-level market commentary. It requires a rigorous, data-grounded view of how revenue streams, competitive positioning, and supply chain architecture will evolve across the forecast window. The latest PW Consulting Graphite Electrodes Market study delivers precisely that intelligence, translating historical performance from 2020 through 2025 into a forward-looking framework that maps the trajectory from 2026 to 2032.
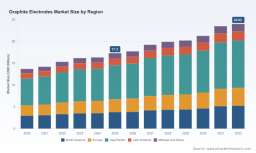
This market has demonstrated remarkable resilience amid macroeconomic turbulence, reaching an estimated 17.3 billion USD in 2025. The forward path reflects sustained industrial demand and structural shifts in steelmaking technology, with the market projected to reach approximately 24.0 billion USD by 2032. Across the seven-year forecast horizon, the compound annual growth rate is estimated at 4.8 percent, signaling steady but uneven expansion that will reward organizations capable of aligning capacity, sourcing, and pricing strategies with regional and technological realities.
Yet aggregate figures only tell part of the story. The real strategic value lies in understanding where growth concentrates, which product categories capture premium margins, and how regulatory interventions are redrawing competitive lines. This report is designed to equip decision-makers with actionable clarity while protecting the integrity of forward-looking intelligence that can be operationalized immediately.
The Strategic Imperative for 2026 Decision-Makers
2026 is not a year for incremental adjustments. It is a year defined by structural realignment. Graphite electrodes remain the lifeblood of electric arc furnace steelmaking, and as global steel producers continue to prioritize lower-emission, flexible production routes, demand for high-performance electrode solutions continues to deepen. At the same time, the supply side is navigating tightening raw material conditions. Petroleum needle coke, the primary upstream feedstock, has experienced pronounced price pressure driven by tight availability and crude oil volatility in late 2025. For electrode manufacturers and end-users alike, this translates into margin compression risks, inventory planning complexity, and an urgent need to reevaluate procurement contracts and hedging mechanisms.
Simultaneously, the regulatory environment has shifted decisively. Trade remedy actions targeting large-diameter graphite electrodes from China and India have introduced new uncertainty into cross-border sourcing strategies. Major North American producers have formally petitioned for antidumping and countervailing duties, and preliminary determinations indicate material injury to domestic industry. In parallel, other jurisdictions have tightened import controls, with significant provisional duty rates imposed by Japan on certain Chinese-origin electrodes. These developments are not isolated events; they represent a broader recalibration of trade flows that will reshape regional pricing dynamics, capacity utilization, and the competitive balance between integrated incumbents and emerging supply sources.
In this environment, strategic planning without granular segmentation and scenario-based forecasting is a liability. Organizations need to understand how different product categories are positioned, which applications drive the majority of revenue, and how regional markets diverge in terms of growth velocity and regulatory exposure. The full report unpacks these dimensions in depth, providing the granularity required to build procurement roadmaps, capacity expansion theses, and competitive response playbooks.
What the Report Delivers: An Operational Blueprint
PW Consulting’s Graphite Electrodes Market study is structured to move beyond high-level trends and deliver operational utility. The analysis draws on a multi-year historical dataset spanning 2020 to 2025, anchored by a base-year assessment for 2025 and extending through a detailed forecast period from 2026 to 2032. The report combines top-down market sizing with bottom-up validation, ensuring that revenue trajectories reflect both macroeconomic demand drivers and industry-specific supply constraints.
Key components of the study include:
Graphite Electrode Rod Market
- Historical revenue performance tracking from 2020 through 2025, illustrating how the market navigated post-pandemic recovery, raw material shocks, and shifting steelmaking demand patterns.
- Forward-looking revenue projections across the 2026–2032 window, with annual estimates that capture inflection points linked to trade policy implementation, capacity expansions, and product mix evolution.
- Demand segmentation by application, highlighting how electric arc furnace steelmaking continues to anchor consumption while ladle furnace operations and other industrial uses contribute distinct growth profiles.
- Product-type analysis distinguishing ultra-high-power, high-power, and regular-power electrodes, with attention to performance requirements, pricing premiums, and end-user qualification trends.
- Regional market assessment covering major geographic zones, with an emphasis on demand concentration, import dependency, trade remedy exposure, and localized capacity dynamics.
- Upstream feedstock context, including the role of petroleum needle coke availability and pricing as a critical determinant of manufacturer margins and supply stability.
- Competitive landscape profiling of leading international producers, examining geographic footprints, product readiness, vertical integration strategies, and recent commercial or regulatory moves.
The report is built for practical use. Procurement teams can align contract timing and volume commitments with forecast demand shifts. Strategy leaders can evaluate whether to invest in larger-diameter electrode capabilities, diversify sourcing portfolios, or reposition pricing frameworks in response to regulatory and input-cost pressures. Investors and analysts gain a structured view of market concentration, growth catalysts, and the competitive dynamics that will separate resilient incumbents from exposed challengers.
Product Mix, Application Demand, and the Ultra-High-Power Shift
The composition of electrode demand is increasingly tilted toward higher-performance grades, reflecting the ongoing modernization of electric arc furnace operations. Ultra-high-power electrodes have become the default choice for many large-scale steel producers seeking improved thermal efficiency, longer campaign life, and the ability to operate at higher power inputs. This shift is not merely technical; it carries direct implications for pricing power, supply chain qualification cycles, and the competitive positioning of manufacturers with specialized production capabilities.
High-power and regular-power electrodes continue to play important roles across a broader set of industrial applications, but their growth trajectories diverge sharply from the premium segment. Understanding where each category finds demand, how substitution dynamics play out under cost pressure, and which end-use markets are expanding or contracting is essential for accurate revenue forecasting and product portfolio planning. The full report provides a detailed breakdown of these categories, including the relative contribution of each to overall market revenue and the structural factors shaping their outlook through 2032.
At the application level, electric arc furnace steelmaking remains the dominant driver of graphite electrode consumption, supported by the global shift toward electric-based steel production routes. Ladle furnace operations and other industrial processes add meaningful incremental demand, but their growth profiles differ based on plant utilization rates, process optimization trends, and regional steelmaking configurations. The report examines these application dynamics with sufficient granularity to help users identify where volume growth is most resilient and where sensitivity to economic cycles or capacity rationalization is highest.
Regional Dynamics and the New Trade Reality
Regional divergence has become one of the defining features of the graphite electrodes market. Asia Pacific continues to represent a substantial share of global demand, reflecting the scale of steel production in the region and the ongoing expansion of electric arc furnace capacity. North America and Europe, while smaller in absolute terms, are experiencing distinct competitive and regulatory shifts that alter pricing behavior, import patterns, and domestic production incentives. Latin America and the Middle East and Africa contribute additional demand streams, often tied to specific industrial development pathways and trade linkages.
What makes the current moment particularly consequential is the interaction between regional demand and trade policy. Recent trade remedy filings targeting large-diameter graphite electrodes from China and India have introduced new friction into established supply routes. Preliminary determinations by the United States International Trade Commission have signaled material injury to domestic industry, while provisional duties in other markets, including the notable Japanese action on certain Chinese imports, illustrate how quickly trade barriers can reshape sourcing economics. These interventions do not merely affect price; they influence where capacity is built, which suppliers can reliably serve specific markets, and how risk is distributed across the value chain.
Graphite Electrodes Market
A complete regional analysis is essential because aggregate market growth can mask highly uneven local trajectories. The full report disentangles these patterns, providing a region-by-region view of demand strength, import exposure, capacity positioning, and the likely impact of ongoing trade proceedings. This level of detail is critical for organizations that must align sourcing, distribution, and pricing strategies with specific jurisdictional realities rather than broad global averages.
Competitive Landscape: Integration, Scale, and Strategic Agility
The graphite electrodes market is characterized by a consolidated core of global incumbents alongside regionally focused producers with strong local execution. Market concentration remains moderate at the top, with the largest firms commanding a meaningful but not dominant share of total revenue, leaving ample room for specialized players and regional champions to compete effectively in particular segments or geographies.
Several leading companies illustrate the strategic directions shaping the market. GrafTech International Ltd., headquartered in Brooklyn Heights, Ohio, has established itself as a major producer and supplier of ultra-high-power graphite electrodes, including 800-millimeter-diameter super-sized electrodes for electric arc furnace steelmaking. Its vertically integrated position extends into petroleum needle coke production, with facilities across France, Spain, Mexico, and Pennsylvania, giving it a structural advantage in feedstock control and supply continuity. In recent months, GrafTech has taken two notable steps that underscore its positioning: the successful qualification and launch of 800-millimeter electrodes for additional furnaces in 2025, and a 2026 price increase on uncommitted volumes aimed at restoring sustainable pricing levels across regions.
HEG Limited, based in Bhopal, India, operates what is recognized as the world’s largest single-site integrated plant for high-power and ultra-high-power graphite electrodes. Its focus on large-diameter electrodes for electric arc furnace steel production positions it as a central player in one of the most demand-intensive segments of the market. The scale and integration of its operations give it a distinct cost and supply chain profile, particularly relevant as global trade flows face new restrictions.
Tokai Carbon Co., Ltd., headquartered in Tokyo, Japan, maintains a global production footprint spanning Japan, Europe, and North America. It supplies ultra-high-power electrodes for electric arc furnace steelmaking and has navigated regional capacity adjustments in Japan and Europe, reflecting the strategic recalibration that many multinational electrode producers are undertaking in response to demand shifts and cost pressures. Its North American subsidiary, Tokai Carbon GE LLC, based in Charlotte, North Carolina, produces graphite electrodes and connecting pins up to 800 millimeters, reinforcing the group’s commitment to the U.S. industrial market.
Resonac Graphite America Inc., located in Ridgeville, South Carolina, is a producer and supplier of high-quality graphite electrodes for electric arc furnaces, ladle furnaces, and non-ferrous applications. As part of the broader Resonac Group, it operates plants across the Americas, EMEA, and Asia, with involvement in large-diameter electrode supply. In a significant sustainability milestone, Resonac Graphite achieved the world’s first verified Environmental Product Declaration for graphite electrodes in late 2025, establishing an official global benchmark that may influence procurement preferences, especially among steelmakers pursuing ESG-linked sourcing criteria.
Graphite India Limited, headquartered in New Delhi, is another major producer of ultra-high-power graphite electrodes for steelmaking, with plants in India and Europe. It is recognized as one of the five largest global producers outside China, a positioning that carries strategic importance as trade remedy actions redirect flows away from certain Chinese and Indian large-diameter exports into alternative supply channels.
Together, these companies reflect the core strategic themes of the market: vertical integration into needle coke, scale in large-diameter production, regional footprint optimization, sustainability differentiation, and active engagement in trade and pricing defense. The full report profiles these and other key players in greater depth, linking corporate capabilities to market share dynamics, regional exposure, and likely competitive responses through the forecast period.
Regulatory and Input-Cost Pressure: Two Forces Reshaping Margins
Two external forces are exerting the greatest influence on near-term market economics: trade regulation and raw material availability. On the trade front, the filing of antidumping and countervailing duty petitions by major North American entities in early 2026 marks a pivotal moment for large-diameter graphite electrodes. Preliminary findings have supported the view that imports from China and India are materially injuring the U.S. domestic industry, and the resulting duties could substantially alter the cost base for buyers reliant on those supply routes. In combination with earlier provisional measures in other markets, these actions suggest a broader trend toward protection of domestic electrode production and a reevaluation of import dependency.
On the raw material side, petroleum coke and needle coke prices have surged due to tight supply and crude oil volatility in late 2025. Since petroleum needle coke is the primary upstream feedstock for graphite electrodes, any sustained increase in input costs directly pressures manufacturer margins and, in turn, shapes pricing strategies across the value chain. For integrated producers with captive needle coke capacity, these conditions may offer relative relief and margin protection. For non-integrated suppliers and end-users negotiating long-term contracts, the environment demands more flexible pricing mechanisms, closer inventory management, and a clearer understanding of where cost increases can be absorbed versus passed through.
These forces do not operate in isolation. Trade restrictions can shift demand toward alternative suppliers, tightening their order books and affecting lead times. Raw material inflation can amplify the impact of import duties by raising the floor for domestic pricing. The interplay between regulation and input costs is precisely the kind of multi-variable dynamic that requires scenario-based analysis rather than single-point forecasts. The complete report provides that analytical structure, including the conditions under which different margin outcomes are most likely.
Why the Full Study Matters for the 2026–2032 Horizon
The graphite electrodes market is entering a phase where strategic advantage will belong to organizations that can connect market structure to operational execution. The headline growth trajectory, moving from approximately 17.7 billion USD in 2026 toward more than 24 billion USD by 2032, is encouraging, but it does not by itself indicate where value will accrue. Growth will be uneven across applications, product types, and regions. Pricing will be shaped by feedstock conditions, trade policy outcomes, and the willingness of leading producers to defend sustainable price levels. Competitive positioning will increasingly depend on integration, large-diameter capability, sustainability credentials, and the ability to navigate cross-border regulatory complexity.
PW Consulting’s full Graphite Electrodes Market research translates these dynamics into a structured, decision-ready intelligence package. It offers the historical context needed to interpret current conditions, the segmentation detail required to prioritize investment and procurement choices, and the competitive and regulatory analysis essential for anticipating disruptive shifts. Rather than leaving organizations to piece together partial signals from quarterly filings, trade notices, and commodity price moves, the study consolidates them into a coherent strategic framework.
For executives planning capacity, sourcing, pricing, or market entry decisions in 2026 and beyond, the difference between an informed strategy and a reactive one often comes down to granularity. The report is designed to provide that granularity, while maintaining the forward-looking discipline necessary to support decisions through 2032.
To access the complete segmentation detail, regional analysis, competitive profiling, and scenario-based forecasts, explore the full market research here: https://www.pwconsulting.com/graphite-electrodes-market .
For detailed analysis of this topic, please visit the official page: Graphite Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com