

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Soft Ferrite Core Market to Reach $344.8 Million by 2032, Posting 6.98% CAGR

Strategic Intelligence for 2026: The Soft Ferrite Core Market in a Transforming Landscape
As global industries navigate structural shifts in electrification, connectivity, and energy efficiency, the soft ferrite core market has emerged as a critical enabler of next-generation electronic and power systems. Our latest market research delivers a comprehensive, forward-looking assessment of this sector, positioning enterprise leaders with the analytical rigor required to make informed capital allocation, sourcing, and product development decisions throughout the 2026–2032 horizon. This introductory insight outlines the strategic value of the full report, highlighting macro trajectory, competitive positioning, supply chain dynamics, and the operational frameworks that will define market winners in the years ahead. Readers seeking granular segmentation data, regional revenue breakdowns, and company-level market share modeling are encouraged to explore the complete research package, where granular intelligence is structured for immediate executive application.
The Strategic Imperative for 2026 Decision-Making
The soft ferrite core industry sits at the intersection of multiple secular trends: expanding consumer electronics penetration, rapid automotive electrification, and the proliferation of power conversion systems across industrial and infrastructure applications. For executives operating in 2026, the challenge is no longer simply understanding market direction but anticipating how component-level dynamics will cascade into product cost structures, supply chain resilience, and competitive differentiation. Our research is designed to translate macroeconomic signals into actionable strategic guidance, helping organizations align procurement strategies, R&D roadmaps, and market entry plans with the evolving reality of the ferrite ecosystem. The base year of 2025 establishes a reliable historical foundation, while the forecast window through 2032 provides a sufficiently extended planning horizon to evaluate long-cycle investments, capacity expansion decisions, and technology roadmap commitments.
Market Trajectory and Growth Architecture
The historical record from 2020 through 2025 demonstrates a consistent upward trajectory for soft ferrite core revenues, reflecting sustained demand absorption across multiple end-use verticals. This growth momentum carries forward into the forecast period, supported by expanding power electronics deployments, higher switching frequency requirements, and the ongoing miniaturization of magnetic components. The compound annual growth rate projected for the forecast window underscores a structurally expanding market rather than a cyclical upturn. Revenue progression across the forecast years reveals an accelerating expansion profile, with incremental annual gains compounding into a materially larger addressable market by the end of the decade. This trajectory signals that early-mover positioning, strategic supplier partnerships, and forward-looking inventory and capacity planning will yield disproportionate advantages as demand scales.
Segmentation Architecture and Application Dynamics
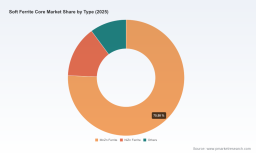
Understanding how demand distributes across product types, end-use applications, and geographies is essential for precise go-to-market execution and portfolio prioritization. Soft ferrite cores bifurcate primarily into MnZn and NiZn variants, each serving distinct technical requirements and cost-performance trade-offs. MnZn materials dominate volume-intensive power conversion and transformer applications where cost efficiency and magnetic permeability are paramount, while NiZn formulations address high-frequency, low-loss, and EMI suppression scenarios demanding specialized electrical characteristics. The application landscape is led by consumer electronics, which absorbs the largest share of core demand driven by continuous device iteration, power management complexity, and connectivity expansion. Automotive applications represent a strategically significant and growing demand pool, fueled by onboard power electronics, charging infrastructure, motor control systems, and electrification architectures that require robust, thermally stable magnetic components. Additional application verticals contribute further diversification, spanning industrial automation, telecommunications, medical equipment, and infrastructure power systems.
Geographic distribution of demand reflects mature industrial ecosystems, high-growth manufacturing regions, and emerging market expansion corridors. Regional demand profiles are shaped by local electronics manufacturing intensity, automotive production footprints, infrastructure investment cycles, and the location of key supplier operations. The full research deconstructs these geographic dynamics in detail, providing executives with the regional intelligence needed to calibrate sales coverage, distribution partnerships, and localized sourcing strategies without exposing the market to oversimplified regional narratives.
Competitive Landscape and Strategic Positioning
The competitive structure of the soft ferrite core market is characterized by a moderately concentrated industry where leading manufacturers compete on technical capability, production scale, global supply reach, and application-specific engineering support. Market concentration metrics indicate that while the top players hold meaningful positioning, a substantial share of demand is served by a broad field of specialized and regional producers, creating a competitive environment where differentiation, reliability, and supply continuity are decisive.
Several established manufacturers anchor the global landscape, each bringing distinct capabilities and strategic focus areas. TDK Corporation operates as a leading manufacturer of MnZn and NiZn soft ferrite cores across multiple geometries, serving power electronics, EMI suppression, and high-frequency applications with a diversified product architecture. Ferroxcube International Holding B.V. maintains a global manufacturing footprint spanning Europe, Asia, and the United States, delivering MnZn and NiZn cores and accessories for telecom, power, and industrial markets with an emphasis on broad application coverage. DMEGC Magnetics Co., Ltd. stands as a major Chinese producer of MnZn and NiZn cores in standard and custom shapes, supporting power supplies, inductors, and automotive applications with strong domestic and export-oriented capacity. MAGNETICS Inc. contributes a US-based manufacturing base focused on MnZn soft ferrite cores for chokes, inductors, and power electronics across telecommunications, aerospace, and medical end markets, where qualification rigor and supply reliability are particularly valued. Proterial, Ltd. offers MnZn and NiZn cores engineered for advanced low-loss and high-frequency performance, targeting transformers, inductors, and energy-related applications where electrical efficiency is a primary design constraint. Cosmo Ferrites Ltd. and Acme Electronics represent Indian manufacturing capabilities with export-oriented strategies, producing MnZn soft ferrite cores for power, telecom, consumer, and industrial electronics, reinforcing the importance of regional sourcing diversification and cost-competitive supply alternatives.
Recent corporate activity illustrates how competition is evolving beyond steady-state production into capacity expansion, product line extension, and strategic collaboration. TDK expanded its large-size ferrite core lineup with new shapes designed for EV charging, UPS, solar inverters, motor drives, and industrial applications, signaling proactive alignment with electrification and renewable power conversion demand. Separately, Premo and Delta Manufacturing formed a joint venture in India to enhance soft ferrite core component manufacturing and innovation for the electronics industry, reflecting a broader trend toward regional capacity reinforcement and collaborative capability building in high-growth manufacturing geographies.
Supply Chain, Raw Material, and Regulatory Dynamics
Cost structures and supply continuity in the soft ferrite core market are heavily influenced by raw material availability, commodity pricing volatility, and evolving regulatory frameworks. Raw material inputs represent a substantial portion of total manufacturing expenses, with historical annual commodity fluctuations creating periodic margin pressure and procurement complexity. Input cost variability for NiZn ferrite materials, spanning iron oxide, zinc oxide, and nickel, has historically moved within broad annual fluctuation ranges, requiring disciplined sourcing strategies, hedge-aware purchasing, and supplier diversification to protect profitability.
Recent industry data highlights concrete supply-side pressures. Producer price indices for nonmetallic mineral products have pointed to steady moderate inflation in key input materials used for ferrite cores, reinforcing the need for forward-looking cost modeling. Manganese oxide pricing experienced notable increases in 2023, and ongoing supply fluctuations have continued to affect NiZn ferrite production costs and procurement lead times. Iron oxide grades have faced declines in purity availability linked to mining disruptions in South Africa and Australia, creating ripple effects through ferrite core supply chains and underscoring the vulnerability of geographically concentrated raw material flows.
Regulatory developments add further complexity to procurement and capacity planning. The US DOE tightened manganese quotas for ferrite cores effective 2026, imposing a reduction in annual import quotas for manganese-iron alloys. This policy shift introduces a new dimension of supply constraint for US-facing operations and reinforces the strategic importance of qualified alternative sourcing, inventory buffering, and regional compliance planning. Together, these raw material and regulatory dynamics illustrate that competitive resilience will depend not only on product performance but also on supply chain architecture, supplier qualification depth, and procurement agility.
Ferrite Cores Market
What the Full Research Delivers
The complete Soft Ferrite Core Market research extends far beyond headline growth figures to provide executives with a multidimensional intelligence framework. The report integrates historical performance analysis, forecast modeling, segmentation mapping, competitive profiling, and supply chain risk assessment into a unified reference architecture. Key deliverables include detailed market sizing across the historical and forecast periods, structured segmentation analysis across product types, applications, and regional markets, and a comprehensive view of the competitive landscape anchored by company profiles, capability assessments, and recent strategic moves.
The research also examines market concentration dynamics, providing clarity on share distribution and the competitive implications of consolidation versus fragmentation. Operational and strategic content covers demand drivers, technology and performance trends, pricing and cost structure considerations, and regulatory influences that shape procurement and market access. By aligning macro trajectory with segment-level mechanics and competitive intelligence, the report enables decision-makers to evaluate opportunity sizing, identify high-potential application and product intersections, assess supplier reliability, and anticipate the impact of commodity and regulatory shifts on cost planning.
Navigating 2026 and the Forecast Horizon
For enterprise leaders, the strategic task in 2026 is to convert market visibility into disciplined execution. Growth in the soft ferrite core market is supported by durable demand drivers, yet the environment also features material cost volatility, evolving regulatory constraints, and a competitive field that rewards technical differentiation, supply reliability, and geographic flexibility. Organizations that treat this market as a strategic component of their broader power electronics, automotive, and electronics sourcing portfolios will be better positioned to secure favorable supply terms, align product development with high-growth application trajectories, and manage risk across raw material and regulatory fronts.
Soft Ferrite Core Market
The full research package is structured to support this execution-oriented mindset, offering the depth and precision needed to inform procurement strategy, product planning, investment prioritization, and competitive positioning. For decision-makers who require detailed segmentation data, regional demand breakdowns, and company-level intelligence to support 2026 planning cycles, the complete report provides the comprehensive picture necessary to move from insight to action.
For detailed analysis of this topic, please visit the official page: Soft Ferrite Core Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com