

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dibasic Ester Market Reaches $162M in 2025, Projected 6.5% CAGR Through 2032

Navigating the Dibasic Ester Market: Strategic Intelligence for 2026 Decision-Makers
The dibasic ester (DBE) market is transitioning from a niche solvent category into a strategic pillar for sustainable industrial chemistry. As regulatory architectures tighten around volatile organic compounds (VOCs) and hazardous air pollutants, formulators and procurement leaders are recalibrating their solvent portfolios with urgency. PW Consulting’s newly released Dibasic Ester Market research arrives at a critical inflection point, offering the analytical rigor required to navigate a landscape defined by regulatory acceleration, bio-based feedstock maturation, and intensifying competitive positioning. This introduction outlines why this report is essential reading for executives shaping 2026 investment, sourcing, and product development strategies.
The Macro Trajectory: Why Scale Alone Is No Longer Sufficient
Historical performance in the DBE sector reveals a steady upward climb, reflecting broader industrial shifts toward lower-toxicity, readily biodegradable solvent systems. From a base perspective in 2025, the overall market size has expanded consistently over the past half-decade, with mid-2020s momentum setting the stage for the current forecast window. Our analysis projects the global DBE market to surpass the USD 240 million threshold by the close of the forecast period, underpinned by a compound annual growth rate of 6.5 percent across 2026 through 2032.
These headline figures, however, mask the operational realities that determine winners and laggards in this space. Growth is not evenly distributed across end-use verticals or geographic corridors. Instead, it concentrates where regulatory pressure intersects with technical feasibility and where supply chains have secured reliable access to both petrochemical and emerging bio-based acid streams. A surface-level grasp of aggregate revenue projections leaves procurement teams vulnerable to mispriced contracts, misaligned capacity commitments, and missed opportunities in high-margin specialty grades. The full report dissects these structural drivers without exposing sensitive segmentation data, guiding strategic readers toward a complete intelligence package that reveals precisely where value is being created and captured.
Regulatory Tailwinds and Feedstock Evolution: The Dual Engines of Demand
The impetus behind DBE adoption is no longer driven solely by performance characteristics. A converging set of regulatory and sustainability mandates is compressing decision timelines for coatings manufacturers, industrial cleaner formulators, and specialty polymer producers. In North America, ongoing TSCA reviews of legacy solvents and EPA NESHAP standards are accelerating reformulation activity, positioning DBE as a priority alternative to hazardous air pollutants and VOC-intensive carriers. Parallel developments in Europe, where ECHA enforcement of REACH and EU Green Deal commitments are compelling formulators across Germany, France, the Netherlands, and Italy to replace chlorinated and high-VOC solvents, have created a structural demand pull that extends well beyond incremental substitution.
Simultaneously, the feedstock narrative is shifting from theoretical advantage to commercial viability. Bio-based dimethyl succinate derived from fermentation of corn, sugarcane, or lignocellulosic biomass has achieved cost parity within approximately 15 to 20 percent of petrochemical equivalents as of 2025. This narrowing cost gap, coupled with bio-succinate projects for DBE variants advancing toward full commercialization between 2025 and 2027, reinforces the sustainability credentials of the DBE product family. Strategic partnerships between specialty fermentation companies and established DBE producers have announced commercial-scale bio-succinate projects slated for operation between 2026 and 2028, signaling a supply-side transformation that will reshape cost structures and carbon intensity profiles across the value chain.
These dynamics demand scenario-based procurement planning rather than static sourcing models. The report maps how regulatory timelines, regional enforcement intensity, and feedstock availability interact to influence near-term pricing volatility, medium-term contract structures, and long-term capacity allocation. Readers who access the complete study will gain a framework for evaluating supplier resilience, anticipating reformulation bottlenecks, and aligning solvent transitions with corporate sustainability targets without compromising performance specifications.
Dibasic Ester (DBE) Market
Competitive Landscape: Differentiation in a Moderately Concentrated Market
The DBE industry operates under moderate concentration, with the top three players capturing roughly one-third of aggregate market share and the top five accounting for close to half. This structure creates a marketplace where scale provides baseline stability, but differentiation—rooted in feedstock origin, purity grades, regional distribution capability, and application-specific technical support—determines competitive endurance. The report evaluates core participants across North America, Europe, and Asia Pacific, tracing how each enterprise is positioning its portfolio to capture value in a rapidly evolving demand environment.
In the United States, Invista has anchored its strategy around INVISTA DBE™ esters and DBA dibasic acid, produced from adipic acid with a minimum of 55 percent recycled content. These materials are readily biodegradable and supplied as solvent solutions tailored for coatings, polyurethane polyols, recycling solvents, and soil stabilization. In 2023, Invista announced an investment in a new bio-based DBE production facility, signaling a long-term commitment to integrating circular feedstock pathways into mainstream solvent supply. Ascend Performance Materials, based in Charlotte, has advanced its FlexaTrac®-DME platform, a clear, colorless, low-odor liquid produced by reacting methanol with adipic, glutaric, and succinic acid streams and fractionated for high-performance applications in coatings, resins, and industrial settings. Eastman Chemical Company rounds out the U.S. competitive tier with an established DBE product line and custom blends, leveraging one of the broadest portfolios and geographic commercial networks available for coatings and solvent applications.
European players are navigating a regulatory-heavy environment while expanding specialty-grade capabilities. Radici Group, operating from Bergamo, Italy, channels DBE products through its European manufacturing base and specialty chemical distribution networks, targeting industrial solvents and performance materials. Solvay S.A., headquartered in Brussels, has focused on high-purity DBE grades within its European specialty solvents portfolio, serving coatings, pharmaceutical, and personal care applications. Notably, Solvay unveiled an innovative low-VOC DBE formulation for automotive applications in early 2023, illustrating how product-level innovation can unlock adjacent end-use verticals with stringent emission requirements.
In Asia Pacific, capacity expansion and specification-grade upgrading are reshaping competitive dynamics. Shandong Yuanli Science and Technology Co., Ltd., based in Weifang, Shandong, operates a large-scale production platform for its Dibasic Ester (MDBE) series, with annual output exceeding 90,000 tons as part of a broader fine chemicals portfolio serving the paint and coating industry. Changle Yili Chemical Co., Ltd., also situated in Weifang, focuses on DBE production with annual capacity of 20,000 tons of dibasic ester and related dimethyl adipate, targeting high-boiling-point solvents for coatings, printing ink, and dispersants. Jiangsu Baichuan High-tech New Materials Co., Ltd., operating in Jiangsu, emphasizes high-tech new materials and DBE production with a clear emphasis on upgrading quality capabilities for specification-grade contracts in advanced application markets. Rounding out the competitive field, KH Neochem Co., Ltd. in Japan concentrates on high-purity specialty-grade DBE products for Japanese electronics and pharmaceutical customers with exacting quality requirements, demonstrating how niche technical positioning can sustain premium value even in a moderately consolidated market.
Rather than presenting a simple brand directory, the report evaluates the strategic intent behind these corporate moves: capacity reallocation, feedstock diversification, grade specialization, and geographic channel expansion. It maps where consolidation pressures are most likely to emerge, which application-adjacent opportunities remain under-penetrated, and how bio-based investments will alter the competitive hierarchy through the end of the forecast window. The complete analysis reserves detailed market share trajectories, regional capacity balances, and supplier-specific risk assessments for the full publication, ensuring that commercial sensitivity is preserved while delivering actionable competitive intelligence.
Report Structure and Operational Value for 2026 Planning
PW Consulting’s Dibasic Ester Market research is designed as a decision-support instrument rather than a static market summary. The report integrates historical baseline data from 2020 through 2025 with a forward-looking forecast covering 2026 through 2032, enabling executives to benchmark recent performance against projected trajectory and identify inflection points before they materialize in quarterly results. The methodology combines top-down market sizing with bottom-up segmentation logic, ensuring that aggregate trends are grounded in realistic capacity, demand substitution, and regulatory timing assumptions.
Worldwide Dibutyl Maleate (DBM) Market
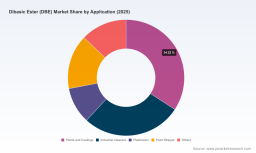
Inside the publication, readers will find a structured examination of market dynamics, including regulatory catalysts, raw material cost trajectories, and substitution patterns across solvent families. The analysis evaluates how TSCA and REACH-driven reformulation cycles are compressing adoption timelines and reshaping demand concentration across coatings, industrial cleaners, plasticizers, paint strippers, and ancillary applications. Supply-side considerations are addressed through feedstock availability, bio-based commercialization schedules, and the implications of narrowing cost differentials between renewable succinate derivatives and conventional petrochemical routes.
Competitive assessments are presented with an emphasis on strategic posture rather than headline ranking. The report examines how established producers are leveraging geographic networks and portfolio breadth, how regional specialists are targeting high-purity or specification-grade niches, and how bio-based investments are being staged to align with regulatory milestones and customer sustainability requirements. Recent corporate developments—including facility investments and product launches—are contextualised within broader market movements, offering a realistic view of which initiatives are likely to scale and which remain constrained by feedstock logistics or application qualification cycles.
For 2026 planning, this content translates into several operational advantages. Procurement and sourcing teams can evaluate contract timing against anticipated regulatory enforcement waves and bio-based feedstock entry points. R&D and formulation groups can identify where DBE substitution is technically viable versus where performance trade-offs or qualification bottlenecks will delay adoption. Strategy and corporate development functions can gauge where consolidation, capacity additions, or specialty-grade differentiation will create entry opportunities or intensify competitive pressure. The full report deliberately withholds granular regional and application-level breakdowns in this introductory format, reinforcing the need to access the complete intelligence suite for precise quantification, scenario modelling, and supplier-specific benchmarking.
Accessing the Complete Intelligence Package
The Dibasic Ester market is entering a phase where strategic advantage will belong to organizations that can align solvent selection with regulatory timing, feedstock evolution, and application-specific qualification pathways. PW Consulting’s market research provides the depth, structure, and forward-looking analysis required to make those alignments with confidence.
This introduction has outlined the macro trajectory, regulatory and feedstock catalysts, competitive positioning, and report architecture designed to support 2026 decision-making. To obtain the detailed segmentation splits, regional demand balances, application-level volume and value dynamics, and supplier-specific assessments that underpin these conclusions, readers are encouraged to access the full report on the PW Consulting source page. The complete publication delivers the quantified intelligence and scenario frameworks necessary to transform market awareness into executable strategy across sourcing, capacity planning, product development, and competitive positioning.
For detailed analysis of this topic, please visit the official page: Dibasic Ester (DBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com