

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Contact Image Sensor Market to Hit $2.52B by 2032 at 7.2% CAGR

Strategic Intelligence for the Contact Image Sensor Market: Navigating the 2026-2032 Cycle
The ability to capture high-fidelity images precisely at the point of contact has moved from a niche engineering requirement to a core enabling technology across manufacturing, financial services, and document digitization. As we enter the 2026 fiscal cycle, the Contact Image Sensor Market finds itself at a critical inflection point, shaped by rapid advancements in CMOS integration, increasing demand for inline inspection in semiconductor and battery production, and a shifting competitive landscape defined by corporate restructuring and strategic product expansions. For executives, investors, and R&D strategists, generic market overviews no longer suffice. The decisions made in the next twelve to eighteen months will determine competitive positioning through the end of the decade. This exclusive market research publication has been engineered to provide the actionable, granular intelligence required to navigate this period with confidence.
Market Trajectory: From Historical Consolidation to Accelerated Growth
An analysis of historical data from 2020 through 2025 reveals a market that has steadily expanded its revenue base while navigating supply chain constraints and regional demand fluctuations. The industry has demonstrated consistent upward momentum, transitioning from a mature baseline to an accelerated growth phase. Looking forward over the 2026 to 2032 forecast period, the market is projected to sustain a robust compound annual growth rate of 7.2 percent. This trajectory is not merely a linear continuation of past trends but reflects a structural expansion driven by the replacement of aging imaging technologies, the proliferation of high-resolution inspection requirements in advanced manufacturing, and the continuous digitization of archival and transactional document workflows.
Reaching a market valuation of approximately 1.55 billion USD by the 2025 base year, the sector is expected to surpass the 1.68 billion USD threshold in 2026, before climbing steadily toward a projected valuation exceeding 2.5 billion USD by the close of 2032. This expansion underscores a fundamental shift in how optical sensing is deployed. Enterprises are no longer treating contact image sensors as commoditized components; they are integrating them as performance-critical differentiators in systems where spatial resolution, read rate, and form-factor constraints dictate operational success. Understanding the precise pull-through drivers across inspection, reproduction, and specialized financial hardware is essential for any organization preparing to allocate capital or engineering resources in this space.
Structural Decomposition and Application-Driven Demand Shifts
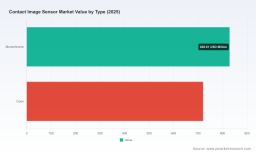
While headline figures provide a valuable macro context, the real strategic value lies in understanding how demand fractures across technology types, end-use applications, and geographic ecosystems. The market has bifurcated notably between monochrome and color imaging pathways, each serving distinct performance and cost requirements. Monochrome solutions continue to anchor high-speed industrial inspection and specialized reading applications where spectral simplicity and computational efficiency are paramount. Concurrently, color-focused architectures are gaining traction in document reproduction and archival scanning, where fidelity to original materials constitutes the primary value proposition. Our research dissects the specific pull factors, technological thresholds, and adoption curves that distinguish these two pathways, enabling readers to assess which technology trajectory aligns with their product roadmaps.
On the application front, scanners remain a dominant demand center, reflecting the enduring need for high-throughput digitization across enterprise and governmental sectors. Copy machines continue to represent a stable, mature consumption base, though incremental upgrades are increasingly driven by energy efficiency mandates and seamless integration with networked document management ecosystems. Surface inspection systems have emerged as a highly dynamic growth vector, fueled by the necessity for defect detection in semiconductor wafer fabrication, lithium-ion battery manufacturing, and high-precision print production. Banknote readers and related financial authentication hardware provide another specialized, regulation-sensitive vertical where long product lifecycles and stringent compliance requirements shape procurement cycles. The report maps these application segments in detail, identifying where volume growth intersects with margin expansion and where commoditization pressures are beginning to surface.
Regionally, the market exhibits a complex interplay of developed-market sophistication and emerging-market volume growth. North America, Europe, and Asia Pacific each present distinct demand profiles shaped by local manufacturing intensity, regulatory environments, and the maturity of end-user industries. Latin America and the Middle East and Africa contribute additional layers of opportunity driven by infrastructure modernization and localized industrial automation. Because regional procurement patterns, distribution channel dynamics, and competitive intensity vary significantly, a blanket global strategy is inherently suboptimal. Our geographic analysis isolates the most attractive sub-markets for market entry, capacity expansion, or partnership development without relying on broad generalizations.
Competitive Dynamics: Restructuring, Innovation, and Strategic Positioning
The competitive architecture of the contact image sensor market is characterized by a concentrated core of established players alongside a network of specialized integrators and custom-sensor designers. Our analysis tracks the strategic maneuvers of key participants, revealing how corporate restructuring, product line expansions, and OEM partnership strategies are reshaping the playing field.
Mitsubishi Electric Corporation continues to be a foundational presence, leveraging its proprietary CMOS sensor ICs and integrated illumination solutions to serve surface inspection, reproduction equipment, and financial reading applications. Notably, in April 2026, the company issued a formal notice of business transfer for its Contact Image Sensor division to its affiliated entity, Miyoshi Electronics Corporation, with the transition slated to take effect on April 1, 2028. This anticipated restructuring will involve production relocation alongside a long-term commitment to customer supply continuity, a move that signals both vertical integration optimization and a strategic reallocation of operational focus. For downstream equipment manufacturers and procurement teams, understanding the implications of this transfer on pricing, supply assurance, and technical support continuity will be vital.
Worldwide 3D Image Sensor Market
Teledyne DALSA has reinforced its position through targeted technology expansion. In May 2026, the company broadened its AxCIS family of high-speed, high-resolution integrated line scan contact image sensors, introducing new 1,800 dpi and 1,500 mm configurations. These models deliver monochrome line rates reaching up to 80 kHz alongside high dynamic range capabilities, directly addressing the escalating performance demands of machine vision inspection in semiconductor wafer processing, battery cell manufacturing, and precision print applications. Such product launches illustrate how competitive differentiation in this market is increasingly tied to raw throughput, resolution ceilings, and the ability to integrate seamlessly into compact, automated inspection architectures.
Contact Image Sensor Market
Other significant players contribute complementary strategic angles. CMOS Sensor Inc, headquartered in San Jose, California, emphasizes custom-designed contact image sensors that support color imaging and bespoke configuration for application-specific requirements, positioning the firm as a flexible partner for organizations with non-standard imaging constraints. FRAMOS GmbH, based in Germany, focuses on the integration of high-quality CIS modules into compact scanning and machine vision systems, offering engineering support across electrical and optical specifications and catering to OEM equipment manufacturers seeking ready-to-deploy imaging subsystems. ColorTrac, operating from the United Kingdom, has carved a specialized niche with CIS-based large format scanners designed for wide-format printing and document handling, addressing a segment where physical footprint, scan width, and handling robustness dictate adoption.
Across this competitive ecosystem, market concentration metrics indicate that a small group of leading firms commands a substantial share of total revenue, underscoring the importance of understanding incumbent advantages, channel relationships, and technology moats. The full report provides a detailed competitive matrix, mapping each key participant against product capabilities, target applications, regional coverage, and recent strategic moves to help stakeholders identify white space, anticipate competitive responses, and formulate partnership or acquisition scenarios.
Regulatory and Macro-Environmental Forces Shaping Market Behavior
Technological capability does not exist in a vacuum. The evolving regulatory environment introduces new layers of complexity to product design, cross-border procurement, and supply chain planning. In May 2025, Canada's Export Control List was updated to include sensors and lasers under Category 6, with specific clauses addressing equipment capable of measuring surfaces with sub-micron repeatability or 0.5 mm accuracy. This development carries direct implications for high-resolution contact image sensors deployed in precision inspection and metrology applications. Manufacturers, system integrators, and distributors operating in or exporting to jurisdictions with similar export control frameworks must anticipate compliance requirements, documentation burdens, and potential restrictions on certain optical configurations. Our market research contextualizes these regulatory shifts within broader trade dynamics, enabling readers to assess exposure, plan supply chain modifications, and align product positioning with compliance realities before they become operational bottlenecks.
What the Full Research Report Delivers
The complete Contact Image Sensor Market research publication is designed as a decision-support instrument rather than a static data compilation. It provides an integrated, multi-layered view of the industry, connecting macro growth signals to actionable commercial and operational intelligence. Readers will find:
- A comprehensive historical and forecast analysis spanning 2020 through 2032, framed around the 2025 base year and expressed in USD millions, enabling precise scenario modeling and investment benchmarking.
- Deep-dive segmentation analysis that isolates demand drivers, pricing dynamics, and technology adoption curves across type, application, and regional dimensions without relying on generic industry narratives.
- A thorough competitive landscape assessment covering key enterprise profiles, product portfolio architectures, recent strategic developments, and market concentration patterns, equipping stakeholders with the context needed to evaluate rival behavior and identify partnership or differentiation opportunities.
- An examination of the latest product launches, corporate transfers, and regulatory updates, including the teledyne Dalsa AxCIS expansion and the Mitsubishi Electric business transfer to Miyoshi Electronics, mapped against their anticipated impact on supply continuity, performance benchmarks, and procurement strategy.
- Forward-looking strategic recommendations addressing capacity planning, R&D prioritization, regional market entry, and supply chain resilience, tailored to the distinct needs of component manufacturers, system integrators, and end-user procurement teams.
Translating Market Intelligence into 2026 Outcomes
In a market growing at a 7.2 percent compound annual rate and projected to reach a valuation above 2.5 billion USD by 2032, the margin between reactive planning and strategic foresight is substantial. The decisions made in 2026 will shape product portfolios, supplier relationships, and regional footprint for years to come. Whether the objective is to secure a reliable supply of high-performance contact image sensors, evaluate entry into high-growth inspection verticals, assess the implications of ongoing corporate restructuring, or benchmark competitive positioning against a concentrated group of established leaders, granular intelligence is the prerequisite for execution.
This market research publication removes ambiguity from those decisions. It replaces broad assumptions with verified data, connects technological trajectories to commercial realities, and equips leadership teams with the clarity needed to allocate resources where they will generate the greatest strategic return. To access the full segmentation breakdowns, detailed competitive profiles, regulatory impact analysis, and forward-looking strategic frameworks, we invite you to visit the complete report page. The precise data, scenario models, and actionable insights required to lead in the Contact Image Sensor Market await there.
For detailed analysis of this topic, please visit the official page: Contact Image Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com