

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dimethyl Carbonate Market to Reach USD 2,896 Million by 2032 with 8.1% CAGR

Dimethyl Carbonate Market Outlook 2026–2032: Strategic Imperatives in a High-Growth Specialty Chemical Landscape
The global Dimethyl Carbonate (DMC) market stands at a critical inflection point. As manufacturers, formulators, and supply chain leaders navigate an environment defined by accelerating electrification, tightening environmental regulations, and volatile raw material dynamics, the ability to anticipate structural shifts in demand, pricing, and competitive positioning has never been more consequential. Our newly released market intelligence study provides a rigorous, forward-looking assessment of the DMC industry across the forecast horizon of 2026 through 2032. Designed for executive decision-makers, this report translates historical trajectories, macro-scale projections, and granular competitive intelligence into actionable strategic roadmaps. Rather than offering static snapshots, it equips organizations with the analytical frameworks necessary to allocate capital, secure supply, and position product portfolios ahead of market inflection cycles.
The DMC sector has experienced sustained expansion over the past half-decade, driven by its dual role as a foundational building block in advanced materials and as a high-performance, low-toxicity solvent aligned with modern sustainability mandates. From a base year valuation in 2025, the overall market has advanced to a projected valuation of USD 1,791.63 million in 2026. Looking ahead through the end of the forecast period in 2032, the market is expected to reach USD 2,896.00 million, underpinned by a compound annual growth rate of 8.1%. These figures reflect more than incremental volume gains; they signal a structural reorientation of DMC consumption toward higher-value applications, geographic demand centers, and purity specifications that reward producers capable of scaling with consistency, regulatory compliance, and technical differentiation.
Historical Trajectory and Forecast Architecture (2020–2032)
Understanding where the market is headed requires a clear lens on how it has evolved. The historical period from 2020 to 2025 captures a phase of resilient growth, during which the market moved from a valuation of USD 1,120.00 million in 2020 to USD 1,676.00 million in 2025. This upward trajectory was shaped by expanding polycarbonate synthesis activity, rising adoption of DMC in advanced battery electrolyte formulations, and a broadening pool of industrial and specialty solvent applications. The post-2025 forecast phase reflects a continuation of this momentum, with annual valuations charting a steady ascent through 2032. The compound annual growth rate of 8.1% positions DMC among the more structurally supported specialty chemical segments, where growth is not merely cyclical but anchored in durable end-use demand drivers.
The forecast model is constructed to isolate the pace, direction, and composition of value creation across multiple dimensions. It reconciles baseline macroeconomic assumptions with application-specific consumption patterns, grade-level differentiation, and regional supply-demand balances. Critically, the analysis does not treat the market as a monolith. Instead, it deconstructs growth into the segments that actually matter to commercial strategy: which grades command premium positioning, which applications are expanding fastest in absolute and relative terms, and where regional manufacturing and procurement ecosystems are likely to concentrate or disperse over the next several years.
Market Architecture: Grades, Applications, and Geographies
The DMC market’s growth story is fundamentally segmented. By grade, the landscape is divided among Industrial Grade, Pharmaceutical Grade, and Battery Grade, each serving distinct technical specifications, regulatory requirements, and pricing dynamics. Industrial-grade volumes anchor broad solvent and chemical synthesis usage, while pharmaceutical-grade supplies cater to highly controlled formulation environments that demand stringent purity and auditability. Battery-grade DMC, meanwhile, has emerged as a strategic differentiator, driven by the relentless scaling of lithium-ion electrolyte production and the material requirements of next-generation energy storage systems.
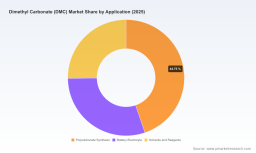
By application, the market draws its revenue composition from three principal demand pillars. Polycarbonate synthesis remains a foundational consumption route, leveraging DMC as a key intermediate in polymer manufacturing. Battery electrolyte applications represent a rapidly scaling demand channel, reflecting the broader electrification trajectory across automotive, consumer electronics, and stationary storage markets. A third application cluster encompasses solvents and reagents, where DMC's favorable toxicological profile and solvent strength continue to drive substitution away from more hazardous alternatives. Each application pathway carries its own throughput characteristics, specification thresholds, and sensitivity to downstream manufacturing cycles, making application-level visibility indispensable for capacity planning and go-to-market strategy.
Geographically, demand is distributed across a diversified set of regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The regional breakdown reflects differing maturity levels, manufacturing footprints, policy environments, and end-use industrial bases. Some regions are characterized by established production infrastructure and mature solvent markets, while others are experiencing accelerated uptake driven by localized manufacturing expansion, energy transition programs, and shifting trade dynamics. Understanding the interplay between regional demand concentration and supply network resilience is central to managing procurement risk and identifying white-space opportunities.
Competitive Landscape and Strategic Positioning
The DMC industry is shaped by a competitive field that spans multinational chemical producers, specialized high-purity material suppliers, and large-scale regional manufacturers. Market concentration remains moderate, with the top three players accounting for approximately 25% of total market value and the top five firms collectively representing around 35%. This level of concentration suggests a market that is neither highly fragmented nor dominated by a handful of incumbents, creating space for differentiated positioning through grade specialization, geographic footprint, technical service, and supply reliability.
Dimethyl Carbonate (DMC) Market
Several key companies illustrate the strategic diversity within the sector. UBE Corporation, headquartered in Tokyo, produces DMC and ethyl methyl carbonate through phosgene and oxidative carbonylation routes, with manufacturing presence that includes a Louisiana facility and operations in Spain and Thailand. Its focus on battery-grade DMC for lithium-ion electrolytes aligns with the growing premiumization of the segment. Lotte Chemical Corporation, based in Seoul, manufactures DMC as a monomer for polycarbonates and specialty chemicals, supplying industrial and battery grades from Korean production sites. Kowa Company, Ltd., operating from Nagoya, develops and supplies DMC across industrial solvent, battery, and pharmaceutical channels, with production and distribution networks spanning Japan and the United States. Kishida Chemical Co., Ltd., based in Osaka, emphasizes high-purity grades produced via transesterification, serving laboratory, industrial, and pharmaceutical applications.
In the high-purity and reagent space, Merck KGaA, headquartered in Darmstadt, supplies DMC as a high-purity solvent and reagent for pharmaceutical and chemical synthesis, with offerings that also extend into battery-electrolyte grade options. On the large-scale production side, Shandong Shida Shenghua Chemical Group Co., Ltd. and Hualu Hengsheng Group Co., Ltd., both operating in Shandong, China, represent substantial manufacturing capacity built on methanol oxidative carbonylation and transesterification pathways, supplying industrial, battery, and pharmaceutical grades with ongoing capacity upgrades. Tokyo Chemical Industry Co., Ltd. (TCI) contributes to the research and industrial grade market with high-purity offerings for synthesis and battery applications, while Dongying City Longxing Chemical Co., Ltd. serves solvent and polycarbonate precursor demand with battery-grade capacity as part of the broader Chinese manufacturing ecosystem.
Recent corporate activity underscores how aggressively firms are positioning themselves for the next phase of demand growth. In February 2026, UBE Corporation initiated groundbreaking and construction for a new DMC and EMC plant in Louisiana, USA, targeting 100,000 tons per year of DMC capacity, with operations planned for the second half of fiscal 2026 to address North American battery and semiconductor demand. Earlier, in November 2025, Jiangsu Sailboat Petrochemical Co., Ltd. collaborated with Asahi Kasei on a new high-purity DMC and ethylene carbonate facility in Lianyungang, China, aimed at increasing battery-grade supply. These developments reflect a broader pattern: capacity additions are increasingly tailored to purity, regional demand proximity, and application-specific requirements rather than undifferentiated volume expansion.
Market Dynamics: Supply, Regulation, and Raw Material Sensitivity
No strategic assessment of the DMC market is complete without examining the external forces that shape cost structures, compliance obligations, and demand elasticity. Raw material dynamics remain a critical lever. Methanol prices in China rose sharply to over USD 400 per ton in March 2026, climbing more than 40% from early March levels amid geopolitical tensions and supply disruptions. Broader Northeast Asian pricing also strengthened, with China FOB prices around USD 425 per metric ton and India FOB prices near USD 807 per metric ton, reflecting tighter supply linked to Middle East disruptions. For producers and downstream buyers alike, methanol cost volatility translates directly into margin pressure, pricing strategy complexity, and inventory timing decisions.
Regulatory and trade developments add further layers of strategic consideration. In July 2025, U.S. Customs and Border Protection issued a ruling classifying Dimethyl Carbonate (CAS No. 616-38-6) from Saudi Arabia, an action with implications for import routing, duty considerations, and sourcing strategy. At the same time, the U.S. EPA continues to reinforce demand for DMC as a low-toxicity green alternative to hazardous solvents under Clean Air Act classifications. This regulatory tailwind supports substitution trends in application segments where environmental compliance, workplace safety, and formulation sustainability are becoming competitive differentiators rather than mere compliance checkboxes.
Lithium Batter Ethylene Carbonate Market
Together, raw material volatility, trade classification developments, and environmental regulation create a market environment in which operational agility matters as much as scale. Producers and buyers must navigate cost pass-through dynamics, ensure continuity of high-purity supply, and align procurement strategies with evolving regulatory expectations. The firms that succeed will be those that treat these dynamics not as isolated risks but as integrated variables in capacity planning, contract structuring, and geographic sourcing.
What the Report Delivers: Actionable Intelligence for Executive Decision-Making
This market research study is designed to move beyond high-level characterization and into the practical judgments that executives, commercial leaders, and strategy teams need to make in 2026 and beyond. The report provides a structured, evidence-based view of the DMC market that supports capital allocation, procurement planning, product portfolio strategy, and competitive benchmarking. It integrates historical performance, forecast trajectories, segment-level analysis, and company-level intelligence into a single decision-support framework.
Readers will find detailed coverage of market sizing and growth modeling across the forecast period, with a clear delineation of how revenue is distributed by grade, application, and region. The analysis includes competitive profiling of the principal participants, examining production routes, grade focus, geographic presence, and recent capacity or partnership developments. It also contextualizes market behavior within the broader environment of raw material pricing, regulatory change, and trade classification actions that influence both supply economics and demand patterns. Importantly, the report connects these observations to strategic implications: where demand is structurally strengthening, which grade and application combinations offer the most compelling value creation potential, and how competitive concentration shapes bargaining power, differentiation opportunities, and market entry considerations.
By presenting a comprehensive but curated view of the market, the study enables organizations to identify where to deepen investment, where to manage exposure, and where to monitor emerging shifts that could alter the competitive landscape. It is built for teams that require more than aggregate market numbers; they need the analytical scaffolding that turns data into informed action.
Strategic Implications for 2026 and Beyond
The DMC market’s projected trajectory offers a compelling case for proactive strategic engagement. With the market expected to advance from a 2026 valuation of USD 1,791.63 million to USD 2,896.00 million by 2032 at a CAGR of 8.1%, the growth runway is substantial, but it is not uniformly distributed. Value creation will increasingly favor participants who can align capacity with grade-specific demand, secure reliable methanol input economics, and position for application-driven growth in polycarbonate synthesis, battery electrolytes, and specialty solvents. Geographic and regulatory diversity will further reward firms that can manage supply chain resilience while capitalizing on sustainability-driven substitution trends.
In this context, the strategic questions facing industry leaders are clear. How should capacity investments be prioritized across industrial, pharmaceutical, and battery grades? Which application segments offer the strongest combination of volume growth and margin resilience? How should procurement and sourcing strategies adapt to methanol price volatility and evolving trade classifications? And where do competitive dynamics create room for differentiation through purity, service, or regional proximity? Answering these questions requires detailed intelligence that connects market structure to operational and commercial decision-making.
Next Steps: Accessing the Full Intelligence Suite
This overview provides a high-level framing of the market environment and the strategic value embedded in our latest DMC market research. It is intended to demonstrate the depth and relevance of the analysis while preserving the detailed segmentations, regional breakdowns, application-level revenue distributions, and company-specific assessments that constitute the full report. For organizations seeking to make precise, evidence-based decisions in 2026, the complete study offers the granularity required to translate macro trends into executable strategy.
To access the full market sizing across segments, detailed forecast tables, competitive profiles, and the complete analysis of market dynamics and strategic implications, visit the full report page. The complete intelligence suite is structured to support executive review, commercial planning, and investment evaluation with the specificity that contemporary DMC market decisions demand.
For detailed analysis of this topic, please visit the official page: Dimethyl Carbonate (DMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com