

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microducts Market Hits $4.84B in 2025, Projected 11.3% CAGR Through 2032

Microducts Market Strategic Outlook 2026: Navigating the Next Wave of Fiber Infrastructure Investment
The global telecommunications landscape is undergoing a structural transformation driven by accelerating bandwidth demand, the maturation of fiber-to-the-x (FTTX) architectures, and the relentless push toward low-latency, high-density connectivity. At the heart of this transition lies a critical yet often underestimated physical layer component: microducts. As network operators, infrastructure investors, and municipal planners confront the operational realities of hyperscale fiber deployment, the microducts market has evolved from a commoditized conduit segment into a strategically differentiated infrastructure category. Our latest market research delivers a comprehensive, data-grounded assessment of this sector, offering enterprise decision-makers a clear line of sight into the forces that will shape capital allocation, supply chain strategy, and competitive positioning through 2032.
This briefing serves as a strategic preview of that research. It outlines the macro trajectory of the market, dissects the operational and regulatory dynamics currently reshaping competitive behavior, and demonstrates why forward-looking organizations are treating microduct infrastructure intelligence as a core component of their 2026 planning cycles. What follows is designed to establish analytical credibility while pointing toward the full report as the definitive source for actionable intelligence.
Microducts Market
Market Trajectory and the Strategic Imperative for 2026
The microducts market has demonstrated consistent, compounding growth over the past half-decade, transitioning from an estimated 2.82 billion USD in 2020 to approximately 4.84 billion USD by 2025. This trajectory reflects more than incremental demand; it signals a structural expansion in how fiber networks are architected, deployed, and scaled. Looking ahead, the market is projected to surpass the 5.5 billion USD threshold in 2026, with growth momentum carrying the sector toward the 10 billion USD mark by 2032. The intervening years will be characterized by an 11.3 percent compound annual growth rate, a figure that underscores the velocity at which fiber infrastructure investment is translating into tangible demand for precision-engineered microduct systems.
For enterprise strategists, these numbers carry a deeper implication. The growth curve is not linear across all deployment contexts, nor is it evenly distributed across product architectures or geographic markets. Rather, it reveals a market in which certain network topologies, installation methodologies, and material specifications are capturing disproportionate share. Understanding where growth concentrates, why it concentrates there, and how leading operators are positioning themselves to capture it requires more than top-line forecasting. It demands a granular, scenario-aware analysis that maps demand drivers to supply-side capabilities, regulatory constraints, and technological maturity curves.
Our research framework integrates historical performance data with forward-looking modeling to isolate the inflection points that will matter most to 2026 decision-makers. By examining the interplay between network architecture evolution, material cost dynamics, and deployment standardization, the study provides a structured basis for evaluating market entry timing, capacity investment, procurement strategy, and partnership alignment. The objective is not simply to report where the market is heading, but to equip leaders with the analytical scaffolding necessary to act before competitive advantages solidify.
Competitive Positioning and the Reshaping of the Vendor Landscape
The microducts market is defined by a moderately concentrated competitive environment, with a small cohort of established manufacturers commanding a meaningful share of global supply. This concentration does not imply market rigidity. On the contrary, recent developments reveal a landscape marked by targeted capacity expansion, certification-driven differentiation, and strategic collaboration aimed at hardening end-to-end fiber delivery pathways.
Leading players are pursuing competing strategies that reflect divergent interpretations of where value will accrue. Some manufacturers are doubling down on specialized microduct architectures, emphasizing blown fiber compatibility, multi-duct bundling efficiency, and flame-retardant performance for indoor and multi-dwelling unit applications. Others are scaling production capabilities to support broadband expansion initiatives, while a subset of industry participants are forging partnerships that bridge microduct supply with hardened connectivity solutions and network extension frameworks. The result is a market in which product specification, installation methodology, and certification compliance are becoming as strategically consequential as unit cost.
Recent operational milestones illustrate this dynamic with precision. Capacity expansions have been announced to accommodate additional production lines for microduct and microduct bundle manufacturing, signaling confidence in sustained European and regional broadband demand. Certification achievements have reinforced the credibility of micro-trenching and direct installation methodologies, validating microduct systems as viable components of high-visibility infrastructure projects. Facility upgrades have highlighted the deployment of next-generation multi-production configurations aligned with broadband rollout targets, while strategic partnerships have begun to integrate blowable fiber optic micro-cable solutions into hardened connectivity ecosystems. Simultaneously, upstream procurement frameworks between major network operators and fiber suppliers have extended multi-year agreements that indirectly reinforce demand visibility for microduct infrastructure.
These developments matter because they reveal a market in which competitive advantage is increasingly derived from operational readiness, specification alignment, and ecosystem integration rather than scale alone. Our analysis maps these strategic moves against market concentration metrics, regional deployment patterns, and application-specific demand profiles to identify where vendor positioning is likely to translate into durable share gains. The full report examines these dynamics in depth, providing a structured competitive assessment that enables buyers, investors, and operators to evaluate supplier reliability, innovation trajectories, and long-term strategic fit.
Regulatory, Material, and Operational Dynamics Influencing Procurement and Deployment
No strategic assessment of the microducts market is complete without acknowledging the regulatory and input-cost environment that governs what can be deployed, where it can be installed, and at what marginal cost. The intersection of standards compliance, material availability, and logistical friction is actively reshaping procurement behavior across the value chain.
On the standards front, industry certification frameworks continue to serve as gatekeepers for installation approvals, particularly in contexts requiring fire-rated performance or outdoor durability. Building codes across the European Union and North America are increasingly mandating flame-retardant microduct variants for indoor and multi-dwelling installations, elevating material specification from a technical preference to a compliance requirement. Concurrently, technical standards governing microduct diameters and microcable blowability are defining the practical parameters for fiber-to-the-home deployments, constraining design flexibility while simultaneously reducing deployment variability. These regulatory and technical anchors create a predictable baseline for procurement but also raise the stakes for manufacturers that must align product portfolios with evolving approval pathways.
Material dynamics introduce a parallel layer of strategic complexity. HDPE remains the primary feedstock for microduct production, and volatility in HDPE pricing has placed margin pressure on manufacturers operating amid ongoing geopolitical oil supply dynamics. Upstream resin logistics and geopolitical factors have translated into effective cost increases for HDPE microduct grades, compressing the margin between raw material expenditure and finished product pricing. In this environment, procurement strategies that rely solely on historical cost assumptions risk underpricing projects or overcommitting to fixed-price contracts without adequate exposure management.
These forces do not operate in isolation. Regulatory specification requirements interact with material cost trajectories to influence which product types become preferred in specific deployment scenarios. Installation methodologies that minimize civil works exposure may gain favor in cost-sensitive environments, while standardized microduct diameters and certified flame-retardant variants may become default choices where compliance risk outweighs marginal savings. Our research integrates these dynamics into a unified operating context, enabling stakeholders to evaluate how regulatory compliance, feedstock volatility, and logistical surcharges will shape total cost of ownership, supplier selection, and deployment scheduling through the forecast period.
Pre-Wired Conduits Market
What the Full Research Delivers for Enterprise Decision-Makers
The macro trajectory, competitive movements, and regulatory and material dynamics outlined above constitute only the surface layer of the market environment. Translating this context into executable strategy requires a deeper, more structured intelligence layer—one that connects demand segmentation, application-specific adoption patterns, product-type preferences, and regional deployment intensity to the operational decisions facing leadership teams in 2026.
The complete research study is designed to serve that function. It moves beyond aggregate forecasting to provide a multidimensional assessment of the microducts market, linking historical performance data with forward-looking modeling across the forecast horizon. The analysis examines how demand propagates across network architecture types, how product architectures align with installation methodologies, and how application contexts differentiate growth velocity and margin profiles. It also situates vendor behavior within a competitive framework that accounts for market concentration, strategic partnerships, certification milestones, and capacity investments, offering a structured basis for evaluating supplier resilience and long-term positioning.
Equally important, the study embeds market dynamics into practical decision-support frameworks. Procurement teams can use the analysis to benchmark supplier landscapes, anticipate specification shifts, and model cost exposure under varying material and logistics scenarios. Network planners and infrastructure investors can leverage the segmentation analysis to identify where deployment intensity, regulatory pressure, and product-fit alignment are most likely to generate durable demand. Strategic leaders can draw on the competitive and dynamic assessments to time market entries, structure partnerships, and calibrate capacity commitments in a way that balances growth opportunity against cost uncertainty.
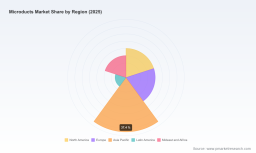
Accessing the full report provides the granularity necessary to convert high-level market awareness into targeted action. The detailed segmentation analysis, the application- and product-type breakdowns, and the regional demand distributions are presented with the precision required for operational planning and investment evaluation. These elements are intentionally developed to support scenario testing, supplier comparison, and procurement calibration, ensuring that decision-makers can move from strategic intent to execution with confidence.
Conclusion: Why 2026 Demands Precision Intelligence
The microducts market is entering a phase in which growth is no longer the only metric that matters. The strategic question for 2026 is how to capture that growth efficiently, compliantly, and with a supply chain and partner ecosystem capable of sustaining deployment velocity amid material volatility and specification evolution. The companies that will navigate this environment most effectively are those that treat microduct infrastructure not as a passive procurement category but as a strategically managed layer of the broader fiber architecture.
Our research was constructed to support precisely that shift in mindset. By integrating historical trajectory, competitive behavior, regulatory and material dynamics, and forward-looking growth modeling, the study provides a coherent intelligence foundation for enterprise decision-makers seeking to align investment, procurement, and deployment strategies with market reality. The aggregate figures referenced here establish the scale and direction of the opportunity. The full report delivers the segmentation depth, competitive detail, and operational context needed to act on it.
For leaders preparing 2026 capital plans, supplier evaluations, and deployment roadmaps, the distinction between high-level awareness and actionable intelligence will define execution quality. The complete market research closes that gap, transforming macro momentum into structured, decision-ready insight.
For detailed analysis of this topic, please visit the official page: Microducts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com