

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Slewing Bearings Market to Reach $652.66 Million by 2032 with 5.95% CAGR

Navigating the Turn: Strategic Insights into the 2026 Slewing Bearings Market
Executive Overview
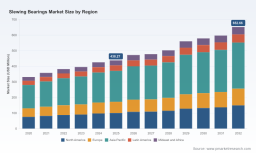
The global slewing bearings market stands at a critical inflection point. Between 2020 and 2025, the industry demonstrated remarkable resilience, expanding from a revenue base of 331.45 million USD to 438.27 million USD. This historical trajectory underscores a consistent demand cycle driven by heavy infrastructure investment and the modernization of industrial machinery. As we project forward into the forecast period of 2026 through 2032, the market is poised to reach a valuation of 652.66 million USD by the end of the decade.
For enterprise leaders and procurement strategists, understanding this growth curve is not merely about tracking revenue; it is about anticipating supply chain constraints, technological shifts, and competitive realignments. The Compound Annual Growth Rate (CAGR) indicating a steady expansion at approximately 5.95 percent suggests a mature yet evolving landscape. This article serves as a strategic primer, drawing from the comprehensive PW Consulting Slewing Bearings Market Research, to highlight the operational realities defining the 2026 business environment.
Macroeconomic Trajectory and Growth Drivers
The market expansion from 2020 to 2025 was characterized by steady volume increases across key industrial sectors. The revenue progression from 358.19 million USD in 2021 to 395.93 million USD in 2023 highlights the post-pandemic recovery velocity. By 2026, the market is expected to breach the 472.72 million USD threshold. This growth is not linear but is propelled by specific macroeconomic engines that require nuanced understanding.
Primary growth vectors include the ongoing transition in energy infrastructure and the persistent need for heavy lifting solutions in construction and mining. However, the forecast period from 2027 to 2032 reveals an acceleration in value accumulation. The jump from 478.24 million USD in 2027 to 560.44 million USD in 2029 indicates that market maturity is bringing higher value density per unit, rather than just volume growth. Strategic planners must note that while the top-line revenue is expanding, the underlying cost structures are facing significant pressure from raw material volatility.
The reliance on steel-intensive manufacturing means that fluctuations in alloy steel such as 42CrMo directly impact manufacturing costs and fatigue life of the raceway. Industry market data from mid-2026 suggests that these material constraints are compressing profit margins for slewing bearing manufacturers. Consequently, the revenue figures reported in market sizing must be interpreted alongside margin analysis to understand true profitability potential in the coming years.
Segmentation Dynamics: Type and Application
The market structure is defined by distinct technological and application-based segments. In terms of product typology, the landscape is bifurcated between Roller Slewing Bearings and Ball Slewing Bearings, with a smaller portion occupied by other specialized types. The Roller segment continues to hold significant share due to its load-bearing capabilities in heavy machinery, while the Ball segment remains critical for precision applications requiring lower friction and higher rotational speeds.
Application-wise, the demand is diversified but concentrated in high-capital sectors. Renewable Energy remains a pivotal driver, reflecting the global push toward wind turbine installation and maintenance where slewing bearings are integral to yaw and pitch systems. Construction and Transit Equipment follows closely, driven by excavators, cranes, and tunneling machinery. Industrial Machinery and Mining sectors contribute substantial volumes, while miscellaneous applications round out the portfolio.
It is crucial for strategy teams to recognize that these segments do not grow in isolation. The interplay between renewable energy installation cycles and construction equipment demand creates complex demand forecasting challenges. A detailed breakdown of how these segments interact, including specific volume contributions and regional variances, is essential for accurate budgeting and capacity planning. Readers seeking precise segmentation splits and application-specific revenue breakdowns are advised to consult the full market intelligence report to avoid strategic misalignment.
Competitive Landscape and Key Players
The market concentration metrics indicate a moderately fragmented environment. The CR3 stands at 24.6 percent, and the CR5 extends to 32.1 percent. This suggests that while key multinational corporations hold significant influence, there is ample room for specialized players and regional manufacturers to compete on customization and price.
Prominent entities shaping the competitive terrain include SKF, headquartered in Göteborg, Sweden. As a manufacturer of standard and customized slewing bearings with outside diameters ranging from 0.1 to 18 m, SKF sets a benchmark for precision and scale. Similarly, Kaydon Bearings, based in Muskegon, Michigan, USA, supplies slewing ring bearings and thin section bearings, including specific solutions for wind energy applications.
Thyssenkrupp Rothe Erde, operating out of Germany, remains a global leader in large-diameter slewing bearings up to 25,000 mm, with facilities spanning Asia, Europe, and the Americas. Their recent operational updates, including plans to consolidate operations to Aurora in 2026, signal strategic shifts in manufacturing footprints that could affect supply chain reliability in North America.
Other notable participants include Scheerer Bearing Corporation in Willow Grove, Pennsylvania, known for high-quality slewing ring bearings and drives. SlewPro, based in Hudson, Massachusetts, focuses on precision custom slewing rings, drives, and gears for U.S. OEMs, highlighting the niche for localized customization. TGB Group in Italy leads in high-quality slewing rings for demanding environments, while Silverthin Bearing Group in Preston, Washington, produces precision thin section and slewing ring bearings for aerospace, robotics, and industrial uses.
In the Asia-Pacific region, LDB Bearing in Luoyang, Henan, China, manufactures slewing bearings, slew drives, and gears for heavy machinery and cranes. Fenghe Slewing Bearing operates as a custom OEM/ODM manufacturer, often replacing SKF and Kaydon equivalents, while QCB in the United Kingdom supplies slewing rings, drives, and thin section bearings with diameters from 100 mm to over 10,000 mm.
The competitive dynamics are further fluidified by recent corporate activities. In July 2025, Silverthin Bearing Group released a new comprehensive catalog for thin section and slewing ring bearings targeting space, aerospace, defense, robotics, medical, oil and gas, and semiconductor industries. This expansion into high-tech sectors diversifies their revenue base beyond traditional industrial uses. Meanwhile, Xuzhou Wanda Slewing Bearing Co., Ltd. exhibited slewing bearings and drives at CONEXPO-CON-AGG 2026 in Las Vegas, signaling aggressive market penetration in the construction sector. LDB Bearing also joined as an exhibitor at bauma CONEXPO INDIA 2026, reinforcing the commitment of Chinese manufacturers to global trade shows and direct customer engagement.
Understanding the specific strengths, weaknesses, and strategic moves of each competitor is vital for positioning. The full market report provides a detailed competitive benchmarking analysis that goes beyond company profiles to assess market share dynamics and strategic maneuvering.
Regulatory and Operational Dynamics
The operational environment for slewing bearings is increasingly shaped by regulatory frameworks and technical standards. A significant development occurred in June 2026 with the introduction of ISO 16123:2025. This standard specifies design, manufacture, and acceptance requirements for slewing bearings in marine cranes at ambient temperatures not lower than −40 °C. Compliance with this standard is becoming a prerequisite for bidding on offshore and marine construction contracts, effectively raising the barrier to entry for manufacturers not equipped for extreme condition engineering.
Simultaneously, the European Union introduced new guidelines to ensure the sustainability of bearing manufacturing processes. These guidelines emphasize reduced carbon footprints and enhanced recycling practices. For global suppliers, this means that sourcing strategies and production methodologies in Europe must align with stricter environmental compliance, potentially increasing operational costs but also creating differentiation opportunities for early adopters of green manufacturing.
Raw material dynamics remain a persistent headwind. The fluctuation in costs of specialty steel and rare earth elements poses a substantial restraint on production. As previously noted, slewing bearings are steel-intensive, with fluctuations in alloy steel such as 42CrMo directly impacting manufacturing costs and fatigue life of the raceway. Supply chain managers must develop hedging strategies or long-term supplier contracts to mitigate these risks. The market report offers a deep dive into cost structure analysis and raw material trend forecasting to assist in these mitigation efforts.
External Tooth Slewing Bearing Market
Strategic Implications for 2026 Decision Makers
As we navigate 2026, the slewing bearings market offers both opportunities and challenges that require decisive action. The growth trajectory toward 652.66 million USD by 2032 is clear, but the path to capturing value within that growth is complex. Decision makers must evaluate their supply chain resilience against raw material volatility. They must assess their compliance readiness regarding ISO 16123:2025 and EU sustainability guidelines. Furthermore, they must analyze their competitive positioning relative to giants like Thyssenkrupp Rothe Erde and specialized players like Silverthin or SlewPro.
The consolidation of operations by key players, such as the relocation plans announced by thyssenkrupp rothe erde USA in May 2026, indicates a shift in logistics and distribution networks. Procurement teams need to anticipate how these geographic shifts will impact lead times and delivery reliability for North American operations.
For investors and strategic planners, the moderate market concentration (CR5 at 32.1 percent) suggests that M&A activity or strategic partnerships could reshape the landscape. Acquiring niche capabilities in thin section bearings or expanding into high-growth applications like renewable energy could yield significant returns. However, without granular data on segment profitability and regional growth rates, such moves carry risk.
This article has highlighted the macro trends, competitive players, and regulatory shifts defining the current market. However, the depth of insight required to formulate a winning strategy demands more than surface-level trends. The PW Consulting Slewing Bearings Market Research provides the actionable data needed to navigate these complexities, including detailed segmentation analysis, regional revenue splits, and comprehensive company profiling.
To secure your organization's position in this evolving market, access to precise intelligence is paramount. We invite you to explore the full report for complete segmentation data, detailed competitive analysis, and strategic forecasts that will inform your 2026 and beyond planning.
Slewing Bearings Market
For detailed analysis of this topic, please visit the official page: Slewing Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com