

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biologics & Biosimilars Market Hits $527.36B in 2025, Projected 10.42% CAGR to 2032

Navigating the Biologics and Biosimilars Market: Strategic Intelligence for 2026 and Beyond
The global biologics and biosimilars landscape is undergoing a structural transformation that demands immediate and informed strategic attention. As biosimilar adoption accelerates across developed and emerging healthcare systems, organizations that fail to anticipate regulatory shifts, manufacturing bottlenecks, and reimbursement realignments risk ceding competitive ground to agile entrants. Our newly released research framework maps this trajectory with precision, delivering an operational blueprint for executives navigating pricing pressure, portfolio optimization, and geographic expansion.
The market has demonstrated consistent momentum over the past half-decade, having moved from a baseline of 321.27 billion USD in 2020 to an estimated valuation of 527.36 billion USD in 2025. Forecasts indicate sustained expansion through 2032, with the trajectory expected to reach 1.055 trillion USD by the final year of the projection window. Crucially, the compound annual growth rate for this interval stands at 10.42 percent, reflecting not merely incremental uptake but a fundamental restructuring of how therapeutic proteins and their follow-on counterparts are adopted, reimbursed, and manufactured at scale. For corporate leadership teams evaluating 2026 budgeting, capacity investments, and partnership strategies, these figures are not abstract benchmarks. They signal an environment where speed-to-market, regulatory navigation, and supply chain resilience will separate market leaders from reactive followers.
Why 2026 Requires a Strategic Overhaul
Corporate planning cycles traditionally treat biologics and biosimilars through a narrow commercial lens, yet the coming year will expose structural fault lines across the value chain. Reimbursement models continue to lag inflationary pressures, with hospital networks facing mounting underpayments that constrain procurement flexibility and shift negotiation leverage toward manufacturers who can demonstrate consistent quality and reliable supply. Simultaneously, regulatory pathways are being recalibrated to reduce development friction while preserving safety standards. The cumulative effect is a market where pricing architecture, interchangeability designations, and manufacturing scalability become equally decisive. Organizations that continue relying on legacy portfolio assumptions will find themselves misaligned with procurement priorities, payer expectations, and competitive entry timing.
Rather than treating this environment as a series of isolated challenges, executive teams need an integrated view of how approval cadence, international sourcing dependencies, input cost volatility, and regional demand patterns intersect. Recent market intelligence confirms that biosimilar adoption remains constrained relative to therapeutic spending, with approved follow-on products representing a substantial share of total pharmaceutical expenditure while capturing a smaller portion of actual utilization. This gap is not an anomaly; it reflects payer hesitation, formulary optimization cycles, and the operational complexity of switching protocols. Understanding where that gap closes first, and which therapeutic categories unlock faster uptake, will shape marketing authorization strategies, manufacturing commitments, and commercial launch sequencing throughout 2026.
What the Research Delivers
Our Biologics and Biosimilars Market study was designed to convert macro trends into executable decision support. Rather than offering high-level commentary, the analysis is structured around the operational variables that procurement, regulatory, and commercial teams encounter daily. The report integrates historical performance data from 2020 through the current base year with a forward-looking forecast spanning 2026 to 2032, enabling scenario modeling that accounts for approval timing, regional reimbursement evolution, and manufacturing cost dynamics.
Readers will find a coordinated set of analytical modules that address:
- Comprehensive market sizing and trajectory mapping, anchored to verified historical baselines and calibrated forecast intervals that support capital allocation and capacity planning
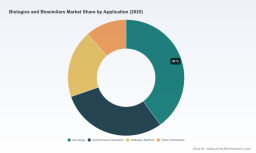
- Structural segmentation analysis across therapeutic classes and application categories, allowing portfolio teams to identify concentration risks, growth pockets, and substitution exposure
- Regional demand mapping that contextualizes procurement patterns, payer behavior, and market entry timing without relying on superficial geographic snapshots
- Competitive benchmarking against established multinational manufacturers and specialized biosimilar developers, including product portfolio reach, approval momentum, and commercialization infrastructure
- Supply chain and manufacturing risk assessment, covering single-use system dependencies, active pharmaceutical ingredient sourcing exposure, and cost sensitivity under shifting trade conditions
- Regulatory and reimbursement dynamics, including recent designation changes, guidance simplifications, and the operational impact of approval cadence on interchangeable product development
- Strategic scenario frameworks that translate data into prioritization logic for launch sequencing, partnership evaluation, and market access planning
Each section is built to answer a practical question: where should resources be deployed, which therapeutic categories warrant accelerated development or licensing focus, and how should organizations position manufacturing and distribution assets to buffer against input cost volatility? The intent is to provide decision-makers with a structured reference point that can be integrated directly into annual planning, risk assessments, and partnership diligence.
Competitive Landscape: Who Is Moving and Why
The current competitive environment is defined by a blend of scaled multinational portfolios and focused biosimilar specialists. Several organizations have built substantial follow-on biologics pipelines, while others are leveraging recent approvals to accelerate commercialization in therapeutic areas where originator exposure remains high. Amgen continues to expand its biosimilar footprint with commercialized products spanning oncology and bone metabolism indications, reflecting a deliberate strategy to convert portfolio depth into recurring commercial value. Pfizer has reinforced its presence through operational growth in select biosimilar categories, supported by manufacturing infrastructure designed to sustain launch velocity and supply reliability.
Sandoz has maintained its positioning as a dedicated follow-on biologics leader, advancing multiple approvals and launch activities that reinforce its focus on high-quality biosimilar development. Celltrion is executing a broader expansion plan that extends its biosimilar product roadmap through the late 2030s, complemented by recent U.S. facility activation and product introductions that broaden market access. Biocon Biologics has strengthened its commercialization base with multiple approved biosimilars and recent regulatory clearances, while Alvotech is pushing forward with biosimilar programs targeting high-spend immunology assets and has advanced recent approvals and launch activity.
Specialized developers are also shaping competitive dynamics. Formycon has concentrated on ophthalmology biosimilars with multiple FDA-approved candidates and recent launch milestones. Samsung Bioepis continues to build a diversified approval portfolio, leveraging U.S. commercialization partnerships to extend reach for recent denosumab and other biosimilar introductions. Fresenius Kabi has integrated biosimilar offerings into broader therapeutic portfolios, with ongoing regulatory activity supporting oncology and inflammatory treatment options. Together, these organizations illustrate a market where differentiation emerges not only from approval count but from manufacturing readiness, interchangeability strategy, and the ability to convert approvals into durable commercial execution.
Regulatory and Reimbursement Pressures Reshaping Market Behavior
Regulatory evolution remains one of the most influential forces guiding biosimilar development and adoption. Recent guidance efforts have aimed to simplify biosimilarity study requirements and reduce development friction for interchangeable designations, signaling a regulatory posture that favors faster pathway execution without compromising evaluation rigor. Approval activity has reflected this direction, with multiple biosimilar products receiving clearance across therapeutic indications during recent months, including developments in immunology, ophthalmology, and bone metabolism categories.
These approval patterns matter because they influence formulary inclusion speed, switching confidence, and procurement planning. Yet regulatory clearance alone does not guarantee market penetration. Payer and hospital economics remain under strain, with reimbursement structures for biologics trailing inflationary cost movements. This mismatch complicates commercialization for manufacturers and creates procurement uncertainty for providers, especially when biosimilar substitution requires coordinated clinical workflows and contracting adjustments. Organizations that account for these reimbursement constraints in their launch planning will be better positioned to align pricing, contracting, and market access support with the realities of institutional buying behavior.
Supply Chain Realities and Cost Dynamics
Behind the approval headlines lies a supply environment that directly shapes margin durability and supply reliability. Biologics manufacturing remains highly dependent on international sourcing, with active pharmaceutical ingredients increasingly concentrated across a limited number of geographies. Sterile injectable production is similarly exposed to concentrated manufacturing bases, creating structural sensitivity to logistics disruption, quality audits, and sourcing continuity. These dependencies are not abstract procurement concerns. They influence production scheduling, inventory strategy, and the ability to meet launch demand without compromising consistency.
Worldwide Aflibercept Biosimilars Market
Compounding these structural dependencies are cost pressures tied to input inflation and trade policy. Recent analysis indicates that tariff exposure on single-use systems and related manufacturing inputs has raised production costs for monoclonal antibody batch operations, with meaningful impact at commercial scale. For organizations planning capacity expansion or new product introductions, this implies that cost modeling must incorporate not only direct manufacturing expenses but also scenario sensitivity around input availability, logistics friction, and regional sourcing diversification. Companies that treat supply chain resilience as a secondary operational concern will face greater exposure when launching products that rely on consistent batch output and predictable cost structures.
How to Use This Research for 2026 Decision-Making
The strategic value of this research lies in its ability to convert broad market signals into prioritized action. Leaders can use the analysis to:
Biologics and Biosimilars Market
- Evaluate portfolio exposure across therapeutic categories and identify where interchangeability, approval momentum, and payer readiness intersect most favorably
- Stress-test manufacturing and sourcing strategies against input cost sensitivity and international dependency risks
- Map competitive entry timing and approval cadence to anticipate substitution pressure and adjust pricing or contracting assumptions accordingly
- Align commercial launch planning with regional procurement patterns and reimbursement conditions rather than relying on generic adoption curves
- Support partnership and licensing decisions with competitive benchmarking that reflects both portfolio breadth and execution capability
For organizations managing multiple development programs or planning biosimilar market entry, the study provides a structured reference for balancing speed, quality, and commercial feasibility. For established manufacturers, it offers a framework for assessing where portfolio reinforcement, regional expansion, or supply chain diversification will yield the strongest return under current market conditions.
Conclusion
The biologics and biosimilars market is entering a phase where growth is no longer the only metric that matters. Execution quality, regulatory alignment, reimbursement navigation, and supply chain discipline will determine which organizations convert market expansion into durable competitive advantage. The trajectory projected through 2032 reflects substantial opportunity, but realizing that opportunity requires decision-making grounded in detailed market intelligence rather than generalized industry narratives.
Our full Biologics and Biosimilars Market research report extends far beyond the strategic overview presented here. It delivers the complete dataset, segmentation analysis, competitive benchmarking, regulatory tracking, and scenario frameworks required to support confident planning across 2026 and the forecast period ahead. For executive teams, procurement leaders, and commercial strategists seeking to move from observation to action, the complete study provides the depth necessary to translate market momentum into measured, defensible decisions.
For detailed analysis of this topic, please visit the official page: Biologics and Biosimilars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com