

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sterile Medical Packaging Market Hits $501M in 2025, Projects 7.65% CAGR to 2032

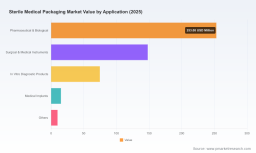
Strategic Imperatives in the Sterile Medical Packaging Market: Navigating Growth Amid Regulatory Precision and Material Innovation
The global healthcare ecosystem depends on an often-overlooked foundation: sterile medical packaging. As therapeutic modalities grow increasingly complex and supply chains stretch across continents, the integrity of packaging has become inseparable from patient safety, regulatory compliance, and commercial viability. Our newly released market research offers a comprehensive, forward-looking blueprint for executives, procurement leaders, and strategic planners who must navigate the sterile medical packaging landscape through the end of the decade. This briefing outlines the macro trajectory, competitive architecture, regulatory currents, and operational imperatives that will define portfolio strategy, capital allocation, and risk management from 2026 onward.
Plastic Medical Packaging Market
Over the past half-decade, the sector has demonstrated steady, resilient expansion, with the overall market advancing from approximately 350.0 million USD in 2020 to an estimated 501.01 million USD in 2025. Looking ahead, the forecast period through 2032 points to continued momentum, with the market projected to reach 834.21 million USD by the terminal year of the analysis window. The implied compound annual growth rate of 7.65 percent underscores a structurally healthy demand environment, driven by aging demographics, expanding surgical volumes, and accelerating adoption of single-use sterile systems. Yet historical growth alone does not dictate strategic advantage. The real opportunity—and the real risk—lies in how organizations interpret shifting regulatory baselines, material cost dynamics, and the concentration of market power while positioning themselves for sustained, defensible performance.
Sterile Medical Packaging Market
Mapping the 2026–2032 Trajectory: What the Numbers Mean for Executive Decision-Making
A 7.65 percent CAGR is not a uniform tailwind. It is a directional signal that rewards segmentation discipline, regional prioritization, and modality-specific packaging engineering. The transition from 501.01 million USD in the base year to a projected 550.33 million USD in 2026 may appear incremental on a spreadsheet, but it reflects a market in which volume growth, premiumization of barrier solutions, and substitution toward higher-performance materials are occurring simultaneously. Organizations that treat the forecast as a single aggregate figure risk misallocating R&D resources, misreading capacity needs, and underpricing contractual commitments. The strategic value of our research lies in its ability to translate this aggregate trajectory into actionable decision layers: where demand is structurally hardening, which application verticals are reshaping supplier requirements, and how geographic exposure should inform localized compliance and distribution footprints. Readers who access the full dataset will find granular breakdowns that enable scenario planning rather than deterministic assumptions.
Competitive Architecture: Concentration, Differentiation, and the Real Source of Advantage
The sterile medical packaging sector remains moderately concentrated, with the top three players collectively commanding roughly a quarter of total revenue and the top five approaching just under 29 percent. This concentration level signals a market where scale, proprietary material science, and entrenched customer relationships matter, yet it also leaves substantial room for specialized suppliers, regional specialists, and agile innovators to capture niche share. The competitive field includes globally recognized suppliers with deep engineering heritage and vertically aligned service models. Amcor, headquartered in Zürich, has built a formidable reputation in thermoformed trays and flexible sterile packaging, consistently emphasizing responsible healthcare solutions that align with sustainability mandates. DuPont de Nemours, based in Wilmington, continues to anchor a significant portion of the flexible barrier market through its Tyvek materials portfolio, supplying sterile pouches, header bags, and lids that are closely associated with medical device protection. West Pharmaceutical Services, operating from Exton, serves the sterile injectable value chain with components and delivery systems designed for rigorous aseptic standards. Sonoco, from Hartsville, provides both rigid and flexible paper-based and composite solutions, while Gerresheimer, headquartered in Düsseldorf, remains a critical voice in glass and plastic primary packaging for sterile pharmaceuticals and medical devices.
The competitive landscape extends well beyond these anchor players. BillerudKorsnäs, based in Stockholm, produces medical-grade paper and paperboard tailored to sterile packaging requirements. Placon, in Oshkosh, specializes in thermoformed medical trays and sterile packaging solutions, and recently expanded its offerings with new lightweight tray designs featuring improved barrier properties. Nelipak Healthcare Packaging, from Fort Worth, provides flexible and rigid sterile packaging for high-volume healthcare applications. Steripack, headquartered in Dublin, focuses on custom sterile medical packaging solutions, and Constantia Flexibles, in Vienna, continues to scale flexible packaging options for sterile medical and pharmaceutical needs. Together, these organizations illustrate a market defined not simply by size but by differentiated capability sets: barrier engineering, thermoforming expertise, glass formulation, paperboard performance, and regulatory documentation fluency. The full competitive analysis in our report examines positioning, strategic overlap, capacity implications, and the evolving tactics that separate market share retainers from share expanders.
Regulatory Density and the Compliance Premium
Few industries operate under a regulatory cadence as intense as sterile medical packaging. In 2026, the compliance environment is tightening across multiple jurisdictions simultaneously, transforming what was once a technical specification exercise into a strategic governance function. The U.S. FDA updated its recognition of ISO 11607-1, referencing the second edition of 2019 with Amendment 1:2023 as the standard for packaging of terminally sterilized medical devices, with full compliance required by December 2026. This timeline is not distant; it dictates near-term testing protocols, validation cascades, and supplier qualification programs for any organization involved in sterile device packaging. Simultaneously, the EU Packaging and Packaging Waste Regulation entered into force in February 2025, establishing a clear architectural shift: all packaging must be recyclable by 2030, with recycled content requirements beginning in 2026 and eco-modulated extended producer responsibility fees applied to producers. For sterile medical packaging suppliers, this means that recyclability is no longer a sustainability aspiration but a design constraint with direct cost implications.
In the United States, the Quality Management System Regulation alignment requirement, which mandates full compliance by February 2026 and aligns with ISO 13485:2016, has further elevated the baseline for quality documentation, traceability, and manufacturing control across sterile packaging operations. Meanwhile, as of March 2026, seven U.S. states—California, Colorado, Maine, Maryland, Minnesota, Oregon, and Washington—have active packaging extended producer responsibility programs that tie producer fees to recyclability and recycled content levels. These state-level frameworks increasingly influence sourcing decisions, especially for suppliers operating across multiple jurisdictions or serving multi-state device manufacturers. The strategic implication is clear: regulatory literacy is now a competitive asset. Organizations that treat compliance as a back-office checklist will face escalating cost leakage and customer qualification friction. Our report maps these overlapping obligations into a practical compliance architecture, helping decision-makers anticipate validation timelines, packaging design constraints, and cross-border regulatory exposure.
Material Economics and the Cost Discipline of Sterile Design
Sterile packaging performance is inseparable from material economics. Barrier integrity, sterilization compatibility, durability during logistics, and compatibility with automated filling lines all depend on raw material behavior, yet pricing volatility can quietly erode margins even when demand remains robust. In April 2026, the Producer Price Index for plastics packaging film and sheet manufacturing stood at 193.699, reflecting sustained pressure on resin and film inputs. This figure is more than a macroeconomic marker; it signals the ongoing operational reality for packaging manufacturers who must balance barrier reliability with cost control. At the same time, material innovation continues to reshape the value proposition. The recent introduction of new lightweight thermoformed tray designs with improved barrier properties illustrates how engineering sophistication can mitigate input cost exposure while enhancing product protection. Similarly, Gerresheimer’s presentation of sustainable flint and amber glass packaging solutions for medical and nutraceutical applications at BIOFACH 2026 highlights the broader industry movement toward material responsibility without sacrificing performance. Our research examines how material choice interacts with sterilization modality, device sensitivity, shelf-life requirements, and recyclability expectations, giving executives a structured lens for evaluating substrate strategies rather than reacting to spot price movements alone.
The Strategic Architecture of the Report
This study is designed for leaders who need to convert market intelligence into executable strategy. It integrates historical performance records with a disciplined forecast framework, enabling readers to test assumptions around volume growth, pricing momentum, and material substitution under multiple scenarios. Beyond the headline trajectory, the report dissects the structural forces shaping supply and demand, including sterilization method compatibility, device complexity trends, healthcare spending patterns, and the operational realities of packaging validation. The segmentation analysis is presented not as a static taxonomy but as a decision matrix, showing how different packaging types, application environments, and geographic exposures interact with cost structures, regulatory expectations, and customer qualification cycles. The competitive profiling extends beyond corporate summaries to examine how major suppliers position themselves across material classes, service capabilities, and regional coverage. Recent developments are incorporated as live indicators of market direction, revealing where investment is flowing, what performance benchmarks are being reset, and which design philosophies are gaining traction. The regulatory overlay is treated as a dynamic factor rather than a static appendix, allowing readers to anticipate where compliance costs will concentrate and where design flexibility may create near-term advantage. For organizations evaluating supplier partnerships, capacity expansion, regional entry, or portfolio rationalization, the full report provides the depth required to support board-level discussion and operational planning.
Forward Positioning: Why the Full Intelligence Matters Now
The sterile medical packaging market is entering a phase in which growth is real, but growth alone does not guarantee profitability or strategic resilience. Margins will be earned through compliance foresight, material engineering rigor, regional regulatory fluency, and a clear understanding of where concentration creates opportunity versus constraint. The difference between reactive sourcing and proactive portfolio strategy will increasingly show up in qualification velocity, cost stability, and customer trust. Our complete market research goes beyond narrative interpretation to deliver the structured quantitative foundation needed to pressure-test assumptions, benchmark competitive exposure, and plan for the 2026–2032 horizon with confidence. For executives who want to move from directional awareness to evidenced strategy, the full report is the next necessary step.
For detailed analysis of this topic, please visit the official page: Sterile Medical Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com