

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fibrinogen Concentrates Market Hits $468.38M in 2025, Poised for 5.96% CAGR Through 2032

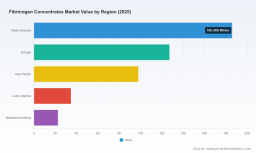
Strategic Imperatives in the Fibrinogen Concentrates Market: A 2026 Outlook
Introduction: The Critical Role of Fibrinogen in Modern Healthcare
The global landscape of hemostatic therapy is undergoing a profound transformation, driven by an aging population, the increasing complexity of surgical procedures, and a heightened focus on patient safety during critical bleeding events. At the center of this evolution lies the Fibrinogen Concentrates Market, a specialized segment of the plasma-derived therapeutics industry that has demonstrated remarkable resilience and growth potential. As we move through 2026, understanding the strategic dynamics of this market is no longer optional for stakeholders in the pharmaceutical, biotech, and healthcare procurement sectors; it is a necessity for sustainable growth and competitive positioning.
Fibrinogen, also known as Factor I, is a crucial protein in the blood coagulation cascade. Its deficiency, whether congenital or acquired, can lead to severe bleeding complications, increased morbidity, and significant healthcare costs. The past few years have witnessed a surge in clinical recognition regarding the importance of fibrinogen replacement therapy in trauma, cardiac surgery, and obstetric hemorrhage. This growing clinical awareness, coupled with regulatory milestones and pipeline advancements, has set the stage for a period of robust expansion. Our latest comprehensive market research provides an exhaustive analysis of these trends, offering a roadmap for navigating the opportunities and challenges that define the current fiscal environment.
For business leaders and investors, the question is not merely whether the market is growing, but how to capture value within a complex matrix of regulatory hurdles, supply chain constraints, and competitive maneuvering. This article serves as a strategic primer, highlighting key insights from our full report while underscoring the depth of analysis available to support your 2026 decision-making processes.
Market Trajectory and Growth Dynamics
The historical performance of the fibrinogen concentrates market tells a compelling story of steady acceleration. From a baseline revenue position in the early 2020s, the market has navigated through pandemic-related disruptions and supply chain bottlenecks to achieve significant expansion by 2025. Our analysis indicates that the market closed the base year at a substantial valuation, reflecting the consolidated efforts of key manufacturers and the increasing adoption of fibrinogen concentrates as a first-line therapy in specific clinical scenarios. This trajectory is not merely a recovery from past volatility but signals a structural shift in how bleeding management is approached globally.
Looking ahead, the growth curve remains positive and robust. Projections for the forecast period extending from 2026 through to 2032 suggest a continued upward momentum. The compound annual growth rate during this period is estimated to reflect a healthy expansion pace, driven by factors such as the widening approval of newer product presentations, the expansion of indications for acquired fibrinogen deficiency, and the gradual penetration of emerging markets. However, growth is not uniform across all vectors. Regional dynamics, varying reimbursement landscapes, and differing clinical guidelines play a pivotal role in shaping the velocity of adoption in specific geographies. Understanding these nuanced drivers is essential for forecasting demand accurately and allocating resources efficiently.
The financial magnitude of this opportunity is significant. By the end of the forecast horizon, market revenue is projected to reach levels that underscore the strategic importance of fibrinogen products within the broader hemostatics portfolio. For companies operating in this space, the ability to anticipate volume growth, manage pricing strategies amidst cost pressures, and align with evolving procurement models will dictate market share retention and profitability. Our report dissects these financial pathways in detail, providing the granularity needed to build resilient business cases.
Product Innovation and Formulation Trends
The competitive landscape is heavily influenced by product differentiation, particularly regarding formulation types. The market is currently segmented based on physical presentation, with lyophilized and liquid formulations representing the dominant categories. Lyophilized fibrinogen concentrates have traditionally held a significant share due to their stability and ease of storage, which are critical advantages in regions with varying infrastructure capabilities. However, the liquid formulation segment is gaining traction, driven by convenience factors and the reduction of reconstitution time in emergency settings.
Recent developments highlight the industry's focus on optimizing these formulations for specific clinical needs. For instance, the introduction of new gram presentations aims to provide flexibility in dosing, catering to both pediatric and adult patient populations while managing inventory costs for hospitals. The shift towards larger presentation sizes for acquired fibrinogen deficiency reflects a growing recognition of the need for rapid, high-volume replacement in acute care scenarios. Furthermore, advancements in purification and virus inactivation technologies continue to enhance the safety profile of these products, addressing long-standing concerns regarding plasma-derived therapies. Manufacturers are increasingly investing in R&D to ensure that their product portfolios remain aligned with the highest standards of clinical efficacy and safety, thereby securing preferential status in hospital formularies.
Fibrinogen Concentrates Market
Human Fibrinogen Market
Application Segmentation and Clinical Drivers
The utility of fibrinogen concentrates spans across several critical therapeutic areas, with surgical bleeding management and congenital fibrinogen deficiency representing the primary application verticals. In the surgical arena, the use of fibrinogen concentrates is becoming increasingly standardized in cardiac, trauma, and orthopedic procedures where blood loss is significant. The drive towards patient blood management (PBM) programs has further accelerated this trend, as hospitals seek to reduce reliance on allogeneic blood transfusions and their associated risks. Fibrinogen concentrates offer a targeted approach to correcting coagulopathy, improving outcomes, and potentially reducing length of stay.
Conversely, the segment dedicated to congenital fibrinogen deficiency, while smaller in terms of patient population, represents a high-value niche attributable to the chronic nature of the condition and the necessity for regular prophylactic treatment. Recent regulatory approvals have expanded the scope of treatment within this segment, allowing for better management of acute bleeding episodes in pediatric and adult patients. Additionally, the acquired fibrinogen deficiency segment is emerging as a key growth area, particularly in the context of massive transfusion protocols and critical care. The widening of indications to include acquired conditions signals a broader therapeutic potential, expanding the total addressable market beyond rare diseases. Our analysis provides a deep dive into the utilization patterns across these applications, correlating them with procedural volumes and clinical guidelines to project future demand vectors.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of established global plasma players and specialized entities, with a moderate level of concentration among the top participants. Key players such as CSL Behring, Octapharma AG, Grifols, S.A., LFB Group, Shanghai RAAS Blood Products Co., Ltd., and Biotest AG are actively shaping the market through product launches, regulatory victories, and strategic collaborations. Each company brings a distinct portfolio of strengths, ranging from global plasma supply capabilities to specialized manufacturing technologies.
CSL Behring remains a formidable presence with its established offerings in the congenital space, leveraging decades of plasma experience. Octapharma AG has been particularly active, with significant approvals expanding the use of its fibrinogen concentrate in acquired deficiency scenarios and introducing new presentation sizes to enhance usability. Grifols has strengthened its position through recent FDA approvals for acute bleeding indications and the establishment of specific billing codes, facilitating reimbursement pathways. LFB Group and Biotest AG continue to focus on their lyophilized offerings, catering to specific regional and clinical preferences. Meanwhile, Shanghai RAAS Blood Products Co., Ltd. represents the growing capability within the Asian market, contributing to regional supply stability and catering to local demand.
Strategic interactions among these players often revolve around regulatory milestones and product differentiation rather than price wars, given the specialized nature of the therapy. However, the competitive intensity is expected to increase as patents expire and new entrants assess the commercial viability of biosimilar or alternative plasma-derived options. Understanding the pipeline timelines, manufacturing capacities, and regulatory strategies of these competitors is vital for identifying gaps in the market and positioning one's own product portfolio effectively.
Regulatory and Economic Headwinds
Despite the positive growth outlook, the market operates within a framework of stringent regulatory requirements and economic pressures that cannot be overlooked. The complexity of plasma collection, testing, and fractionation imposes high barriers to entry and contributes to the overall cost structure of manufacturing. The cost of plasma, specifically fibrinogen-rich materials, constitutes a significant portion of total production costs. This economic reality necessitates efficient fractionation processes and robust supply chain management to maintain margins.
Reimbursement dynamics also play a crucial role in market accessibility. In the United States, the establishment of specific HCPCS codes, such as J7176 for certain fibrinogen products, facilitates claims processing but also brings the therapy under the scrutiny of payer policies. Pricing variability remains a challenge, with standard doses ranging significantly depending on the region and healthcare system. In lower-income regions, the cost barrier can limit access, creating a disparity in treatment availability. Furthermore, clinical policy bulletins from major insurers continue to evolve, influencing prescribing patterns and hospital procurement decisions. Stakeholders must navigate this regulatory labyrinth carefully, ensuring compliance while advocating for value-based reimbursement models that reflect the clinical benefits of fibrinogen concentrates.
Conclusion: The Value of Deep Intelligence
The Fibrinogen Concentrates Market offers a landscape rich with opportunity, defined by clinical innovation, increasing acceptance, and solid growth metrics. However, realizing the full potential of this market requires more than a surface-level understanding of trends. It demands a granular comprehension of regional dynamics, competitive maneuvers, regulatory shifts, and the economic factors that influence procurement and reimbursement. The data points and strategic insights outlined above merely scratch the surface of what is available.
To truly empower your organization for 2026 and beyond, access to comprehensive, validated, and forward-looking intelligence is paramount. Our full market research report delves into the specifics that drive decision-making, offering detailed segmentation analysis, competitive profiling, and scenario planning that is not visible in general summaries. We invite you to explore the complete study to uncover the actionable intelligence needed to refine your strategy, mitigate risks, and capitalize on the evolving demands of the global healthcare landscape. The future of fibrinogen therapy is being written now, and the insights within our report are the tools you need to navigate it successfully.
For detailed analysis of this topic, please visit the official page: Fibrinogen Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com