

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rubidium Atomic Clock Market to Hit $845.41M by 2032 at 7.02% CAGR

Navigating Precision: Strategic Insights Into the Rubidium Atomic Clock Market Through 2032
In an era where nanosecond timing dictates the reliability of global infrastructure, the rubidium atomic clock market has evolved from a niche instrumentation sector into a critical enabler of next-generation defense, telecommunications, and space systems. As enterprises across aerospace, telecom, and scientific research grapple with escalating demands for frequency stability, signal resilience, and miniaturization, understanding where this market is headed is no longer optional—it is a strategic imperative. Our latest comprehensive analysis, spanning historical performance from 2020 through baseline year 2025 and extending across a forecast window to 2032, maps the trajectory of this high-precision timing ecosystem. This overview outlines the market’s structural evolution, highlights the operational content readers can expect from the full study, and underscores why timing intelligence must be embedded into capital allocation, R&D roadmapping, and supply chain strategy in 2026 and beyond.
Market Trajectory: From Steady Growth to Accelerated Expansion
Over the past half-decade, the rubidium atomic clock market has demonstrated consistent, measurable expansion, driven by tightening synchronization requirements across critical infrastructure and the progressive miniaturization of high-stability timing modules. Revenue has climbed from an estimated 400.0 million USD in 2020 to 525.0 million USD by the baseline year of 2025. The forecast period that follows projects this momentum to sustain and gradually accelerate, reaching approximately 574.56 million USD in 2026 and scaling toward 845.41 million USD by the end of the decade. Underlying this progression is a compound annual growth rate of 7.02 percent, a figure that reflects not only incremental adoption but also structural shifts in how precision timing is engineered, deployed, and valued across downstream sectors.
Several macro and sector-specific forces are converging to support this trajectory. The ongoing modernization of satellite navigation architectures, the synchronization demands of dense 5G and emerging 6G network topologies, and the proliferation of space-borne platforms have collectively expanded the addressable base for rubidium-based frequency standards. At the same time, engineering teams are steadily reducing form factors and power consumption, allowing atomic-grade timing to migrate from ground-based reference installations into mobile, airborne, and embedded environments. This transition is redefining the competitive battleground: suppliers that can reconcile long-term frequency stability with size, weight, and environmental ruggedness are capturing disproportionate strategic relevance.
Atomic Clock Market
Yet growth is not uniformly distributed across applications or end-use verticals. The market’s expansion is being shaped by divergent adoption curves, regulatory scaffolding, and procurement cycles that vary significantly by geography and sector. Downstream buyers face an increasingly complex landscape where timing specifications intersect with certification requirements, interoperability mandates, and sustainability considerations. For organizations making investment or sourcing decisions in 2026, relying on aggregate growth figures alone obscures the operational realities that determine which segments will generate outsized returns and which will face margin compression or compliance friction. That is precisely why a granular, forward-looking view is essential.
Structural Complexity: Segmentation Dynamics and Value Distribution
The rubidium atomic clock market is not a monolith. It is a layered ecosystem in which product architectures, deployment environments, and procurement priorities diverge sharply. The full study deconstructs these layers across multiple dimensions, examining how different timing technologies compete for share, how regional demand profiles are evolving, and where application-specific procurement behavior is creating distinct pricing and volume dynamics. Understanding these structural splits is critical because the revenue streams that will drive the next phase of growth are often concentrated in specialized sub-segments that are invisible in top-line aggregates.
From a product architecture standpoint, rubidium-based timing competes within a broader atomic and quasi-atomic frequency control landscape. Each architecture carries distinct trade-offs in stability, size, thermal sensitivity, and total cost of ownership. Procurement teams increasingly evaluate these trade-offs not simply as technical specifications but as strategic risk factors—particularly in environments where timing failure can cascade into communication loss, navigation degradation, or mission-critical downtime. The report maps how these technology pathways are being positioned across defense, aerospace, telecommunications, and research applications, highlighting where engineering roadmaps are converging and where manufacturers are pursuing differentiated niches.
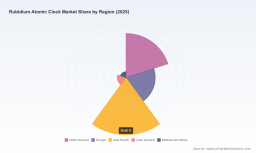
Regionally, demand is shaped by a combination of infrastructure investment cycles, defense modernization programs, and regulatory frameworks that influence both specification requirements and procurement lead times. Certain markets are expanding rapidly due to concentrated network rollouts and localized manufacturing initiatives, while others are maturing into steady, specification-driven replacement and upgrade cycles. The full analysis dissects these regional behaviors without reducing them to simplistic rankings, instead focusing on the procurement drivers, certification pathways, and supply chain configurations that determine how each geography contributes to the overall revenue base.
Rubidium Atomic Clock Market
Application-side dynamics further complicate the picture. Timing requirements in space and military deployments prioritize resilience, radiation tolerance, and long-term frequency holdover under disconnected operating conditions. Telecom and broadcasting deployments emphasize synchronization density, interoperability, and compliance with evolving network timing standards. Scientific and metrology environments prioritize ultra-low phase noise and laboratory-grade stability. Each vertical imposes its own cost tolerance, qualification timeline, and vendor evaluation criteria. For enterprise planners, the strategic question is no longer whether to adopt high-precision timing, but how to align product selection and supply relationships with the specific risk and performance profile of the target segment.
Competitive Landscape: Positioning, Innovation, and Strategic Consolidation
The competitive terrain in the rubidium atomic clock market reflects a blend of established aerospace and defense specialists, frequency-control manufacturers, and emerging players expanding their footprint through miniaturization and cost-optimized architectures. The landscape is characterized by high concentration at the top tier, with a relatively small group of suppliers capturing a substantial share of high-value deployments, while a broader set of manufacturers competes in specialized, volume-sensitive, or application-tailored niches. This structure has important implications for sourcing strategy, partnership selection, and long-term supply assurance.
Among the most prominent participants, Safran Electronics & Defense has reinforced its leadership position through continuous refinement of its rubidium oscillator and miniature clock portfolio. Its recently introduced second-generation miniature Rubidium atomic clock, MIRA, underscores a deliberate strategy to deliver high stability in compact form factors for defense, aerospace, telecom, and industrial markets. This kind of product evolution signals a broader industry shift: competitive advantage is increasingly tied to how effectively a supplier can compress performance envelope requirements into deployable, environmentally resilient modules.
AccuBeat Ltd has likewise maintained a strong identity in the rubidium oscillator and atomic clock segment, with product families engineered for military, defense, space, and critical infrastructure applications. Its focus on GPS and Rubidium-integrated solutions highlights a recurring theme in the market: the blending of atomic timing with positioning and navigation subsystems to create resilient, holdover-capable ensembles. In parallel, firms such as Excelitas Technologies and Frequency Electronics, Inc. continue to advance space-qualified and defense-oriented timing standards, where qualification rigor, environmental endurance, and long-term reliability often outweigh pure unit-cost considerations.
On the industrial and commercial side, manufacturers like Microchip Technology are pushing next-generation miniaturized rubidium atomic clocks and embedded atomic oscillators into aviation, industrial, and ruggedized military environments, expanding the perimeter of where atomic-grade timing can be economically deployed. IQD Frequency Products Ltd and Stanford Research Systems continue to serve precision timing, laboratory, and frequency-control niches, reinforcing the market’s diversity of use cases. Meanwhile, regional production capacity is also expanding, with players such as Chengdu Spaceon Electronics Co., Ltd. strengthening China’s position as a notable source of rubidium atomic clocks, frequency standards, and space-borne timing solutions for satellite and defense applications.
Recent product activity illustrates how quickly this landscape is evolving. In addition to Safran’s MIRA launch in late 2025, Milexia introduced a cost-effective, widely adaptable miniature Rubidium Atomic Clock, signaling that competitive pressure is not only about performance ceilings but also about lowering barriers to adoption across broader application sets. For procurement leaders and technology planners, these developments complicate the traditional supplier evaluation process: the optimal choice may depend less on brand recognition than on the alignment between a specific clock architecture, the intended operating environment, and the qualification pathway required by the end customer or regulator.
Regulatory Calibration: Compliance as a Market Shaper
Regulatory and standards-driven dynamics are playing an increasingly visible role in shaping the rubidium atomic clock market’s consumption patterns. In several key markets, regulatory updates have begun to redefine what qualifies as acceptable timing performance in telecommunications equipment, military systems, and synchronization infrastructure. For instance, recent radio frequency regulatory updates have mandated stricter timing accuracy and interference mitigation for rubidium atomic clocks used in telecommunications equipment. These requirements do more than influence engineering design; they alter the qualification burden, affect interoperability expectations, and create new barriers for suppliers whose architectures were not originally designed with such constraints in mind.
In parallel, enhanced certification standards for timing devices in military applications have placed greater emphasis on robustness under extreme environments and the integration of cybersecurity features. This reflects a broader realization that timing subsystems are not simply performance components; they are potential vectors of operational vulnerability if not properly hardened and secured. Similarly, mandates around interoperability protocols for synchronization devices within 5G infrastructure have required atomic clocks to meet precise frequency stability benchmarks, tightening the alignment between equipment manufacturers, network operators, and timing suppliers. Environmental regulations have added another layer, imposing energy efficiency and hazardous substance restrictions that push manufacturers toward greener production processes and more conscientious material selection.
Together, these regulatory threads create both constraints and opportunities. Suppliers that proactively design for compliance can use certification readiness as a differentiator, shortening customer evaluation cycles and unlocking procurement in regulated verticals. Conversely, organizations that treat regulatory requirements as afterthoughts may face redesign delays, qualification failures, or exclusion from strategic contracts. In 2026, compliance capability is increasingly inseparable from commercial competitiveness in high-precision timing.
Beyond regulation, broader industry context continues to shape deployment velocity. Supply chain normalization, the cadence of satellite and ground network investments, and the pace of defense modernization all influence how quickly timing requirements translate into procurement decisions. The report integrates these dynamics into a working view of demand timing, helping readers distinguish between near-term commercial pull and longer-cycle institutional adoption.
Inside the Report: Practical Intelligence for 2026 Decision-Makers
This study is designed to move beyond headline figures and provide a working reference for teams responsible for strategy, procurement, R&D prioritization, and market entry planning. Rather than presenting a static snapshot, the analysis is structured to support decision-making across multiple planning horizons. Readers can expect detailed coverage of historical performance trends, baseline sizing, and a forecast framework that connects market growth to the underlying drivers most likely to influence spending patterns through 2032.
The report breaks down market structure across product type, application, and regional demand behavior, with attention to how each segment contributes to overall revenue and how segment dynamics differ in terms of adoption drivers, qualification burdens, and competitive intensity. Rather than leaving readers with broad averages, the study identifies where demand is concentrated, where growth is accelerating, and where structural headwinds or regulatory friction may temper expansion. This segmented view is essential for companies evaluating whether to invest in specific product lines, target particular verticals, or allocate sales and engineering resources to the highest-probability opportunities.
Competitive profiling forms another core pillar of the research. The analysis maps the strategic positioning of leading suppliers, the product families they emphasize, and the application sets they prioritize. It examines how recent product launches and technology upgrades are reshaping buyer expectations, and where supplier differentiation is increasingly tied to miniaturization, environmental qualification, holdover performance, and compliance readiness. For organizations evaluating vendor partnerships, M&A targets, or substitution risk, these profiles are built to support direct, evidence-based comparison rather than reputation-based assumptions.
The study also incorporates demand-side analysis, covering how procurement cycles, specification tightening, and system-level integration requirements influence buying behavior across space and military, telecom and broadcasting, scientific and metrology research, and other application areas. This is complemented by an examination of regulatory and standards-driven influences, including certification expectations, synchronization mandates, and environmental compliance considerations that affect both product design and market access. The objective is to give readers a practical framework for anticipating how policy and technical standards will alter procurement speed, qualification cost, and supplier selection over the forecast period.
To make the intelligence actionable, the report connects market data to strategic use cases. These include assessment of total addressable demand for different timing architectures, identification of the segments most exposed to miniaturization-driven expansion, evaluation of supply chain dependency risks, and guidance on where timing investment is likely to generate the strongest return under current adoption patterns. The analysis is calibrated for teams that need to compare market opportunity against internal capability, prioritize roadmap commitments, and understand where competitive pressure is likely to intensify.
Strategic Imperatives: Why Timing Intelligence Matters in 2026
For enterprise leaders, the rubidium atomic clock market is not merely a component segment; it is a timing backbone that influences the reliability, interoperability, and resilience of systems operating across defense, space, telecommunications, and research environments. In 2026, strategic decisions in this space will be shaped by three interlocking realities. First, precision timing is becoming more widely embedded, driven by miniaturization and cost optimization that expand the set of applications where atomic-grade stability is economically viable. Second, procurement is increasingly governed by regulatory and certification frameworks that reward compliance-ready architectures and penalize designs that lag behind evolving standards. Third, competitive advantage is migrating from pure performance leadership toward integrated value propositions that combine stability, environmental ruggedness, cybersecurity awareness, and supply assurance.
Organizations that approach this market with only top-line growth data risk misallocating resources. A segment may show strong aggregate momentum while remaining difficult to access due to qualification complexity or certification burden. Another may offer more moderate growth but clearer procurement pathways and lower substitution risk. A supplier may be well known in one application domain yet less competitive in another where size, power, or environmental tolerance matters more. The full study is built to expose these nuances, enabling decision-makers to separate structural opportunity from surface-level headline appeal.
In practice, this means using timing intelligence to answer questions that directly affect enterprise outcomes. Which application verticals are most likely to drive near-term volume growth, and which will require longer qualification cycles? Where do regulatory mandates create the steepest barriers to entry, and where do they function as competitive moats for prepared suppliers? How should sourcing strategies account for concentrated supply at the top of the market while still capturing innovation from smaller or regionally focused manufacturers? And where does miniaturization open new addressable use cases that can justify internal development investment or partnership formation?
The answers to these questions depend on granular evidence, not generalized market narratives. By aligning strategy with detailed segment behavior, regulatory trajectory, and competitive positioning, organizations can reduce exposure to specification shifts, anticipate procurement timing more accurately, and position their offerings where buyer expectations and regulatory realities intersect most favorably.
Conclusion: The Case for Deeper Intelligence
The rubidium atomic clock market is entering a phase where growth is increasingly defined by how well suppliers and buyers navigate technical, regulatory, and competitive complexity. Aggregate revenue expansion provides the broad outline, but the strategic value lies in the underlying structure: how demand is distributed across applications and regions, how product architectures compete on stability, size, and compliance, and how a concentrated group of leading manufacturers is shaping the procurement environment. For organizations making decisions in 2026, those details determine whether timing strategy becomes a source of advantage or a source of exposure.
This overview has outlined the market’s direction, the forces shaping its evolution, and the practical dimensions covered in the full study. To move from directional awareness to actionable planning, readers need the segmentation detail, competitive comparisons, regulatory integration, and demand-side analysis that the complete report provides. The full intelligence package is available through our research portal, where the complete dataset, segment breakdowns, company profiles, and forecast framework can be reviewed in depth. For teams responsible for market entry, procurement optimization, product roadmap planning, or investment prioritization, accessing the full study is the next step toward turning precision timing from a technical requirement into a strategic asset.
For detailed analysis of this topic, please visit the official page: Rubidium Atomic Clock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com