

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Baby Diaper Rash Cream Market to Reach $280.95M by 2032, 5.75% CAGR

Strategic Intelligence for the Next Wave: Inside the Baby Diaper Rash Cream Market Outlook 2026-2032
The global baby care landscape is undergoing a quiet but significant transformation. As parents become increasingly informed about ingredient safety, barrier protection, and dermatological efficacy, the baby diaper rash cream market has evolved from a commoditized essential into a strategically nuanced segment of the broader infant wellness economy. At PW Consulting, we recognize that navigating this space requires more than headline figures. It demands a rigorous understanding of formulation science, regulatory divergence, distribution channel shifts, and the competitive maneuvers that will separate resilient brands from vulnerable ones over the next seven years.
This article serves as a strategic preview of our newly released market research report. It is designed to give executives, product developers, and category strategists a clear view of the macro trajectory, the structural forces reshaping value creation, and the analytical depth waiting inside the full document. Consider this a trailer: it establishes the narrative arc and demonstrates the methodology, while reserving the precise segmentation intelligence for the complete briefing.
The Macro Trajectory: A Market in Measured Expansion
Drawing on historical data from 2020 through 2025 and extending our forecast horizon to 2032, the baby diaper rash cream market demonstrates a pattern of steady, compounding growth rather than volatile spikes. The sector has consistently expanded its revenue base, reflecting enduring parental demand, rising premiumization, and the proliferation of clinically oriented skincare messaging. Our baseline analysis places the market on a forward compound annual growth rate of 5.75 percent, a trajectory that underscores both resilience and structural opportunity.
Historical movement tells a story of incremental but reliable scaling. Revenue progression from the early 2020s through 2025 reflects a market that absorbed pandemic-era supply chain friction, adapted to shifting retail behaviors, and emerged with stronger online penetration and heightened ingredient scrutiny. Looking ahead, the forecast window from 2026 through 2032 maps a continued upward curve, with revenue levels advancing steadily as formulation innovation, distribution optimization, and regional demand maturation compound over time.
For corporate strategists, this trajectory carries a clear implication: growth in this category will not be captured by broad strokes alone. The companies that outperform will be those that understand where value concentrates, which formulation families command premium positioning, how distribution economics are recalibrating, and which regulatory shifts will alter cost structures or product architectures. Our full report dissects these layers systematically, giving decision-makers the granularity required to allocate resources with confidence.
Structural Pillars Shaping Competitive Advantage
The strategic landscape of the baby diaper rash cream market is defined by several interlocking dynamics. Understanding these forces is essential for any organization seeking to build durable advantage in a category where trust, efficacy, and compliance converge.
Formulation and Ingredient Economics
The category is anchored by a small number of formulation families that dominate consumer recognition and clinical positioning. Zinc oxide-based products remain the cornerstone of barrier protection, supported by petroleum jelly derivatives and lanolin-based alternatives that address different sensory and dermatological preferences. Input cost structures are closely tied to zinc oxide and specialty emollients, meaning that raw material volatility, sourcing strategy, and formulation efficiency directly influence margin performance. Companies that master ingredient optimization while maintaining perceived efficacy are best positioned to defend pricing power.
A critical dimension of formulation strategy is regulatory alignment. The U.S. FDA skin protectant monograph permits up to 40 percent zinc oxide in diaper rash ointments, while the European Union caps zinc oxide at 25 percent and prohibits spray formats. This divergence creates both complexity and opportunity: multinational portfolios must be engineered for regional compliance, while nimble players can differentiate through format innovation where regulation allows. Additionally, the harmonization of monographs on petrolatum by the U.S. Pharmacopeia, taking effect in August 2026 with mandatory UV absorbance testing for polycyclic aromatic hydrocarbons, introduces a new compliance layer that will affect sourcing, quality assurance, and product labeling. Anticipating these requirements is no longer optional; it is a core component of product lifecycle management.
Distribution Channel Reconfiguration
How these products reach consumers is undergoing a quiet rebalancing. Pharmacies remain a dominant channel, reflecting the category's clinical undertones and the trust associated with pharmacist recommendations. Supermarkets and online retailers form the next tier of volume drivers, while specialty baby stores serve a more curated, premium-oriented audience. The strategic question for brands is not simply which channel is largest, but how channel economics, margins, consumer search behavior, and replenishment patterns interact. Our analysis evaluates the relative strategic weight of each pathway and identifies where portfolio placement, promotional architecture, and digital discovery investments will yield the highest returns.
Demand Segments and Usage Contexts
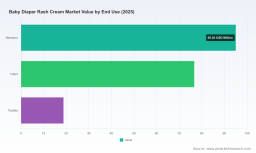
The market serves distinct end-use contexts, each with its own purchasing triggers, formulation expectations, and replenishment cadence. Newborn care remains the most intensive usage period, driven by frequent diaper changes and heightened parental vigilance. Infant care represents a broad and sustained demand base, while toddler usage typically reflects a narrower but still meaningful presence as potty-training transitions alter diaper exposure. Recognizing how these segments differ in price sensitivity, ingredient preferences, and purchase frequency is essential for messaging precision and pack architecture. The full report maps these usage dynamics in detail, enabling brands to tailor product lines and communication strategies to the moments that matter most.
Baby Diapers Market
Geographic Variation and Regional Priorities
Demand is not uniform across the globe. Regional market structures reflect differences in birth rates, retail modernization, healthcare infrastructure, skincare awareness, and regulatory environments. Our research evaluates the relative scale and strategic significance of key regions, highlighting where volume growth, premiumization, and channel expansion create the most attractive entry or reinforcement opportunities. For organizations planning multi-market rollouts or seeking to rebalance their geographic portfolio, this regional intelligence provides a practical scaffold for prioritization.
Competitive Landscape: Strategic Postures in a Concentrated Arena
Market concentration in this category is moderate but meaningful, with a concentrated group of large multinational and specialist players commanding significant share. The interplay between scale, brand equity, formulation credibility, and channel access defines the competitive rhythm. Our report profiles the companies shaping the category, examining how each leverages its positioning to defend or expand its footprint.
Johnson & Johnson, headquartered in New Brunswick, New Jersey, brings deep category heritage and broad consumer trust to its baby care offerings. The Procter & Gamble Company, based in Cincinnati, Ohio, applies its portfolio management discipline and distribution scale to maintain strong category presence. Beiersdorf AG, from Hamburg, Germany, contributes skincare science and dermatological credibility that resonate in premium and efficacy-driven segments. Unilever, headquartered in London, leverages its global brand architecture and sustainability narrative to connect with modern parenting values. The Honest Company, from El Segundo, California, has built its identity around transparent ingredient standards and lifestyle-aligned branding, appealing to consumers who prioritize clean-label positioning.
Beyond these larger platforms, a set of specialized and organic-oriented players adds fragmentation and innovation pressure. Babo Botanicals, based in Emeryville, California, emphasizes gentle botanical formulations. Earth Mama Organic Company, operating in the United States, focuses on plant-based and organic credentials. Summer Laboratories, also in the United States, brings a clinical and specialty formulation perspective. Sebapharma, from Biberach, Germany, contributes European dermatological expertise. Himalaya Wellness, headquartered in Bangalore, India, extends the category into emerging-market herbal and traditional formulation narratives. Weleda AG, based in Arlesheim, Switzerland, reinforces biodynamic and natural skincare positioning. Burt's Bees, from Union, South Carolina, capitalizes on natural ingredient association and broad consumer recognition. Desitin, operating in the United States, remains closely identified with targeted rash protection and barrier-focused product architectures.
The strategic behavior of these players is not static. Innovation events, such as Desitin's January 2025 introduction of a new triple-action diaper rash cream incorporating zinc oxide and ceramide technology to enhance barrier protection and soothe irritated skin, illustrate how incumbents continue to refresh their value propositions. These launches matter because they raise the bar on formulation expectations, reshape shelf dialogue, and force competitors to respond with their own efficacy narratives. Our competitive analysis examines how each organization's offering, brand architecture, and go-to-market posture align with the structural opportunities and constraints identified across formulation, distribution, regulation, and regional demand.
From Insight to Action: What the Full Report Delivers
Market headlines can indicate direction, but they rarely provide the operational clarity needed to make portfolio, pricing, and launch decisions. That is why our research is built around actionable analytical modules rather than static summaries. The complete report is designed to support multiple decision contexts, from long-range capacity and innovation planning to short-term channel prioritization and competitive response mapping.
Inside the full briefing, readers will find a structured examination of the category's revenue trajectory across the forecast window, contextualized by historical momentum and forward growth drivers. The report breaks down the strategic implications of formulation families, distribution pathways, end-use segments, and regional demand patterns without losing sight of how these dimensions interact. Competitive profiles go beyond descriptive overviews to evaluate brand positioning, portfolio logic, and likely areas of strategic pressure or expansion. Regulatory and input-cost developments are integrated into the analysis so that quality, compliance, and margin considerations are evaluated together rather than in isolation.
For executives, the report functions as a decision-grade reference point. For product and R&D leaders, it clarifies where formulation differentiation can translate into defensible positioning. For commercial teams, it maps the channel and segment dynamics that determine where promotional investment and shelf strategy will generate the strongest returns. For corporate development and partnership teams, it identifies where concentration, fragmentation, and innovation activity suggest consolidation, collaboration, or targeted acquisition opportunities.
Baby Diaper Rash Cream Market
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle arrives at a moment when the category's fundamentals are stable but its strategic complexity is rising. Growth is steady, but it is being shaped by ingredient scrutiny, regulatory divergence, channel economics, and the continuous innovation cadence of both large incumbents and focused specialists. In this environment, decisions made without granular context carry higher risk. A formulation roadmap that ignores upcoming monograph requirements may create compliance exposure. A channel expansion plan that overlooks replenishment behavior and margin structure may underperform. A regional prioritization exercise that lacks segment-level demand insight may misallocate resources.
Our report is designed to reduce that uncertainty. It provides the analytical scaffolding needed to align product, commercial, and supply decisions with the realities of the market as it is evolving, not as it was five years ago. By combining macro trajectory analysis with structural evaluation across formulation, distribution, end use, region, regulation, and competition, the research gives organizations a coherent basis for prioritizing initiatives and anticipating shifts before they become crowded.
The full report is available through PW Consulting's research portal. Readers seeking complete segmentation data, regional and channel breakdowns, formulation and end-use detail, and in-depth competitive profiling are encouraged to access the full briefing directly. For teams preparing 2026 strategies, the comprehensive document offers the level of precision required to move from informed awareness to decisive action.
For detailed analysis of this topic, please visit the official page: Baby Diaper Rash Cream Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com