

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Friction Stir Welding Market Hits $215M in 2025, Poised for 6.7% CAGR Through 2032

Navigating the Future of Fabrication: Strategic Insights from the 2026 Friction Stir Welding Equipment Market Report
The Evolution of Solid-State Joining in a High-Growth Economy
The manufacturing landscape is undergoing a profound transformation, driven by the imperative for lightweighting, energy efficiency, and superior joint integrity. At the forefront of this shift is Friction Stir Welding (FSW) technology, a solid-state joining process that has moved from niche applications to a cornerstone of modern industrial fabrication. As we navigate the forecast period from 2026 to 2032, understanding the trajectory of the Friction Stir Welding Equipment Market is no longer optional for industry stakeholders—it is a strategic necessity.
PW Consulting's latest comprehensive study offers a granular view of this evolving ecosystem. The market has demonstrated resilience and steady growth over the historical period from 2020 to 2025, recovering from minor fluctuations to establish a robust foundation. In 2020, the market valuation stood at 162.5 million USD, climbing to 174.96 million USD in 2021. While 2022 saw a slight contraction to 174.34 million USD, the subsequent years revealed strong upward momentum, reaching 190.31 million USD in 2023 and 196.68 million USD in 2024. By the base year of 2025, the market had expanded to 215.0 million USD. This historical performance sets the stage for a forecast period characterized by accelerated expansion.
Looking ahead, the trajectory from 2026 through 2032 indicates a compound annual growth rate (CAGR) of 6.7 percent. Starting at an estimated 223.36 million USD in 2026, the market is projected to crescendo towards 341.75 million USD by 2032. This growth is not merely a function of increased demand but reflects a fundamental shift in manufacturing philosophies where process efficiency and material performance take precedence over traditional methods.
Key Market Drivers and Structural Dynamics
Several critical factors are converging to propel the adoption of FSW equipment across multiple sectors. One of the most significant drivers is the comparative energy efficiency of the technology. Industry analysis indicates that FSW technology reduces energy consumption by approximately 18 percent compared to conventional fusion welding processes. In an era where operational costs and carbon footprints are under intense scrutiny, this efficiency gain presents a compelling value proposition for large-scale manufacturers seeking to optimize their production lines.
However, the path to widespread adoption is not without hurdles. The industry faces a notable labor constraint. Skilled technicians required for advanced welding operations faced a 42 percent shortage in small-scale manufacturers as of 2025. This scarcity of expertise underscores the importance of automation and robotic integration within FSW equipment. As human capital becomes a bottleneck, the demand for systems that reduce reliance on highly specialized manual intervention is expected to rise, favoring manufacturers who can offer turnkey automated solutions.
Regulatory frameworks also play a pivotal role in shaping market behavior. The ISO 25239 series (2020) establishes requirements for FSW procedure qualification, weld quality testing, and operator certification for aluminum and alloys. Compliance with these standards is becoming a prerequisite for entering high-stakes supply chains, particularly in aerospace and automotive sectors. Equipment vendors who can guarantee compliance with ISO standards through their machine precision and integrated quality control features will hold a distinct competitive advantage.
Furthermore, raw material volatility influences procurement strategies. For instance, the LME Aluminium cash settlement price reached 3,736.00 USD per tonne on 5 June 2026. Fluctuations in aluminum prices directly impact the cost-benefit analysis of welding processes. Since FSW is particularly renowned for its effectiveness with aluminum alloys, maintaining cost efficiency in the face of commodity price volatility is a key consideration for purchasing managers evaluating equipment investments.
Friction Stir Welding Equipment Market
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three players holding a combined market share of 26.8 percent and the top five players accounting for 32.5 percent. This fragmentation suggests ample opportunity for both established giants and specialized innovators to capture value, provided they differentiate through technology and service offerings.
Leading the charge is MTI Welding, a global manufacturer based in the United States. Utilizing STIRTEC technology, MTI provides industrial-grade FSW machines and systems that cater to a broad spectrum of applications. Their global footprint allows them to serve diverse markets, setting a benchmark for reliability. Similarly, Mazak Corporation from Japan continues to innovate with its MegaStir line. By integrating FSW machines, tools, and consulting services with hybrid multi-tasking CNC systems, Mazak offers a unified solution that streamlines production workflows. Their recent showcase at Discover 2025 highlighted the advantages of high-speed FSW, reinforcing their commitment to technological leadership.
In the United States, PAR Systems has carved a niche with its I-STIR™ technology, specifically targeting large, complex industrial applications. Their ability to handle substantial workloads makes them a critical partner for sectors like shipbuilding and heavy infrastructure. Meanwhile, European engineering prowess is exemplified by FOOKE GmbH in Germany. They produce high-performance gantry-based FSW machines tailored for aluminum sheet joining in automotive, aerospace, and rail sectors. Their focus on precision and load capacity addresses the rigorous demands of transportation manufacturing.
Stirweld, based in France, takes a modular approach by specializing in FSW heads for CNC machines and spindles for robots. This enables integrated welding and machining solutions, allowing manufacturers to retrofit existing infrastructure rather than investing in entirely new production lines. On the other side of the Atlantic, Bond Technologies provides comprehensive FSW machines and systems, including Rotary Friction Stir Spot Welding (RFSSW) for automotive, aerospace, shipbuilding, and rail applications. Their versatility across industries makes them a flexible partner for diversification strategies.
KUKA AG, another German powerhouse, focuses on robotic FSW cells and systems using KR FORTEC robots. Their solution is designed for high-volume production in automotive and e-mobility, addressing the scalability needs of mass manufacturers. Quickmill complements this landscape with gantry-style CNC milling machines featuring integrated FANUC-controlled FSW capability, specifically useful for thick plate welding. FPT Industrie from Italy rounds out the competitive field with advanced FSW machines such as the StirCell, catering to specialized industrial applications.
Recent Developments and Technological Momentum
The pace of innovation in this sector is accelerating, as evidenced by recent collaborations and product launches. In October 2025, TWI Ltd and Stirweld showcased retractable pin FSW head technology specifically for aluminum hydrogen storage tank welding in aerospace applications. This development is critical as the aerospace industry seeks lighter, safer fuel storage solutions for next-generation aircraft and hydrogen-powered propulsion systems.
Demand signals from the automotive sector are equally strong. In July 2025, KUKA received an order for 12 additional FSW robotic units from a leading U.S. carmaker for electric vehicle battery housing assembly. This order underscores the pivotal role of FSW in the electrification of transport, where battery housing integrity and thermal management are paramount. The trend continued into 2026, with Hufschmied demonstrating FSW integration as part of the DMG MORI in-house exhibition in February. Such demonstrations highlight the growing synergy between machining centers and welding systems, promoting hybrid manufacturing concepts.
Going further into the forecast period, Stirweld is scheduled to exhibit at SpaceTech Expo USA and The Battery Show with FSW robotic solutions in June 2026. These events serve as platforms for validating new technologies with industry leaders. Additionally, Mazak showcased MegaStir high-speed FSW advantages at Discover 2025, reinforcing the narrative that speed and quality are no longer mutually exclusive in FSW processes.
Segmentation Strategy and Investment Implications
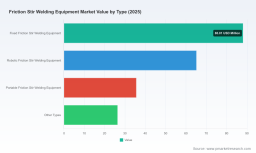
While the aggregate market numbers provide a macroeconomic view, the true strategic value lies in understanding the segmentation shifts. The equipment type landscape is dominated by Fixed Friction Stir Welding Equipment, reflecting the need for stability and precision in high-volume settings. However, Robotic Friction Stir Welding Equipment represents a dynamic growth segment, driven by the labor shortages and the need for flexibility in production lines. Portable Friction Stir Welding Equipment serves specialized on-site repair and construction needs, while Other Types capture emerging niche applications.
Application-wise, the Automotive Industry remains the primary revenue driver, fueled by the transition to electric vehicles and the demand for lightweight aluminum structures. The Aerospace Industry follows closely, leveraging FSW for fuel tanks, fuselage components, and engine parts where defect tolerance is zero. Shipbuilding Industry adoption is growing due to the need for large aluminum hull structures resistant to corrosion, while Railways Industry usage is expanding for high-speed train components. Others include general industrial manufacturing where specific joining requirements dictate the use of solid-state processes.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct regulatory environments, labor cost structures, and manufacturing capabilities. For instance, regions with high labor costs may favor robotic solutions more heavily, while regions with growing infrastructure projects may prioritize portable or fixed systems for heavy civil applications. A detailed regional analysis is crucial for companies planning global expansion or supply chain localization.
Why This Report is Essential for 2026 Decision-Making
In a market projected to grow from 223.36 million USD in 2026 to over 340 million USD by 2032, the cost of inaction or misinformed strategy is significant. This report is designed to equip executives, investors, and product managers with the intelligence needed to navigate this growth curve. It moves beyond surface-level statistics to provide actionable intelligence on vendor selection, technology trends, and regional opportunities.
Readers will gain access to a detailed analysis of the competitive positioning of key players, evaluating their strengths, weaknesses, and strategic moves. The report dissects the segmentation splits with precision, allowing stakeholders to identify high-potential niches without exposing them to the noise of aggregate data that may not apply to their specific context. Understanding the interplay between labor shortages, energy efficiency mandates, and regulatory standards is critical for forecasting internal demand and budgeting for capital expenditure.
Moreover, the report contextualizes raw material dynamics and regulatory changes within the broader equipment procurement strategy. By analyzing recent developments such as the KUKA order surge and TWI collaborations, the study infers future demand patterns that are not yet visible in historical data. This forward-looking perspective is vital for aligning R&D roadmaps and production capacity planning with market reality.
The fragmentation of the market, with a CR5 of 32.5 percent, implies that consolidation opportunities or disruptive innovations could reshape the leaderboard. Investors need to know where value is being created and where margin pressure exists. Manufacturers need to know which technologies are becoming commoditized and which command a premium. This research provides the framework to answer those questions.
Conclusion: Preparing for the Next Wave of Manufacturing Innovation
The Friction Stir Welding Equipment Market is at an inflection point. The convergence of electrification, lightweighting mandates, and automation trends creates a fertile environment for growth. However, realizing value in this market requires more than just capital investment; it requires strategic alignment with technological trends and a deep understanding of the competitive terrain.
Friction Welding Machine Market
PW Consulting's 2026 Market Research Report serves as a definitive guide for navigating this complexity. It synthesizes historical performance, forecast projections, and qualitative industry dynamics into a coherent strategic narrative. For organizations aiming to lead in manufacturing innovation, access to this level of detail is not merely an advantage—it is a prerequisite for sustained competitiveness. The data speaks to a clear trajectory of growth, but the specific pathways to capturing that growth are detailed within the full study. Stakeholders are encouraged to delve deeper into the comprehensive analysis to unlock the specific insights relevant to their operational goals and market position.
For detailed analysis of this topic, please visit the official page: Friction Stir Welding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com