

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hole Saw Market to Hit $533.6 Million by 2032 with 6.98% CAGR

Strategic Intelligence in the Hole Saw Market: Navigating Growth and Consolidation Through 2032
The hole saw market stands at a critical inflection point for industrial and construction-sector decision-makers. As infrastructure modernization accelerates globally and precision hole-making tools become integral to workflow efficiency, understanding the trajectory of this specialized segment is no longer optional—it is a strategic imperative. PW Consulting’s latest definitive market research on the hole saw industry delivers the analytical rigor required to navigate a landscape defined by material innovation, shifting end-user demand, and pronounced competitive concentration.
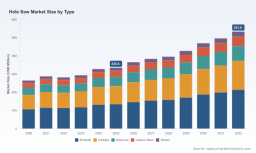
Grounded in a comprehensive historical baseline spanning 2020 through 2025 and extending forward to 2032, the report captures the full lifecycle of market evolution. From a starting valuation of USD 265.0 million in 2020, the sector demonstrated resilience through fluctuating industrial cycles, expanding to USD 335.4 million by 2025. The trajectory points decisively upward, with the market projected to reach USD 533.6 million by 2032. This expansion is anchored by a steady compound annual growth rate of 6.98 percent across the 2026 to 2032 forecast window. For executives formulating capital allocation, product development roadmaps, and supply chain strategies, this statistical arc provides more than a scorecard—it offers a behavioral map of buyer preferences, application drift, and regional performance patterns that will dictate market outcomes for the next seven years.
What separates this research from conventional industry trackers is its deliberate alignment with actionable enterprise strategy. Rather than offering retrospective summaries, the analysis is structured to answer the operational questions that procurement directors, R&D leads, and channel managers face daily: which material grades are commanding premium positioning, how dry versus wet drilling methodologies are reshaping end-use expectations, and where commercial versus domestic user bases are absorbing incremental volume. The study also dissects product architecture across bi-metal, carbide, diamond, carbon steel, and specialty variants, mapping their respective value propositions against performance durability and total cost of ownership. By translating raw market sizing into functional intelligence, the report equips stakeholders to anticipate demand shifts before they manifest in quarterly orders.
The competitive architecture of the hole saw sector presents a landscape of high consolidation and specialized differentiation. Market concentration metrics reveal that the top three players command approximately seventy-eight percent of aggregate share, while the top five firms control nearly eighty-eight percent. This structural reality underscores both the barriers to entry and the opportunities for incumbents to refine positioning through innovation, warranty engineering, and application-specific tooling. A closer examination of the leading manufacturers illustrates how strategic product architecture is being deployed to capture distinct operational niches and defend market standing.
Bi-Metal Engineering as a Foundational Platform
Bi-metal construction has emerged as the operational backbone for professional and trade-grade hole saw deployment, with major manufacturers investing heavily in tooth reinforcement, variable pitch geometry, and durability warranties. LENOX has positioned its SPEED SLOT Bi-Metal Hole Saws as a complete system solution, emphasizing reinforced tooth design to reduce breakage and extend service life under sustained cutting loads. Greenlee has tailored its bi-metal lineup directly to professional electricians and industrial installers, pairing hole saws and arbors with accessories designed for high-frequency trade use. Milwaukee Tool has advanced the segment further with its HOLE DOZER platform, integrating bi-metal and carbide teeth options while backing the product line with a Lifetime Tooth Break Warranty, ALL-ACCESS SLOT configurations, and a twenty-five percent faster cutting profile optimized for cordless tool ecosystems. IRWIN Tools has pursued a similar durability-first philosophy through its WeldTec bi-metal platform, utilizing variable tooth design to balance extended life with improved cutting performance, and packaging these capabilities into heavy-duty kits that address high-demand job site scenarios.
Carbide and Specialized Tooth Architectures
Where bi-metal addresses general-purpose resilience, carbide and specialty tooth designs target material-specific performance thresholds. Milwaukee Tool’s bi-metal/carbide hybrid approach demonstrates how mixed-material tooth engineering is becoming a differentiator in speed and wear resistance. Diablo Tools has carved a distinct positioning with its Demo Demon Carbide Teeth Rough-In Hole Saw Sets, engineered to deliver clean boring through wood and nail-embedded substrates where conventional tooling would degrade rapidly. Starrett extends its precision industrial portfolio into hole-making with curated hole saw sets that appeal to users prioritizing dimensional consistency and repeat accuracy. Morse Cutting Tools has pushed application boundaries with its impact-compatible hole saw line, leveraging quick-change quarter-inch impact shanks to streamline thin-metal cutting operations and reduce tool-change friction on active job sites. These developments reflect a broader market trend in which manufacturers are moving beyond generic sizing to embed application intelligence directly into product architecture.
System Integration and Trade-Channel Momentum
RIDGID continues to reinforce its utility and construction footprint by supplying comprehensive hole cutting tools, arbors, and complete hole saw systems calibrated for plumbing and structural applications. The company’s emphasis on system-level compatibility aligns with a wider industry movement in which toolmakers are bundling arbors, pilots, and accessory kits to reduce field friction and improve installation predictability. Trade-channel activity further confirms this momentum. During the National Hardware Show in March 2026, exhibitors showcased HSS bi-metal hole saws, diamond brazed hole saws, TCT hole cutters for wood, and door lock installation kits tailored for wood substrates, signaling broad category diversification across trade audiences. In February 2026, Sydney Tools expanded its stocking strategy to cover the largest hole saw range across every size requirement, deliberately aggregating top-tier brands for professional and industrial users. These distribution and exhibition patterns illustrate how channel breadth and SKU completeness are increasingly becoming competitive variables alongside raw product performance.
Operational Innovation and Field Adoption
Innovation on the ground is also reshaping adoption pathways. In January 2026, VCG Construction LLC released an instructional tutorial demonstrating a stacked hole saw technique using the Spyder Rapid Core Eject system for enlarging holes without a jig. This type of field-driven technique sharing highlights how accessory ecosystems and core-ejection mechanics are reducing setup time and expanding practical use cases beyond standard drilling. Alongside product demonstrations, September 2025 saw Morse Cutting Tools formally launch its impact hole saw line for thin metal cutting, emphasizing quick-change sizing and quarter-inch impact shanks—an indication that impact-tool compatibility is becoming a decisive factor in metal fabrication and maintenance segments. Collectively, these events suggest that market momentum is being reinforced not only by end-user spending but also by the broadening of practical techniques and accessory-enabled efficiency gains.
Market Dynamics Shaped by Materials, Standards, and Infrastructure Specifications
The operational environment for hole saws is being shaped by intersecting forces across raw material science, regulatory specification, and public works contracting. At the material level, hole saw performance is anchored in high-speed steel and HSS-Co grades, which deliver the cutting endurance and thermal resilience required for sustained metal and wood applications. This material foundation directly influences product longevity, replacement cycles, and total cost of ownership, making grade selection a strategic variable for both manufacturers and specification writers.
On the regulatory and specification side, hole saw usage is increasingly documented within formal construction and utility frameworks. Cutting requirements for sewer mains, pipe fittings, and pavement now commonly reference ANSI standards and mandate precise diameter control, embedding hole saw methods into compliance-driven workflows. In utility projects, hole saw cutting is specified for service taps on DIP water mains and RCP pipes to ensure accurate sizing and prevent damage during installation. Stormwater basin and main construction contracts similarly incorporate hole saw applications for precise utility connections and concrete or metal hole cutting. Delaware DOT standard specifications have also recognized hole saw methods as an approved approach for sewer main service taps. These specification linkages indicate that hole saw adoption is not merely a function of price and availability; it is increasingly tied to documented performance, dimensional accuracy, and compliance assurance within public and private infrastructure work.
Strategic Priorities for 2026 and Beyond
For organizations operating in or adjacent to the hole saw value chain, the strategic posture for 2026 must be anchored in three interlocking priorities. First, product portfolios must be evaluated against application reality rather than legacy categorization. The divergence between bi-metal durability, carbide aggression, diamond precision, and carbon steel cost-efficiency is not merely a technical detail; it is a segmentation driver that influences procurement behavior across commercial and domestic end users, and across dry and wet drilling contexts. Understanding which product families are gaining share under which operating conditions is essential for both inventory planning and new product investment.
Second, competitive strategy must account for the concentrated nature of the market. With share heavily clustered among a small group of dominant players, market entry or share expansion requires clear differentiation in warranty terms, shank compatibility, tooth geometry, or system bundling. Companies that rely on undifferentiated SKU proliferation risk being outflanked by competitors who embed reliability features, speed improvements, and accessory ecosystems into defensible product platforms.
Worldwide Wire Saw Market
Third, go-to-market execution should align with specification-driven demand. As hole saw methods become more explicitly referenced in municipal, utility, and construction specifications, the ability to demonstrate compliance, dimensional accuracy, and consistent performance will increasingly influence bidding outcomes and procurement lists. Manufacturers, distributors, and service providers that prepare specification-grade documentation, application guidance, and trade-channel visibility will be better positioned to convert technical requirements into repeatable purchasing behavior.
What the Full Analysis Delivers
This report is designed to move beyond surface-level market sizing and provide a decision-grade blueprint for navigating the hole saw sector through 2032. It integrates historical performance, forward-looking forecasts, segmentation logic across product type, application method, end-user profile, and regional behavior, and a structured competitive assessment of the companies shaping current market dynamics. It also captures the material, regulatory, and operational signals that are influencing specification language, procurement patterns, and product development priorities in real time. The objective is to give executives a clear line of sight into where growth is materializing, which product architectures are gaining traction, and how market concentration is shaping competitive whitespace.
The complete research package unpacks these themes with the granularity required for strategic planning, investment justification, and channel execution. For leaders who need precise segmentation insights, competitive benchmarking, and application-specific demand mapping to support 2026 decision-making, the full report provides the depth and structure necessary to convert market signals into executable strategy.
Hole Saw Market
For detailed analysis of this topic, please visit the official page: Hole Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com