

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Loan Origination Software Market Hits $215M in 2025, Projected 11.8% CAGR Through 2032

Strategic Intelligence in the Loan Origination Software Market: A 2026 Decision-Maker's Guide
As financial institutions navigate a landscape defined by rapid technological adoption, evolving regulatory frameworks, and shifting borrower expectations, the loan origination software (LOS) market has emerged as a critical battleground for strategic investment. The period between 2020 and 2025 demonstrated remarkable resilience and expansion, with industry valuations climbing from approximately $163.15 million to a projected $215.0 million. Looking ahead, the forecast horizon through 2032 signals sustained momentum, driven by an anticipated compound annual growth rate that underscores the sector's transformation from a back-office utility to a frontline competitive differentiator.
At PW Consulting, we recognize that enterprise leaders require more than surface-level projections to allocate capital, prioritize digital transformation roadmaps, or evaluate vendor partnerships. This introduction previews the comprehensive market research report designed to equip decision-makers with actionable, data-backed intelligence for 2026 and beyond. By illuminating macro trajectories, competitive dynamics, and regulatory pressures without exposing granular segmentation figures, we aim to demonstrate the report's strategic utility while preserving the proprietary depth that comprehensive analysis delivers. Readers seeking precise regional valuations, type-specific adoption curves, or application-split revenue allocations are invited to access the full publication through our official research portal.
Navigating the 2026–2032 Market Trajectory
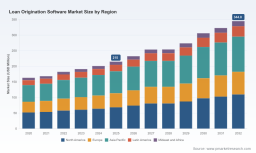
The historical performance of the LOS market from 2020 through 2025 reveals a consistent upward arc, reflecting both post-pandemic digitization acceleration and sustained institutional demand for streamlined lending workflows. Starting at $163.15 million in 2020, the market advanced through successive expansions, crossing $182.44 million in 2022, $191.12 million in 2023, and $201.06 million in 2024 before reaching $215.0 million in the base year of 2025. This trajectory reflects a sector that has successfully transitioned from reactive crisis adaptation to proactive infrastructure modernization.
The forward-looking forecast period, spanning 2026 to 2032, projects continued expansion with a compound annual growth rate of 11.8 percent. By 2026, market valuations are positioned at approximately $232.48 million, with subsequent annual increments carrying the sector toward $253.84 million in 2027, $254.07 million in 2028, $273.7 million in 2029, $306.1 million in 2030, $322.92 million in 2031, and an eventual peak of $344.8 million in 2032. This growth path is not merely a function of incremental adoption; it reflects structural shifts in how financial institutions approach origination efficiency, borrower engagement, and compliance readiness.
It is important to emphasize that these figures represent aggregated market assessments. The report deliberately maintains an elevated analytical perspective at this stage, directing readers toward the full publication for detailed breakdowns by geographic region, deployment type, and end-user application. Such granularity remains essential for segmentation-specific strategy development, but embedding precise regional or sectoral percentages in this overview would diminish the strategic emphasis on macro-is trends, competitive positioning, and operational dynamics that define the broader market narrative.
Operational Transformation and Industry Dynamics
The contemporary LOS market is being reshaped by intersecting forces that extend well beyond software procurement cycles. Financial institutions are no longer evaluating origination platforms solely through the lens of feature parity; they are assessing how effectively these systems integrate artificial intelligence, streamline compliance workflows, and adapt to evolving supervisory expectations. Our research synthesizes multiple operational imperatives that demand executive attention in 2026.
AI-Driven Processing Efficiencies
Automation has shifted from a desirable attribute to an operational necessity. Industry market data from 2026 indicates that AI-powered loan origination systems are capable of reducing underwriting processing time by approximately 75 percent, compressing workflows that traditionally required an hour into roughly fifteen minutes. This compression does more than accelerate turnaround; it fundamentally alters capacity planning, human capital allocation, and the economics of loan servicing. Institutions that leverage intelligent origination platforms are increasingly positioned to scale volume without proportionally expanding operational headcount, while simultaneously improving consistency in initial risk assessments.
Regulatory Pressures Reshaping Compliance Architecture
The regulatory environment is entering a phase of heightened scrutiny, demanding that origination software align with both current mandates and anticipated enforcement timelines. The Consumer Financial Protection Bureau extended the Equal Credit Opportunity Act Section 1071 compliance deadline to January 1, 2028, for covered small-business lending transactions, granting institutions additional runway but simultaneously elevating the urgency of workflow integration for data collection and reporting. This extension does not diminish the requirement for robust origination tracking; rather, it magnifies the strategic value of platforms that can embed Section 1071 readiness into existing origination pipelines without disrupting core lending operations.
Concurrent regulatory developments further complicate the landscape. The National Credit Union Administration's 2026 Supervisory Priorities mandate enhanced credit risk review for federally insured credit unions, with explicit attention to loan underwriting practices. As credit unions seek to demonstrate strengthened oversight, origination systems that provide granular workflow transparency, audit trails, and configurable risk-review checkpoints are gaining strategic relevance. Simultaneously, the Office of the Comptroller of the Currency has identified geopolitical tensions and sanctions as factors increasing compliance burdens on anti-money laundering and sanctions screening systems for banking institutions. These dynamics position origination platforms with embedded compliance frameworks and adaptable screening workflows as critical risk-management enablers rather than mere transaction processors.
The report dedicates extensive analysis to these regulatory intersections, providing decision-makers with structured evaluations of how vendor solutions address Section 1071 data architecture, credit union supervisory alignment, and cross-border compliance screening. Rather than presenting fragmented compliance checklists, the research frames regulatory readiness as a competitive capability, mapping vendor capabilities against the specific operational obligations that define institutional exposure in 2026 and subsequent enforcement waves.
Competitive Landscape: Leading Vendors and Strategic Positioning
The LOS market is characterized by a concentrated yet dynamic competitive ecosystem. Market concentration metrics indicate that the top three participants command approximately 24.6 percent of total market revenue, while the top five collectively represent roughly 26.2 percent. This relatively moderate concentration suggests that while established vendors maintain meaningful share, the market remains accessible to agile innovators and specialized providers that differentiate through workflow automation, AI integration, and vertical-specific compliance tooling. Our research evaluates a curated set of core enterprises whose offerings illustrate the breadth of strategic approaches shaping the market.
Loan Origination Software Market
Blend Labs, Inc., headquartered in San Francisco, California, represents a prominent voice in AI-powered lending infrastructure. Its Intelligent Origination platform extends across mortgages, consumer loans, and deposit products, positioning the company at the intersection of digital lending and real-time decision automation. In October 2025, Blend announced its Intelligent Origination AI system, emphasizing real-time loan decisioning and workflow automation, a move that signals the vendor's commitment to embedding predictive analytics directly into origination pathways.
LendFoundry, based in Irvine, California, competes through a cloud-native loan origination system that integrates AI-driven credit evaluation, compliance management, analytics, and more than eighty integrations. This breadth of connectivity reflects a market trend in which origination platforms are increasingly expected to function as orchestration layers rather than standalone applications, connecting underwriting engines, third-party data providers, and downstream servicing workflows within unified environments.
MeridianLink continues to influence the mortgage and consumer lending segments through cloud-native origination software that emphasizes workflow automation and analyst insights. In December 2025, the company released enhancements to its MeridianLink Mortgage platform, focusing on improved performance and expanded automation capabilities. These iterative product updates illustrate the competitive reality that sustained market relevance requires continuous delivery of performance optimizations alongside advanced automation features.
Calyx Software maintains a distinct presence in the mortgage broker and lender sector through a point-of-sale loan origination platform that spans prequalification through closing while incorporating compliance tooling. Its specialized orientation reflects a broader industry pattern in which certain vendors achieve differentiation by tightly aligning their product architecture with the operational cadence of mortgage origination workflows, including document collection, condition management, and closing coordination.
Finastra enters the competitive conversation through Originate, a unified cloud-based platform designed to address mortgages, loans, and deposit products within a single operating environment. Automated workflows and real-time decisioning form the core of its value proposition, aligning with institutional preferences for consolidation and cross-product consistency. Similarly, ICE Mortgage Technology's Encompass end-to-end mortgage origination platform integrates built-in compliance and API extensibility, reinforcing the market expectation that origination systems must offer both regulatory resilience and technical flexibility for institutions seeking to connect with external data sources and downstream systems.
nCino distinguishes its positioning through a platform that spans commercial, consumer, and small business loan origination, supported by artificial intelligence and automation. Its coverage across multiple lending verticals underscores the growing demand for origination architectures that can accommodate diverse product types without fragmenting underwriting logic or compliance monitoring. TurnKey Lender pursues a parallel strategy through an AI-powered platform featuring configurable workflows, a decisioning engine, and end-to-end automation, appealing to institutions that seek rapid deployment alongside substantial customization latitude.
Floify contributes a digital mortgage point-of-sale origination offering that emphasizes AI automation and configurable loan paths, addressing the front-end borrower experience alongside backend processing requirements. Collectively, these vendors illustrate the market's multidimensional character, where competitive advantage is increasingly derived from the integration of automation, compliance readiness, and user experience rather than standalone transaction functionality.
The full report extends this competitive analysis with detailed capability mapping, recent development tracking, and strategic positioning assessments that help procurement teams, product leaders, and investment analysts evaluate vendor fit against institutional priorities. As evidenced by the documented product launches and updates from Blend Labs and MeridianLink, the competitive field remains highly responsive, and our research captures the cadence of innovation that shapes purchase decisions throughout the forecast window.
Inside the Research Report: Operational Content and Analytical Depth
The comprehensive research publication is structured to translate macro market intelligence into practical, decision-oriented content. Beyond the aggregate revenue trajectory and CAGR context summarized in this preview, the report provides a systematically organized examination of the factors that determine origination software success in 2026 and the subsequent years through 2032. Readers will find detailed evaluations of deployment architectures, workflow automation maturity, AI integration scope, compliance alignment, and integration extensibility across the vendor landscape.
The analysis incorporates recent market developments with precise chronological tracking, enabling stakeholders to assess the pace of innovation and its implications for procurement timing. Product launch activity, enhancement releases, and strategic announcements are correlated with market demand signals, regulatory milestones, and operational efficiency benchmarks to provide a multidimensional view of competitive momentum. This approach helps institutions avoid costly procurement misalignment, particularly when vendor roadmaps and institutional compliance deadlines operate on divergent timelines.
Importantly, the report preserves rigorous analytical separation between high-level market characterization and segment-specific intelligence. While this article intentionally refrains from enumerating regional revenue splits, type-based deployment shares, or application-level market allocations, the full publication delivers those dimensions with methodological clarity. Decision-makers evaluating regional expansion strategies, cloud-versus-on-premise deployment economics, or segment-specific vendor suitability will find the segmentation breakdowns structured to support localized, application-aware investment logic rather than generic market commentary.
Real Estate Software Market
Strategic Imperatives for 2026 Enterprise Decision-Making
Entering 2026, financial institutions face a convergence of operational, regulatory, and technological demands that place origination software at the center of strategic planning. The capacity to compress underwriting timelines through AI-driven automation, align workflows with Section 1071 data requirements, satisfy credit union supervisory expectations, and maintain robust sanctions and anti-money laundering screening processes increasingly defines institutional agility. Procurement and technology leaders must therefore evaluate LOS providers not merely on feature checklists but on their ability to serve as adaptive compliance and efficiency engines within broader lending operations.
The research underscores that competitive differentiation in the LOS market will continue to accrue to organizations that couple procurement decisions with clear operational objectives: processing speed, audit readiness, cross-product consistency, integration flexibility, and borrower-facing digital engagement. Institutions that delay strategic vendor evaluation risk falling behind peers who are already operationalizing automation capabilities and embedding regulatory preparedness into origination workflows. Conversely, those that approach the market with structured, intelligence-driven assessments can align technology investment with measurable operational outcomes and compliance resilience.
This article serves as a strategic preview, demonstrating the analytical rigor and market coverage embedded in the full PW Consulting research publication. To access precise segmentation data, detailed vendor capability matrices, regional market breakdowns, and application-specific adoption insights that inform capital allocation, vendor selection, and product strategy, we invite you to visit the official research page and secure the complete market study. The full report provides the granularity necessary to convert macro intelligence into executable strategy for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Loan Origination Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com