

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrostatic Chucks Market Hits $208.7M in 2025, 8.45% CAGR to 2032

Strategic Intelligence for the Semiconductor Ecosystem: Navigating the 2026 Electrostatic Chucks for Wafer Market
Executive Overview
The electrostatic chuck market stands at a critical inflection point as semiconductor manufacturing enters the era of sub-3nm nodes and advanced packaging. As a senior strategic advisor at PW Consulting, I have observed how critical wafer handling and thermal management components have become to overall fab productivity. This market research report delivers the comprehensive intelligence required to navigate the complexities of 2026 and beyond, providing decision-makers with the analytical framework needed to allocate capital, secure supply chains, and position for sustained growth.
Our analysis traces the market trajectory from 2020 through 2032, capturing both the historical resilience and the projected acceleration that define this sector. The research is structured to give executives, procurement leaders, and technology strategists the actionable insights necessary to make confident moves in a landscape shaped by technological disruption, regulatory shifts, and intensifying competitive dynamics.
Market Trajectory and Growth Dynamics
The electrostatic chucks for wafer market has demonstrated consistent expansion over the past half-decade, driven by the relentless scaling of semiconductor fabrication and the increasing integration of advanced materials in wafer processing equipment. Historical data reveals a market that grew from approximately 139.2 million USD in 2020 to 208.7 million USD in 2025, reflecting a compound annual growth rate of 8.45 percent across the forecast horizon extending to 2032.
This growth trajectory is not merely a function of volume expansion. It reflects a structural transformation in how semiconductor manufacturers approach wafer clamping, thermal dissipation, and process uniformity. As foundries and logic manufacturers push into Angstrom-class architectures, the electrostatic chuck evolves from a passive handling component into an active process enabler. The market size is projected to reach 367.2 million USD by 2032, indicating sustained demand that will reward organizations capable of aligning their product development and supply chain strategies with this trajectory.
Several macro forces underpin this expansion. The global proliferation of artificial intelligence workloads, the automotive sector's migration toward advanced driver-assistance systems, and the expanding footprint of high-performance computing all contribute to wafer fabrication volumes that place unprecedented demands on chuck technology. Furthermore, the transition toward 3D NAND stacking and gate-all-around transistor architectures requires electrostatic chucks with multi-zone temperature control, enhanced thermal stability, and predictable clamping forces across larger substrate diameters.
Technology Segmentation and Application Landscape
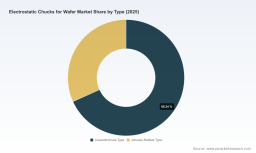
Electrostatic chucks function as indispensable interfaces between wafers and processing tools, leveraging electrostatic forces to secure substrates during etching, deposition, and other critical fabrication steps. The market encompasses two primary technology variants, each addressing distinct process requirements. Coulomb-type chucks dominate segments where precise voltage-controlled clamping and uniform heat transfer are paramount, while Johnsen-Rahbek-type solutions serve applications demanding higher holding forces and simplified drive electronics.
The application landscape reflects the breadth of modern semiconductor manufacturing. Leading semiconductor fabrication operations represent the largest demand center, where chucks must deliver repeatable performance across high-volume production lines. Simultaneously, the MEMS and sensors segment continues to expand as consumer electronics, medical devices, and industrial sensing applications require increasingly sophisticated microfabrication processes. Additional application areas contribute to market diversification, encompassing display manufacturing, advanced packaging, and specialty material processing.
Material selection and ceramic formulation remain central to performance differentiation. High-purity aluminum nitride has emerged as a preferred substrate material for its thermal conductivity and electrical insulation properties, though supply concentration introduces strategic considerations that procurement teams must evaluate carefully. Rare earth doping elements enhance thermal characteristics but introduce price volatility that can impact cost structures across multiple quarters. Understanding these material dependencies is essential for organizations seeking to de-risk their supply chains while maintaining performance standards.
Competitive Landscape and Strategic Positioning
The electrostatic chucks market exhibits a highly concentrated competitive structure, with the top three firms commanding approximately 69.5 percent of total revenue and the top five entities controlling 81.0 percent. This concentration reflects the technical barriers to entry, the capital intensity of advanced ceramic manufacturing, and the long qualification cycles associated with semiconductor equipment components. Organizations operating in this space benefit from deep customer relationships, proprietary material formulations, and established service networks that create substantial switching costs for end users.
Leading participants span North America, Japan, and Europe, each bringing distinct technological strengths and market access advantages. Applied Materials and Lam Research represent the U.S. equipment ecosystem, offering electrostatic chuck solutions integrated with broader wafer processing platforms and leveraging extensive customer installations to drive recurring demand. Japanese manufacturers including Shinko Electric, Kyocera, NGK Insulators, TOTO, Sumitomo Osaka Cement, and NTK CERATEC contribute specialized ceramic expertise and precision engineering capabilities that align with the exacting requirements of advanced nodes.
Entry and expansion strategies also involve regional players and specialty suppliers. II-VI M Cubed, Entegris, and Calitech provide complementary product portfolios and material solutions, while Beijing U-PRECISION TECH reflects the growing capability of Chinese domestic manufacturers to serve local fabrication capacity. Competitive differentiation increasingly hinges on multi-zone thermal control, AI-enabled monitoring, and the ability to deliver chucks that meet evolving process specifications without compromising yield.
Recent Industry Developments and Strategic Implications
Recent corporate activities illustrate how the competitive landscape is evolving in response to technology roadmaps and market pressures. In March 2025, Tokyo Electron Limited announced the launch of a new RF electrostatic chuck optimized for 3nm node fabrication, emphasizing enhanced thermal stability and process uniformity. This product introduction signals the industry's focus on chuck performance as a direct contributor to process window expansion and yield improvement at advanced nodes.
Electrostatic Chucks for Wafer Market
Semiconductor Electrostatic Chuck Market
Applied Materials completed an acquisition in February 2025, absorbing a startup specializing in AI-enabled wafer handling sensors. The strategic intent is clear: embedding predictive analytics into electrostatic chuck systems enables real-time monitoring, fault detection, and adaptive control that can reduce downtime and improve process consistency. Organizations that integrate sensor data with chuck performance will gain operational advantages that extend beyond hardware specifications.
Partnership activity further demonstrates the collaborative nature of innovation in this sector. In January 2025, CMC Materials partnered with a leading European semiconductor manufacturer to develop eco-friendly, high-performance ceramic electrostatic chucks. Sustainability considerations are becoming embedded in product development cycles, and manufacturers that proactively address material sourcing, energy efficiency, and end-of-life considerations will strengthen their positions with customers operating under environmental and regulatory mandates.
Regulatory Environment and Supply Chain Considerations
Strategic decision-making in this market must account for an evolving regulatory landscape. Export controls introduced by the U.S. Department of Commerce Bureau of Industry and Security impose licensing requirements on advanced computing items with electrostatic chuck features, including products with twenty or more individually controllable variable temperature elements when destined for specific countries. These controls shape market access, influence product design choices, and require compliance infrastructure that can add complexity to international sales strategies.
Supply chain resilience has emerged as a parallel imperative. High-purity aluminum nitride powder exhibits significant supplier concentration, with approximately 72 percent of global supply originating from three vendors. Geopolitical tensions have introduced delivery delays ranging from 30 to 45 days, prompting manufacturers to carry six to eight months of safety stock. Rare earth doping elements for enhanced thermal properties have experienced quarterly price volatility of roughly 18 percent since 2022, adding cost unpredictability that must be managed through hedging strategies, long-term agreements, and material substitution research.
Regional dynamics further complicate supply chain planning. U.S.-China technology restrictions create uncertainty for manufacturers serving the Chinese domestic market, which represented approximately 20 percent of global semiconductor equipment spending in 2024. At the same time, incentive programs in the United States and European Union encourage localized production of electrostatic chucks, compelling manufacturers to establish near-fab service hubs and accelerating industry consolidation. Organizations that proactively diversify sourcing, localize service capabilities, and align product portfolios with regional requirements will be better positioned to capture growth while mitigating disruption risk.
What This Report Delivers for 2026 Decision-Making
PW Consulting's Electrostatic Chucks for Wafer Market research is designed to translate market complexity into decision-ready intelligence. The report offers a rigorous evaluation of market size, growth rates, and segmentation dynamics, enabling executives to benchmark their strategies against observable industry movements. Detailed analysis of technology types, application requirements, and regional demand patterns supports product planning, capacity allocation, and go-to-market prioritization.
Competitive profiling extends beyond corporate descriptions to examine positioning, technological focus, and strategic moves that shape market share trajectories. Procurement and supply chain leaders will benefit from assessment of material dependencies, cost drivers, and risk factors that influence sourcing strategies. Regulatory analysis provides the context needed to navigate export controls, incentive programs, and regional compliance requirements that affect market access and operational planning.
The research also addresses forward-looking scenarios, evaluating how technology nodes, customer adoption patterns, and macroeconomic forces may influence demand through 2032. This forward perspective helps organizations anticipate inflection points, allocate R&D resources with greater precision, and prepare for competitive shifts before they materialize.
Conclusion: Positioning for Sustained Advantage
The electrostatic chucks for wafer market will continue to reward organizations that combine technical excellence with strategic agility. Growth to 367.2 million USD by 2032 is attainable, but capturing share within that outcome requires disciplined assessment of technology roadmaps, supply chain resilience, regulatory exposure, and competitive intensity. Decision-makers who ground their strategies in comprehensive market intelligence will be better equipped to navigate uncertainty, align investments with demand, and build durable advantages in a sector where performance, reliability, and responsiveness define leadership.
PW Consulting's full market research report provides the depth, granularity, and analytical rigor necessary to convert these insights into actionable plans. The complete dataset, segmentation breakdowns, competitive assessments, and region-specific dynamics are available in the detailed publication, offering the precision required to calibrate strategy for 2026 and the decade ahead.
For detailed analysis of this topic, please visit the official page: Electrostatic Chucks for Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com