

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: All-Solid-State Battery Market Hits $9.69B in 2025, Forecasts 13.2% CAGR to $23.08B by 2032

Navigating the All-Solid-State Battery Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global energy storage landscape is undergoing a structural transformation. As the industry moves beyond the mature lithium-ion paradigm, all-solid-state battery technology stands at a critical inflection point. The transition from laboratory validation to pilot production and early commercialization is no longer a theoretical horizon—it is actively reshaping competitive dynamics, supply chain architectures, and capital allocation strategies. For executives, investors, and policy stakeholders operating in 2026, understanding where the market stands, how it will compound, and which operational bottlenecks will dictate success is not optional. It is a prerequisite for informed decision-making.
This insight introduces PW Consulting's latest all-solid-state battery market research, a comprehensive analysis designed to translate complex technological trajectories into actionable strategic frameworks. The study is structured to support enterprise planning across technology roadmapping, regional expansion, partnership scouting, and risk mitigation. What follows is a demonstration of the analytical rigor embedded in the full report, alongside a clear outline of the operational intelligence it delivers.
The Trajectory: From Steady Base to Accelerated Scale
Historical data from 2020 through 2025 reveals a market that has consistently expanded, even as technological maturity and manufacturing readiness evolved at different paces across regions and developer categories. The baseline positioning in 2025 reflects aUSD-denominated market size that underscores both the growing commercial interest and the tangible progress in cell-level validation and early pilot lines. Looking forward, the forecast window spanning 2026 to 2032 projects a compound annual growth rate of 13.2 percent, with the market expected to surpass the ten-figure milestone in the near term and continue its upward compounding trajectory toward the end of the forecast period.
These macro-level figures are more than retrospective benchmarks. They signal the pace at which scaled adoption, OEM qualification cycles, and electrolyte supply chain maturation will converge. The growth curve implies that companies positioning themselves now—whether through proprietary cell architectures, electrolyte material scaling, or manufacturing partnerships—will face a market that rewards early alignment with gigawatt-scale production pathways and standardized testing protocols. The full research unpacks the drivers behind this trajectory, mapping the interplay between energy density breakthroughs, cost curve compression, and the gradual replacement of liquid electrolyte systems across priority application segments.
What the Report Delivers: Operational Intelligence Beyond Top-Line Numbers
PW Consulting's all-solid-state battery study is engineered for practitioners who must translate market signals into execution plans. The report goes beyond aggregated market sizing to provide a multi-dimensional operational lens. Core components include:
Solid State Batteries Market
- Technology segmentation mapping that dissects electrolyte material families, anode configurations, and cell architecture pathways, linking each technical route to manufacturing readiness, energy density ceilings, and cost structure implications.
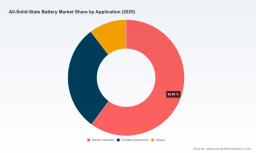
- Application pathway analysis that evaluates demand evolution across electric mobility platforms, portable electronics, and specialized industrial use cases, highlighting qualification timelines, pack-level integration considerations, and difference in adoption pacing.
- Regional dynamics and deployment logic that contextualizes demand concentration, manufacturing footprint development, and policy environments without reducing complex ecosystems to static snapshots.
- Supply chain and infrastructure diagnostics that examine raw material throughput requirements, electrolyte production scaling challenges, roll-to-roll manufacturing economics, and the bottlenecks that will define early gigafactory execution.
- Competitive benchmarking and developer profiling that tracks active players across startup, joint venture, and incumbent OEM-affiliated models, with emphasis on pilot line status, sampling milestones, licensing strategies, and partnership ecosystems.
- Regulatory and standardization watchpoints that monitor evolving testing protocols, safety guideline development, and national standard releases that will influence certification pathways and market access timelines.
Each section is designed to support scenario planning. Readers will find structured comparisons that help evaluate which technical routes align with specific product roadmaps, which regional manufacturing ecosystems offer the most tractable scale-up pathways, and how developer types—from electrolyte material specialists to integrated cell manufacturers—are positioning for licensing, joint production, or standalone commercialization.
Competitive Landscape: Divergent Models, Converging Timelines
The all-solid-state battery ecosystem in 2026 is defined by a diversity of development models and a simultaneous push toward production readiness. The competitive field spans U.S.-based cell developers, electrolyte material suppliers, European joint ventures, Asian integrated manufacturers, and large incumbent players advancing pilot programs with targeted commercialization dates.
In the United States, several organizations are advancing parallel commercialization tracks. QuantumScape has operated with a clear focus on high-energy-density lithium-metal anodes paired with solid electrolyte architectures, and its recent inauguration of the Eagle Line automated pilot production facility in San Jose marks a transition toward OEM customer sampling and gigawatt-scale licensing. Nearby, Ampcera has concentrated on solid-state electrolyte materials, scaling sulfide electrolyte production in Tucson to support downstream cell development. Solid Power has pursued a sulfide-electrolyte route with multi-layer cell production on continuous roll-to-roll lines, targeting automotive OEM relationships that include BMW and Ford. These parallel tracks demonstrate how the U.S. ecosystem is differentiating between integrated cell development, material supply, and roll-to-roll manufacturing capabilities.
Europe's landscape reflects coordinated industrial ambition. Argylium, formed as a joint venture among Syensqo, Axens, and IFPEN, is focused on industrial production and commercialization of sulfide solid electrolytes, signaling a push to secure European electrolyte supply capacity. Meanwhile, ProLogium has advanced oxide ceramic electrolyte-based all-solid-state batteries with roll-to-roll manufacturing progress and gigafactory partnerships, including its collaboration with Mercedes-Benz Marseille. Ilika continues to develop all-solid-state technology with a pilot production focus for electric mobility applications, illustrating a more targeted approach to near-term validation.
In Asia, the pace of milestone achievement has accelerated. Greater Bay Technology, backed by GAC Group, rolled out its first A-sample cells using composite electrolytes, achieving energy density ranges that place it in a high-performance cohort and targeting GWh-scale mass production and vehicle installation. Samsung SDI is progressing with its SolidStack branding, targeting mass production in the second half of 2027 alongside partnerships for EVs and industrial applications. Toyota has received Japanese METI production approval and is targeting pilot production in 2026, leveraging a partnership with Idemitsu Kosan for mass-produced sulfide electrolytes. These developments underscore how Asian developers are compressing the timeline from cell validation to pilot and early mass-production planning.
The report profiles these and other active participants with structured operational summaries, tracking not only headquarters and public-facing positioning but also the concrete milestones that indicate where each organization sits on the commercialization curve. Recent events—such as automated pilot line inaugurations, A-sample cell rollouts, joint venture formations, and gigafactory partnerships—are integrated into a dynamic competitive map that helps readers assess who is moving from demonstration to deployment, and at what scale.
Market Dynamics: Standards, Funding, and Infrastructure Friction
The trajectory of all-solid-state battery commercialization is being shaped as much by regulatory and infrastructure developments as by cell-level innovation. Standardization activity is expanding across multiple forums. The International Electrotechnical Commission's Technical Committee 21 has broadened its work to develop unified standards and testing protocols for solid-state battery technologies, including updates to the IEC 62660 series. These efforts matter because harmonized testing and certification pathways will directly influence OEM qualification speed, cross-border market access, and investor confidence in production readiness.
At the national level, China plans to release its first national standard for solid-state EV batteries, defining distinctions among liquid, semi-solid, and all-solid-state packs. This type of classification framework can reset competitive expectations by clarifying which technologies fall into which regulatory categories, influencing both procurement specifications and consumer-facing positioning. In the United States, the Department of Energy's Advanced Materials and Manufacturing Technologies Office has awarded SBIR Phase II funding to multiple small businesses focused on innovative manufacturing of next-generation solid-state batteries, signaling public-sector support for manufacturing process innovation. Preliminary safety testing guidelines are also being established by the Department of Energy and the Consumer Product Safety Commission, even as full standards remain under development.
Infrastructure and raw material dynamics introduce additional strategic considerations. Solid-state batteries consume substantial quantities of solid electrolytes per unit of production capacity, and the scaling of electrolyte manufacturing, precursor sourcing, and specialized production infrastructure represents a material constraint that will shape early gigafactory economics. These supply-side realities interact with roll-to-roll processing requirements, cell stacking precision, and quality control demands to create a set of execution risks that are often underweighted in technology-only assessments. The full study integrates these dynamics into a cohesive view of where friction will emerge and how different developer models are preparing to address it.
All-Solid-State Battery Market
Why This Research Matters for 2026 Strategy
Entering 2026, the all-solid-state battery market is transitioning from narrative-driven anticipation to milestone-driven evaluation. Enterprises that depend on battery technology for product differentiation, cost structure, or sustainability positioning need more than headlines. They need a structured understanding of which technical pathways are reaching pilot readiness, which electrolyte and cell architectures are attracting OEM sampling and licensing interest, where regional manufacturing ecosystems are forming, and how standardization and safety guidelines will alter qualification timelines.
The strategic value of this research lies in its capacity to support concrete decisions. Technology teams can use the segmentation and developer profiling to benchmark internal roadmaps against external milestones. Supply chain and procurement leaders can anticipate electrolyte capacity constraints and manufacturing infrastructure requirements as they plan for scale-up. Corporate development and partnership teams can identify which organizations are moving from demonstration to pilot production, which joint ventures are consolidating electrolyte supply, and which gigafactory collaborations signal near-term commercialization intent. Investors and advisors can use the macro trajectory, competitive mapping, and regulatory watchpoints to calibrate expectations around adoption pacing and market concentration.
Market concentration data included in the study indicates that the top three participants account for a substantial share of the evaluated landscape, while the top five extend that footprint further. This concentration pattern, when read alongside the diversity of development models and the ongoing arrival of new milestones, suggests a market that is simultaneously consolidating around capable players and still open to new entrants with differentiated technical or manufacturing advantages. Understanding where concentration ends and white space remains is one of the decisive questions the report is built to answer.
What You Will Gain From the Full Study
The complete PW Consulting all-solid-state battery market research delivers a decision-grade intelligence package. It connects historical expansion and forward-looking growth projections to the operational realities of electrolyte scaling, cell architecture selection, application qualification cycles, and regional manufacturing development. It profiles active developers with milestone-level tracking, integrates regulatory and standardization developments into commercial timing assessments, and highlights the raw material and infrastructure dynamics that will influence early production economics.
Crucially, the report preserves analytical depth without reducing the market to static divisions. Regional, type-based, and application-based segmentation is presented with the contextual interpretation required for strategy work, allowing readers to understand where demand, manufacturing, and policy pressures intersect. The goal is not simply to enumerate the landscape, but to equip decision-makers with the frameworks needed to prioritize investments, time partnerships, and manage execution risk in a market that is moving quickly from pilot lines to early commercial pathways.
For executives and strategy teams operating in 2026, the window for informed positioning is narrow and valuable. The all-solid-state battery market will not wait for organizations to catch up once production standards crystallize and OEM qualification cycles accelerate. The full research provides the structured intelligence required to act with confidence—translating growth projections, competitive milestones, and regulatory developments into a clear strategic plan. We invite you to access the complete report for the detailed segmentation data, developer profiles, regional deployment analysis, and scenario frameworks that will support your 2026 and beyond planning.
For detailed analysis of this topic, please visit the official page: All-Solid-State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com