

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AGV Market Reaches $215M in 2025, Projected 8.7% CAGR Through 2032

# Navigating the Automated Future: Strategic Insights into the 2026 AGV Market Landscape
Introduction: The Imperative for Automated Mobility
The industrial landscape is undergoing a seismic shift characterized by the rapid integration of Automated Guided Vehicles (AGVs) into core operational workflows. As we move through 2026, the transition from manual material handling to autonomous logistics is no longer merely a technological upgrade but a strategic necessity for maintaining competitiveness. PW Consulting's latest market research provides a comprehensive evaluation of this evolving sector, offering enterprise leaders the clarity needed to navigate investment decisions, supply chain restructuring, and technology adoption strategies. This report serves as a critical tool for stakeholders aiming to capitalize on the momentum driving the AGV market. By analyzing historical trajectories and forecasting future growth, we provide a roadmap for organizations seeking to optimize efficiency, reduce labor dependency, and enhance safety within industrial environments. The following insights outline the macro-economic forces shaping the industry and highlight the competitive dynamics that will define the next decade.
Macro-Economic Trajectory and Market Valuation
The AGV market has demonstrated resilient growth over the past half-decade, transitioning from a niche automation solution to a cornerstone of modern logistics infrastructure. Our analysis covers historical performance from 2020 through 2025, establishing a robust baseline for forward-looking projections spanning 2026 to 2032. This longitudinal view allows stakeholders to understand the velocity of adoption and the scaling potential of autonomous vehicle technologies across various industrial verticals.
Historical data indicates a steady expansion in market valuation, with revenue climbing consistently as industries accelerate their digital transformation initiatives. The market has evolved from a baseline of significant investment in 2020 to a substantially larger valuation by the base year of 2025. This growth trajectory reflects the increasing normalization of automation in warehousing, manufacturing, and distribution centers. The compound annual growth rate observed over the forecast period underscores the sustained demand for automated solutions, driven by the need for operational continuity and precision in material handling.
Worldwide Automatic Guided Vehicle Sensing System Market
Looking ahead, the forecast period reveals a compelling expansion story. The market is projected to continue its upward momentum, reaching new valuation milestones by 2032. This growth is not linear but is influenced by technological breakthroughs, regulatory shifts, and changing labor dynamics. For strategic planners, understanding the magnitude of this growth is essential for capital allocation. The data suggests that early adopters and those who scale their AGV fleets in alignment with market expansion will secure significant operational advantages over competitors relying on legacy manual processes.
Currency stability and revenue measurement in USD Millions provide a standardized framework for global comparison, ensuring that investors and corporate strategists can assess opportunities without distortion from volatile exchange rates. This standardization is particularly vital for multinational corporations evaluating deployment strategies across different geographic zones. The consistency in reporting allows for a clearer assessment of return on investment and total cost of ownership when comparing AGV solutions against traditional material handling equipment.
Strategic Drivers and Key Industry Dynamics
Several converging factors are propelling the AGV market forward in 2026. These drivers are not isolated incidents but represent structural shifts in the global industrial economy. Understanding these dynamics is crucial for any organization planning to integrate autonomous vehicles into their operational framework.
-
Labor Market Constraints: Persistent labor shortages in warehouses and manufacturing facilities are accelerating AGV adoption. Organizations are increasingly reducing reliance on human operators for repetitive tasks, particularly in e-commerce fulfillment and automotive assembly lines. This shift is not just about cost reduction but about ensuring operational resilience in the face of fluctuating labor availability.
-
Regulatory Compliance: Safety remains paramount in the deployment of industrial automation. Compliance with ISO 3691-4 for the safety of driverless industrial trucks and ISO 13849-2015 for performance levels is mandatory for AGV systems in industrial environments. Navigating these regulatory frameworks requires sophisticated engineering and rigorous testing, which influences both vendor selection and implementation timelines.
-
Raw Material Supply Chains: Lithium-ion batteries and specialized sensors represent the primary raw material costs in AGVs. Supply chain disruptions continue to affect component pricing, making procurement strategy a critical component of project planning. Companies must account for volatility in battery technology and sensor availability when budgeting for large-scale deployments.
-
Tariff Implications: Trade policies, including US tariffs on imported sensors, semiconductors, and batteries for AGVs, have increased costs in certain regions. This economic pressure is encouraging localized sourcing in North America and Europe, influencing where companies manufacture and source their automation hardware.
-
Energy Efficiency Standards: Technological advancements have enabled AGVs to achieve up to 96% energy efficiency through advanced battery management and induction charging systems in warehouse operations. This efficiency reduces total cost of ownership and aligns with broader corporate sustainability goals, making AGVs an attractive option for green logistics initiatives.
Competitive Landscape and Vendor Differentiation
The AGV market is characterized by a mix of established industrial giants and agile technology specialists. Market concentration is significant, with the top three players holding a substantial share of the market and the top five commanding an even larger portion. This consolidation suggests that while there is room for innovation, scale and integration capabilities are becoming increasingly important for market leadership.
Key players are distinguishing themselves through specific technological offerings and strategic focus areas. Japan-based firms such as Daifuku Co., Ltd. and Toyota Industries Corporation are leveraging their heritage in automation and automotive manufacturing to lead in AGVs and sorting systems with AI-enabled navigation. Meanwhile, US companies like JBT Corporation, Seegrid Corporation, Vecna Robotics, and Hyster-Yale, Inc. are focusing on rugged operations, vision-guided systems, AI-driven collaboration, and integrated lift truck solutions respectively. European powerhouses including KION Group AG, KUKA AG, Swisslog Holding AG, SSI SCHAEFER, and Mitsubishi Logisnext are emphasizing integrated logistics solutions, industrial robotics, and warehouse systems.
Recent developments highlight the pace of innovation within this competitive field. In March 2025, Daifuku Co., Ltd. launched a new series of AI-enabled AGVs featuring enhanced obstacle detection and autonomous navigation, signaling a push towards smarter, safer vehicle fleets. September 2025 saw Hyster introduce the Hyster Atlas automated lift truck platform with a cloud-based drag-and-drop portal for AGV-integrated material transfers, emphasizing ease of integration and user control. Furthermore, in October 2025, KION Group AG presented a Physical AI platform at CeMAT Shanghai, demonstrating AGVs with 30% higher efficiency in complex environments. These milestones illustrate the rapid iteration of product capabilities and the increasing reliance on AI to optimize performance.
For buyers, this landscape implies that vendor selection must go beyond price considerations. Organizations need to assess the specific technological strengths of each provider relative to their own operational environment. Whether the priority is high-capacity handling for heavy manufacturing, vision-guided flexibility for dynamic warehouses, or cloud-based management for seamless integration, the competitive field offers diverse solutions tailored to distinct use cases.
Segmentation Overview: Types, Applications, and Regions
The market is segmented across various dimensions, each offering unique opportunities and challenges for stakeholders. Understanding the breadth of these segments helps organizations identify where their specific needs align with the broader market supply.
Vehicle Types and Functional Capabilities
The market encompasses a diverse range of vehicle types, each designed to address specific material handling requirements. Tow Vehicles remain a significant portion of the market, catering to applications requiring the movement of trailers and heavy loads. Unit Load Carriers are essential for transporting individual items or containers, often seen in high-volume picking environments. Pallet Trucks facilitate the movement of palletized goods, while Assembly Line Vehicles and Forklift Trucks serve specialized roles within manufacturing and heavy lifting contexts. The variety in vehicle types ensures that AGV solutions can be customized to fit the physical constraints and logistical needs of different facilities.
Application Versatility
AGVs are deployed across a wide spectrum of applications, reflecting their adaptability to different operational workflows. Transportation and Distribution represent a major use case, where vehicles move goods between different zones within a facility or across site boundaries. Storage and Assembly applications leverage AGVs to manage inventory placement and support production lines, ensuring smooth material flow. Packaging operations also utilize AGVs to streamline the final stages of product preparation and dispatch. This versatility allows companies to deploy automation in phases, targeting the most labor-intensive or error-prone processes first.
Automated Guided Vehicles (AGVs) Market
Geographic Distribution
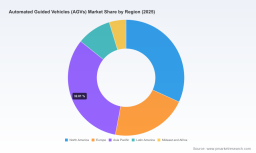
Geographic adoption varies based on industrial maturity, labor costs, and infrastructure readiness. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa each present unique market conditions. Factors such as local manufacturing bases, trade tariffs, and regional labor dynamics influence the rate of AGV deployment. Companies operating globally must tailor their investment strategies to these regional nuances, considering factors like localized sourcing requirements and specific regulatory environments when planning rollout strategies.
Strategic Decision-Making in 2026
For enterprise leaders, the data and analysis provided in PW Consulting's report offer more than just market statistics; they provide a foundation for strategic decision-making. In 2026, the choice to invest in AGVs is intertwined with broader corporate goals regarding sustainability, resilience, and efficiency. The roadmap to 2032 suggests that delaying automation investments may result in competitive disadvantages as peers leverage autonomous technologies to reduce costs and improve throughput.
Decision-makers must consider the total lifecycle cost of AGV systems, including procurement, integration, maintenance, and energy consumption. The impact of tariffs on components and the volatility of raw material costs necessitate flexible procurement strategies. Furthermore, alignment with regulatory standards ensures that investments are future-proofed against changing safety requirements. The growth projections indicate a rising tide of adoption, suggesting that the ecosystem of support, maintenance, and integration services will expand alongside the market itself.
Organizations should also evaluate their readiness for AI-enabled navigation and cloud-based management systems. As vendors like Daifuku and KION Group demonstrate higher efficiency through AI integration, the bar for performance is rising. Legacy systems without smart capabilities may become obsolete faster than anticipated. Therefore, strategic planning should prioritize scalable solutions that can evolve with technological advancements.
Conclusion and Call to Action
The Automated Guided Vehicles market stands at a pivotal juncture in 2026. With a strong growth trajectory, evolving competitive dynamics, and significant shifts in labor and regulatory landscapes, the opportunity for strategic investment is clear. However, navigating this complex environment requires detailed intelligence that goes beyond surface-level market summaries.
PW Consulting's comprehensive market research report offers the depth required to make informed decisions. From granular segmentation data to detailed vendor profiles and risk assessments, the full report provides the actionable intelligence necessary to optimize your automation strategy. We invite industry leaders, investors, and strategic planners to access the complete study to uncover the specific data points and insights that will drive your organization's success in the age of autonomous logistics.
Stay ahead of the curve by leveraging our expert analysis. Explore the full report to gain a competitive edge in the rapidly expanding AGV market.
For detailed analysis of this topic, please visit the official page: Automated Guided Vehicles (AGVs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com