

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Surgical Blades Market Sized at $219.8M in 2025, Projected 5.2% CAGR Through 2032

Navigating Precision: Strategic Insights for the Surgical Blades & Scalpels Market Through 2032
The global surgical blades and scalpels market stands at a critical inflection point. As healthcare systems worldwide navigate post-pandemic operational restructuring, supply chain realignment, and evolving safety mandates, the demand for precision cutting instruments has never required more rigorous strategic forecasting. Our latest market research offers a comprehensive, data-grounded examination of this essential medical device segment, delivering actionable intelligence tailored for executive decision-making in 2026 and beyond.
Over the historical period from 2020 through 2025, the market has demonstrated consistent upward momentum, with total revenue expanding from approximately 172.5 million USD to a projected 219.8 million USD by the base year of 2025. This trajectory reflects not only the steady recovery of elective surgical volumes but also structural shifts in procurement preferences, sterilization protocols, and instrument safety standards. Looking forward, the forecast period spanning 2026 to 2032 projects continued expansion, with a compound annual growth rate of 5.2 percent. By the close of the forecast horizon in 2032, overall market revenue is expected to reach 312.3 million USD, signaling a mature yet steadily evolving landscape where differentiation, compliance readiness, and channel optimization will separate market leaders from passive participants.
This research is designed specifically to serve as a strategic compass. It does not merely aggregate historical figures; it translates macroeconomic and clinical trends into operational frameworks that procurement directors, product managers, regulatory affairs leads, and investment analysts can apply immediately. The following sections outline the core components of the study, the competitive forces reshaping the industry, and the regulatory and reimbursement dynamics that will dictate market behavior in the coming years.
Research Architecture and Operational Deliverables
Our methodology combines longitudinal revenue tracking, supplier-side intelligence, and end-user purchasing pattern analysis to produce a multi-dimensional view of market behavior. The report is structured to provide immediate utility across several corporate functions. Each section is built around actionable frameworks rather than abstract commentary, ensuring that readers can translate findings directly into pricing strategies, capacity planning, distributor negotiations, and product development roadmaps.
Surgical Blades & Scalpels Market
- Comprehensive historical revenue mapping from 2020 through 2025, establishing a reliable baseline for trend extrapolation and scenario modeling
- Forward-looking revenue projections across the 2026 to 2032 forecast window, segmented by instrument type and surgical application to highlight where growth concentration and margin opportunities are forming
- Regional deployment analysis that examines demand maturity, procurement centralization tendencies, and import dependency across major healthcare markets, enabling geographic prioritization and localized go-to-market planning
- Supply chain and manufacturing readiness assessment, including sterilization validation pathways, material sourcing considerations, and capacity utilization patterns that influence lead times and service-level consistency
- Pricing architecture and margin sensitivity review, addressing how procurement consolidation, private-label contracting, and safety-instrument premiums are reshaping unit economics across hospital networks and ambulatory surgery centers
Throughout the document, we maintain a strict focus on practical decision support. Readers will encounter structured comparative tables, adoption curve assessments, and procurement behavior summaries that clarify how purchasing committees evaluate blade consistency, handle compatibility, sterility assurance, and total cost of ownership. The analysis deliberately avoids superficial generalizations, instead grounding each observation in verifiable procurement trends and regulatory milestones.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated supplier base, with the top three players collectively accounting for approximately 60 percent of total revenue and the top five capturing around 72 percent. This concentration reflects the technical barriers associated with precision metallurgy, sterile packaging validation, handle standardization, and consistent quality control. At the same time, the remaining competitive tier remains highly active, particularly in regions where cost efficiency, localized distribution, and rapid product iteration provide tangible procurement advantages.
Legacy manufacturers continue to anchor the market through established clinical trust, broad handle compatibility, and extensive sterile blade portfolios. Companies with multi-decade operational histories have built reputations around consistent edge retention, carbon steel and stainless steel options, and integrated safety or retractable configurations. Their competitive moat relies heavily on long-standing hospital contracts, standardized Bard-Parker-style handle ecosystems, and incremental innovation in safety features that align with institutional sharps-injury reduction programs.
In parallel, internationally scaled producers have expanded their footprint by emphasizing sterile disposable formats, full carbon steel and stainless steel line coverage, and export-oriented distribution networks. These players often compete on total landed cost, flexible minimum order structures, and rapid responsiveness to regional specification preferences. Their growth trajectory has been closely tied to the broader global shift toward single-use sterile instruments, especially in settings where reprocessing capacity, labor constraints, or infection-control policies make disposables the operationally preferred choice.
Precision-focused manufacturers from advanced industrial ecosystems continue to distinguish themselves through sharpness consistency, refined metallurgical finishing, and specialized safety scalpel lines. Their market positioning frequently emphasizes reliability under high-volume procedural use, controlled edge geometry, and adherence to stringent manufacturing quality systems. Meanwhile, dental-focused suppliers and specialized ophthalmic and micro-blade producers occupy highly specific application niches, where instrument precision, handle ergonomics, and procedure-specific formatting matter more than broad commodity volume.
Beyond standalone blade and scalpel manufacturers, broader perioperative solution providers have increasingly integrated blade and handle offerings into comprehensive surgical workflow portfolios. This integration strengthens cross-selling opportunities, deepens hospital account penetration, and aligns instrument supply with larger capital and service contracts. The result is a competitive environment where product performance remains essential, but account access, distribution reach, and bundled value propositions are becoming equally decisive.
Recent commercial activity already illustrates how distribution strategy is reshaping regional access. In early 2025, a notable distribution agreement expanded exclusive Canadian coverage for a major blade and scalpel portfolio, signaling how manufacturers are leveraging specialized regional partners to accelerate channel penetration, improve service responsiveness, and navigate procurement complexity without proportionally expanding direct sales infrastructure. Such moves are likely to continue as suppliers seek efficient pathways into concentrated purchasing environments.
Regulatory, Safety, and Reimbursement Dynamics
Market behavior in this segment is heavily shaped by regulatory classification, occupational safety standards, and reimbursement architecture. Scalpel blades and scalpels are generally classified as Class I exempt devices in major regulatory frameworks, meaning that most conventional models do not require premarket submission pathways beyond establishment registration and listing. This classification lowers entry barriers for established manufacturers but also intensifies competition on quality consistency, packaging reliability, and supply dependability rather than regulatory novelty.
At the same time, occupational safety mandates and international safety scalpel standards continue to drive institutional adoption toward single-use sterile disposable blades. Hospitals and surgery centers are increasingly prioritizing sharps-injury reduction, ergonomics, and standardized safety mechanisms, particularly in high-volume general surgery environments. Compliance expectations, including globally recognized quality management system requirements for manufacturing facilities and stricter single-use validation expectations in certain healthcare markets, reinforce the importance of documented process control and traceable sterile packaging.
Worldwide Surgical Saw Blades Market
Reimbursement structure further influences purchasing logic. Surgical blades and scalpels are not separately coded under dedicated procedure billing categories; instead, their costs are typically absorbed within global surgical procedure fees under existing procedural coding frameworks. This reimbursement reality encourages procurement teams to evaluate instruments through the lens of total procedural cost, waste reduction, handling efficiency, and injury-prevention value rather than line-item price alone. Consequently, suppliers that can demonstrate consistent performance, reduced reprocessing burden, and reliable sterility assurance are often better positioned to defend premium positioning or secure preferred vendor status.
Regulatory stability in classification does not mean strategic stagnation. On the contrary, it places greater emphasis on manufacturing discipline, packaging integrity, handle ecosystem compatibility, safety feature adoption, and service reliability. In practical terms, competitive advantage now depends on how effectively a supplier can align product design with institutional safety policies, procurement consolidation trends, and operating-room efficiency goals.
How This Research Supports 2026 Decision-Making
As organizations plan for the 2026 operating environment, the strategic question is no longer whether the market will grow, but where margin, share, and risk will concentrate within that growth. The 5.2 percent projected compound annual growth rate through 2032 indicates durable expansion, but that growth will not be evenly distributed across product categories, surgical specialties, or geographic procurement systems. Decision-makers need clarity on which instrument formats are gaining procedural preference, which application areas are driving volume resilience, and how regional purchasing behavior is evolving under cost-pressure and safety-compliance imperatives.
This study provides that clarity by mapping demand trajectories against supplier capabilities, regulatory expectations, and channel structures. It is built to support concrete actions: refining product mix decisions, prioritizing distribution partnerships, anticipating procurement consolidation pressure, and identifying where safety-driven disposables or precision-focused reusable lines are most likely to command strategic attention. The analysis also helps organizations anticipate how broader perioperative integration trends may influence account access and competitive positioning over time.
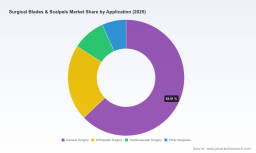
To move from high-level direction to detailed, numbers-backed strategy, decision-makers need the complete dataset, scenario models, and supplier-level comparisons contained in the full report. The executive summary presented here is intended to establish the strategic frame and demonstrate the depth of analysis available, while leaving the precise segmentation figures, regional deployment percentages, and application-level revenue breakdowns for the complete publication.
Next Steps and Source Access
Our full market research publication extends far beyond the framework outlined in this preview. It delivers the complete revenue trajectory, detailed segmentation insights, competitive profiling, procurement behavior analysis, and regulatory context needed to build defensible 2026 strategies and multi-year forecasts. For procurement leaders, product strategists, and market entry teams, the complete report converts broad industry momentum into targeted, operationally relevant intelligence. Readers seeking the full segmentation data, regional breakdowns, application-level analysis, and supplier comparison matrices are encouraged to access the complete market research directly through our official source page, where the complete dataset and strategic appendices are available for download and internal distribution.
In a market defined by precision, compliance, and evolving purchasing logic, informed strategy is the difference between reacting to change and shaping it. This research is designed to give organizations that advantage.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com