

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3D Reconstruction Market Hits $1.4B in 2025, Poised for 9.3% CAGR Through 2032

Strategic Intelligence for the 2026 Executive: Navigating the 3D Reconstruction Technology Market
The global landscape for 3D reconstruction technology is undergoing a structural shift. As enterprises across infrastructure, healthcare, manufacturing, and digital media accelerate their adoption of spatial computing and digital twin architectures, decision-makers require more than surface-level trend summaries. They need rigorous, forward-looking intelligence that maps technological inflection points to commercial outcomes. Our newly released 3D Reconstruction Technology Market study delivers precisely that. Built on a comprehensive historical dataset spanning 2020 through 2025 and extending a detailed forecast horizon to 2032, this research translates complex market mechanics into actionable strategic frameworks for 2026 and beyond.
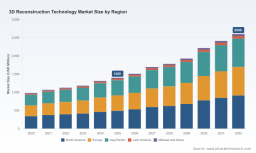
At the macro level, the trajectory is unambiguous. The global market generated approximately 1,400 million USD in revenue during the 2025 base year, building on a consistent growth arc from roughly 980 million USD in 2020. Our projections indicate that revenue will advance to approximately 1,509 million USD in 2026 and continue climbing toward 2,600 million USD by 2032. This expansion reflects a compound annual growth rate of 9.3 percent across the forecast window. More importantly, the growth is not uniform. It is being shaped by distinct technological transition points, shifting enterprise procurement priorities, and regulatory evolutions that collectively redefine which capabilities scale and which stall. For 2026 planning cycles, understanding these underlying dynamics is not optional; it is the difference between reactive budgeting and proactive portfolio strategy.
The Commercial Architecture of the Market
How Value Is Distributed Across Product Types
The market's commercial backbone is anchored by software, which commands the largest revenue share and sets the pace for ecosystem development. Hardware solutions form a substantial secondary layer, providing the sensing, scanning, and computational infrastructure that feeds data pipelines. Services, while currently representing a narrower revenue footprint, play a critical enabling role in deployment, integration, and domain-specific customization. Together, these categories reveal a market that is moving from isolated tool adoption toward integrated, workflow-centric solutions. Enterprises that evaluate vendors solely on standalone feature sets risk missing the larger shift toward interoperable reconstruction environments, where data capture, processing, and downstream utilization must operate as a continuous chain.
Where Demand Is Concentrating by Application
Demand is being pulled from multiple verticals simultaneously, yet the weighting of those applications is uneven and strategically meaningful. Construction and infrastructure applications lead in commercial significance, driven by the need for precise as-built documentation, progress tracking, and integration with building information modeling workflows. Healthcare and medical imaging represent another major demand center, where surgical planning, implant design, and performance capture are reshaping clinical and research workflows. Media and entertainment, manufacturing and industrial design, cultural heritage and archaeology, and gaming and virtual reality each contribute distinct adoption profiles, with different latency requirements, accuracy thresholds, and integration expectations.
For strategy leaders, the implication is clear. A single go-to-market logic does not apply across verticals. The same reconstruction capability that delivers operational value in a construction documentation workflow may need materially different certification, throughput, or visualization characteristics when positioned for healthcare planning or immersive media. Our report dissects these application pathways without oversimplifying them, helping executives match technology roadmaps to the reality of vertical-specific procurement and compliance environments.
Worldwide 3D Image Sensor Market
Regional Market Structures and Strategic Implications
Geographically, the market displays a concentrated but globally distributed structure. North America, Europe, and Asia Pacific each represent substantial revenue bases, while Latin America and the Middle East and Africa contribute smaller but strategically developing demand centers. The important insight is not simply that regions differ in scale, but that they differ in adoption drivers. Mature markets tend to prioritize integration with existing enterprise systems and measurable return on operational expenditure, while emerging regions often exhibit faster sensitivity to cost-effective entry points, mobile capture solutions, and exportable reconstruction workflows that can bridge infrastructure gaps. This divergence matters for expansion planning, partnership selection, and product localization strategies in 2026.
Competitive Landscape: Who Is Setting the Pace
The competitive environment reflects a layered ecosystem rather than a single dominant hub. The market is shaped by specialist software providers, established industrial and imaging hardware firms, digital twin and BIM integrators, and emerging players advancing generalized reconstruction approaches for mobile and immersive contexts. Our report profiles the companies that are actively defining the market's direction, including:
- Pix4D SA, whose photogrammetry software supports drone and terrestrial mapping to generate precise 3D models and spatial outputs from imagery.
- Agisoft LLC, known for Agisoft Metashape, a platform designed to convert digital images into 3D spatial data for GIS, surveying, and cultural heritage applications.
- 3dMD, which provides software-driven 3D and 4D reconstruction systems built on high-precision cameras for human form performance capture in healthcare, AI, and robotics contexts.
- Ricoh Company, Ltd., which extends 3D reconstruction through RICOH THETA cameras and AI-driven digital twin capabilities for XR applications and building documentation.
- Quidient LLC, developing Generalized Scene Reconstruction software and systems for mobile-device-based 3D plus 4D virtual reality modeling of objects and environments.
- Bentley Systems, Incorporated, whose 3D modeling and reconstruction solutions connect with digital twins and BIM for infrastructure, architecture, and engineering projects.
- Trimble Inc., delivering 3D reconstruction and mapping technologies through hardware and software for construction, agriculture, and geospatial applications.
- Leica Geosystems AG, supplying surveying and photogrammetry equipment that enables high-accuracy 3D reconstruction and point cloud generation.
- Topcon Positioning Systems, Inc., offering 3D surveying and mapping solutions for precise reconstruction in construction and land surveying.
- Autodesk, Inc., providing 3D reconstruction and modeling software such as ReCap for transforming point clouds into usable 3D environments.
- FARO Technologies, Inc., manufacturing 3D scanning and metrology systems for accurate object reconstruction in industrial and quality control settings.
- Matterport, Inc., developing 3D imaging platforms with cameras and software for capturing indoor environments and converting them into digital twins.
- NavVis GmbH, delivering mobile 3D laser scanning and mapping systems for indoor environment reconstruction and navigation.
- Emergent Vision Technologies, specializing in high-speed GigE industrial cameras that enable real-time 3D reconstruction in vision and imaging systems.
The strategic takeaway is not simply that these companies exist, but that they occupy different positions across the value chain and pursue different integration models. Some compete primarily on capture accuracy and workflow maturity; others compete on software ecosystems, interoperability, or specialized verticals. For 2026, competitive advantage will increasingly belong to organizations that can align vendor selection and internal development with a coherent reconstruction architecture rather than a collection of disconnected tools.
Market Dynamics Shaping 2026 Decisions
Regulatory Acceleration and Industry Validation
Recent developments underscore how quickly regulatory and institutional validation can alter commercial pathways. In May 2026, 3D Systems demonstrated clearance of EU regulatory requirements for 3D printed dentures, advancing the commercial use of 3D reconstruction in dental manufacturing. This milestone matters beyond one application because it signals broader acceptance of reconstruction-driven medical device workflows. At the same time, data protection frameworks such as GDPR and CCPA continue to mandate strict handling protocols for applications involving personal capture data or scanned environmental information. For enterprises deploying reconstruction technologies in shared spaces or human-facing contexts, compliance design is becoming a core element of product architecture, not a downstream legal afterthought.
Capital Investment and Advanced Use Cases
Public and institutional funding is also expanding the frontier of what reconstruction systems can address. In December 2025, Florida Tech's Autonomy Lab received a 1.5 million USD grant from the U.S. Space Force and the Air Force Research Lab to develop deep learning algorithms for 3D reconstruction of space debris and spacecraft from limited 2D images. While this effort is oriented toward aerospace and defense challenges, it illustrates a broader trend: reconstruction methods are being pushed into domains where input data is incomplete, noisy, or sparse. That progression influences commercial markets too, particularly in inspection, monitoring, and remote assessment scenarios where perfect capture conditions cannot be assumed.
Cost, Performance, and Operational Trade-Offs
Operational realities continue to shape deployment decisions. High-end industrial cameras and high-performance GPUs remain primary equipment and computational bottlenecks for real-time 3D reconstruction in manufacturing environments. At the same time, the efficiency payoff can be substantial. In assembly and inspection processes, 3D reconstruction can reduce manual measurement labor costs by 70 to 80 percent through automated point cloud analysis. These two forces—one constraining, one enabling—define a central strategic question for 2026: how to balance computational intensity and hardware investment against labor savings, throughput improvements, and quality gains. The answer varies by use case, but it must be quantified rather than assumed.
Healthcare Reimbursement as a Demand Catalyst
In healthcare, reimbursement dynamics are becoming an increasingly important driver. Post-2025 clinical protocols increasingly see reimbursement policies covering 3D reconstruction-based surgical planning and implant design. This shifts reconstruction from a purely technical feasibility question to a financially viable clinical workflow. It also raises the importance of integration, documentation, and validation standards, because reimbursement-ready adoption requires more than a capable system; it requires a defensible, repeatable process.
Concentration and Strategic Positioning
The market's competitive structure is relatively concentrated. The three largest players account for approximately 55 percent of market share, while the top five reach roughly 70 percent. This concentration creates both opportunities and risks. For buyers, it means a small number of incumbents exert meaningful influence over pricing, integration norms, and ecosystem direction. For challengers and niche innovators, it means differentiation must come from vertical specialization, workflow uniqueness, or technological advances that incumbents cannot easily replicate. For investors and corporate strategists, it means that market entry and partnership decisions should be evaluated against a landscape where share leadership already has a strong gravitational pull.
What Our Report Delivers for 2026 Strategy
This study is designed to support practical executive decision-making rather than abstract technology commentary. It combines historical market reconstruction, forecast modeling, application-level demand analysis, and competitive profiling into a single strategic reference. Specifically, the report helps leaders:
- Understand the growth path of the global market from the 2020 to 2025 historical period through the 2026 to 2032 forecast window, including the forces shaping the 9.3 percent CAGR trajectory.
- Assess how software, hardware, and services interact as an integrated commercial stack, and where procurement attention should be directed in 2026.
- Evaluate application demand across construction and infrastructure, healthcare and medical imaging, media and entertainment, manufacturing and industrial design, cultural heritage and archaeology, and gaming and virtual reality as distinct strategic segments.
- Interpret regional market structures in North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa as guides for expansion, localization, and channel strategy.
- Position against key competitors by understanding differing technology approaches, vertical focus areas, and integration philosophies across the profiled company set.
- Anticipate regulatory, compliance, reimbursement, and cost-related dynamics that influence adoption speed, deployment risk, and total cost of ownership.
- Connect recent developments, including EU regulatory clearance for 3D printed dentures and advanced research funding for space-facing reconstruction algorithms, to broader market implications.
Crucially, the report goes beyond top-line framing. It maps where demand intensity is concentrated, where integration complexity creates friction, and where competitive pressure is most likely to reshape purchasing criteria over the forecast period. That level of detail is necessary because 3D reconstruction technology is no longer a niche capability. It is becoming a foundational layer for digital spatial workflows, and its adoption decisions will influence operational efficiency, product development speed, and service delivery models across multiple industries.
Why This Research Matters Now
2026 is a planning year in which early-mover advantage will increasingly depend on the quality of market intelligence rather than on technology availability alone. Reconstruction tools are maturing, but maturity does not automatically translate into optimal deployment. The companies that win in this environment will be those that understand how market size, growth momentum, vertical demand patterns, competitive concentration, and regulatory conditions combine to shape realistic opportunity.
3D Reconstruction Technology Market
Our full 3D Reconstruction Technology Market report provides the deeper segmentation, scenario-based thinking, and competitive detail required to make those decisions with confidence. The public preview above outlines the strategic structure of the market and the analytical framework we use. The complete dataset, application-level breakdowns, regional dynamics, vendor comparisons, and forward-looking implications are available in the full study, where decision-makers can translate this direction-setting intelligence into precise investment, procurement, and development plans.
For executives mapping 2026 priorities, the core message is straightforward: the market is expanding with disciplined momentum, the competitive field is defined by differentiated specialists and integrators, and the real strategic task is to align reconstruction capabilities with the operational, regulatory, and financial realities of each target vertical. Our research exists to make that alignment possible with clarity, evidence, and commercial pragmatism.
For detailed analysis of this topic, please visit the official page: 3D Reconstruction Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com