

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Sees RF Front-end Module Market Hit $43.3 Billion by 2032 on 10.04% CAGR

Strategic Intelligence for the RF Front-End Module Market: Navigating the 2026 Decision Landscape
The radio frequency front-end module market has evolved from a component-level supply chain discussion into a strategic architecture question for enterprise leaders. As wireless standards mature, spectrum demand intensifies, and device form factors continue to shrink, the front-end module has become the enabling layer that determines performance, power efficiency, thermal behavior, and ultimately market readiness. Our latest market research on this sector is designed to convert complex industry signals into decision-grade intelligence for executives planning product roadmaps, sourcing strategies, capacity allocations, and long-term competitive positioning through 2026 and beyond.
This article introduces the scope and strategic intent of the study. It frames the market’s trajectory, outlines the analytical structure of the full report, and demonstrates how leadership teams can use the findings to reduce uncertainty in a landscape shaped by technological transition, supply constraints, and fast-moving competitive dynamics.
A Market Poised for Sustained Expansion
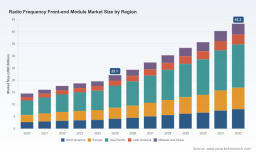
The RF front-end module market has demonstrated a clear and accelerating growth path across the historical window and into the forecast horizon. Revenue expanded from approximately 14.5 billion USD in 2020 to an estimated 22.1 billion USD in 2025, reflecting both rising device volumes and the increasing functional density of front-end architectures. Demand has not merely recovered from prior cycles; it has structurally advanced as connectivity requirements intensify across consumer electronics, telecommunications infrastructure, and automotive platforms.
Looking ahead, the forecast period from 2026 through 2032 points to continued expansion at a compound annual growth rate of 10.04 percent. Under this trajectory, the market is projected to rise from roughly 24.29 billion USD in 2026 to about 43.3 billion USD by 2032. These figures do more than describe size; they signal a shift in how enterprises must think about capacity planning, supplier partnerships, and technology investment. A double-digit CAGR over a seven-year horizon typically rewards early alignment with the right segments, geographies, and product families, while penalizing reactive or fragmented sourcing models.
Why 2026 Is a Critical Planning Year
For strategic planners, 2026 represents more than a midpoint in a forecast range. It is a year in which several overlapping forces converge: the maturation of Wi-Fi 7 ecosystems, the steady rollout of 5G variants and carrier aggregation requirements, the growing complexity of automotive wireless architectures, and persistent pressure on compound semiconductor supply chains. Organizations that set their 2026 priorities without a rigorous view of these forces risk misallocating engineering resources, locking into suboptimal supplier relationships, or missing windows for qualification and integration.
This research is structured to help leadership teams answer the underlying questions that shape 2026 decision-making. Which component categories are capturing the greatest value as devices become more bandwidth-intensive? How are leading manufacturers adjusting portfolios and manufacturing footprints to protect performance and resilience? Where are the most consequential supply constraints likely to influence cost and availability? And how should enterprises interpret regional and application-level demand patterns when allocating commercial and technical resources? The full report provides detailed answers grounded in structured analysis and verified company-level developments.
What the Research Delivers
The study is built for practitioners who need more than headline figures. It combines market sizing, segmentation logic, competitive profiling, and industry dynamics into a single decision framework. The intention is to give executives a consistent reference point for scenario planning, investment justification, and risk assessment.
Among the core elements included in the report:
- Historical market performance and forward projections that connect revenue trends with broader technology adoption cycles
- Component-level market structure covering RF switches, power amplifiers, low noise amplifiers, and RF filters, with attention to how each category contributes to overall market composition
- Application-level demand context spanning consumer electronics, automotive, and telecommunications, highlighting the different performance and qualification requirements that shape purchasing behavior
- Regional market distribution that frames where demand is concentrated and how geographic patterns influence sourcing, manufacturing, and partnership strategies
- Competitive intelligence on major participants, including product specialization, geographic bases, and recent commercial moves
- Industry dynamics covering raw material constraints, manufacturing capacity pressures, regulatory sensitivities, and geopolitical friction points affecting cross-border supply
Importantly, the report avoids reducing the market to a single narrative. Instead, it distinguishes between the structural drivers that persist over multiple years and the shorter-term disruptions that can alter procurement timing, pricing, and product availability. This layered approach is essential for enterprises that must plan with both confidence and flexibility.
Component and Application Dynamics Without Simplification
One of the most valuable aspects of the analysis is its refusal to treat the market as a monolith. The front-end module ecosystem is composed of distinct component categories that serve different roles in transmitter and receiver chains, and each category responds differently to performance requirements, integration trends, and cost pressures. RF switches, power amplifiers, low noise amplifiers, and RF filters all contribute to the market in meaningful ways, but their relative significance varies by device class, frequency band, and system architecture.
Similarly, the application landscape is not uniformly driven by the same adoption cycle. Consumer electronics continue to anchor a substantial share of demand, reflecting the relentless pace of smartphone, wearable, and personal connectivity device refresh cycles. Telecommunications infrastructure remains central as networks evolve to support higher throughput, better spectral efficiency, and broader coverage. Automotive demand, while smaller in current magnitude, is gaining strategic relevance as connected vehicle platforms, advanced driver-assistance systems, and in-cabin wireless experiences expand. The report examines how these application channels interact with component demand, qualification cycles, and supplier selection criteria, while preserving the analytical detail needed for precise planning.
Competitive Landscape: Intensity, Specialization, and Strategic Moves
The market’s competitive structure is best understood as a field of specialized leaders rather than a single dominant logic. Market concentration remains moderate, with the top three participants accounting for roughly 25.5 percent of revenue and the top five reaching about 29.8 percent. This level of concentration indicates a sector where scale matters, but differentiation still creates real advantage. Companies compete through package optimization, integration depth, protocol support, supply-chain reliability, and the ability to meet demanding efficiency and thermal requirements.
Several firms illustrate the breadth of strategic positioning in the market. Murata Manufacturing focuses on ultra-small integrated RF front-end modules that combine filters, RF switches, and matching circuits for LTE, Wi-Fi, Bluetooth, and GPS applications, reflecting a strong emphasis on size and integration. Broadcom develops high-performance RF front-end modules for mobile wireless, Wi-Fi 7 access points, and 5G infrastructure, supported by strong supply-chain partnerships. Skyworks Solutions provides RF front-end modules and integrated solutions for 5G smartphones, automotive connected vehicles, and IoT, with attention to power efficiency and carrier aggregation. Qorvo offers compact RF front-end modules integrating power amplifiers, LNAs, switches, and filters for 5G, Wi-Fi 7, IoT, radar, and satellite communications, and has expanded its mmWave portfolio through the acquisition of Anokiwave.
Qualcomm Technologies supplies complete RF front-end solutions and modules optimized for 5G, Wi-Fi 6E/7, Bluetooth, and multi-band carrier aggregation in smartphones and infrastructure. NXP Semiconductors delivers RF front-end modules and related semiconductor solutions for automotive, industrial, and IoT wireless applications. Infineon Technologies manufactures high-performance RF front-end modules for 5G, automotive, and industrial connectivity with emphasis on efficiency and reliability. Analog Devices produces integrated RF front-end ICs and amplifier-based modules for receiver and transmitter chains in mobile, infrastructure, and defense applications. Renesas Electronics provides RF front-end modules and semiconductors for automotive, industrial, and wireless infrastructure with multi-protocol support. STMicroelectronics offers RF front-end modules for mobile, IoT, and automotive sectors with silicon-based solutions and power management integration. Taiyo Yuden specializes in integrated RF front-end modules for Wi-Fi, Bluetooth, and low-power wireless applications.
This list is more than a roster. It reflects a market in which portfolio breadth, application focus, and technology specialization diverge significantly. Some companies concentrate on highly integrated mobile and infrastructure solutions; others prioritize automotive, industrial, or low-power wireless markets; still others extend into radar, satellite, or mmWave territory. Understanding these differences is central to evaluating supplier fit, anticipating product roadmap alignment, and interpreting the strategic meaning of recent commercial activity.
Automotive Front End Module Market
Recent Developments That Reshape Sourcing and Roadmap Decisions
Recent company actions show how quickly the competitive and supply environment can shift. In September 2025, Qorvo introduced the compact QPF4239 RF front-end module for Wi-Fi 7 systems, integrating a PA, SP2T switch, and bypassable LNA in a 3.0 x 3.0 mm package for access points, routers, and IoT. This kind of product introduction matters because it signals where the industry is pushing integration density, especially for next-generation wireless access and connected device applications.
Earlier, in September 2024, Murata opened a new dedicated RF module production facility in Malaysia to scale advanced RF front-end module manufacturing capacity. Facility investments of this kind are not merely operational updates; they indicate where suppliers expect sustained demand and where they aim to improve responsiveness and geographic diversification. Also in September 2024, Qorvo completed the acquisition of Anokiwave to expand its mmWave RF front-end module portfolio for 5G infrastructure and satellite communications, reinforcing the market’s ongoing move toward higher-frequency and more specialized front-end capability.
Supply agreements further illustrate the strategic anchoring taking place. In March 2024, Broadcom signed a multi-year supply agreement to provide RF front-end modules for Samsung’s 5G smartphone lineup. In the same month, Skyworks Solutions secured a supply contract for RF front-end modules with a major automotive OEM for connected vehicle platforms. These commitments reveal how frontline customers are locking in capacity and performance assurances in a market where qualification cycles and long-term reliability often determine commercial outcomes.
Industry Dynamics: Constraints, Risk, and Strategic Adaptation
Behind the growth narrative lies a supply environment that requires careful interpretation. Raw material constraints have become a material factor in planning. China’s gallium export restrictions have tightened feedstock for GaN wafers critical to high-power PAs in RF front-end modules, causing spot prices to surge in 2024 and prompting OEMs to pursue dual-sourcing strategies. By early 2026, these curbs continued to constrain GaN-based solutions, with defense and satellite contracts showing greater resilience than price-sensitive infrastructure deployments.
At the same time, global shortages of key raw materials and manufacturing capacity bottlenecks in compound semiconductors extended lead times for RF front-end module products through 2025. Tariff and export control sensitivities in the global supply chain, including gallium, arsenic, and specialty substrates, created ongoing challenges for cross-border assembly and distribution. Together, these dynamics show that pricing, availability, and supplier selection cannot be treated as static variables. Enterprises must account for feedstock exposure, geographic manufacturing footprint, qualification redundancy, and the possibility that certain high-performance technologies will carry different risk profiles depending on end market and customer segment.
How to Use This Research for 2026 and Beyond
The full study is intended to support a range of strategic uses. For product and technology leaders, it offers a structured view of component and application trends that can inform architecture choices and integration priorities. For supply chain and procurement teams, it provides context on supplier specialization, recent facility and acquisition activity, and the forces shaping lead times and sourcing risk. For corporate strategists and investors, it frames the market’s scale, growth rate, concentration structure, and competitive differentiation in a way that supports scenario modeling and portfolio decisions.
The report’s value lies in translating macro momentum into operational relevance. A market expanding at a double-digit CAGR is not automatically straightforward to serve. Growth can mask segmentation differences, supply bottlenecks, and competing supplier strategies that determine who captures value in practice. By separating long-term adoption signals from near-term disruption, the research helps organizations avoid overgeneralization and make choices that are robust across multiple plausible futures.
Radio Frequency Front-end Module Market
Closing Perspective
The RF front-end module market is entering a phase where technical performance, supply resilience, and competitive timing intersect more sharply than ever. This research is designed to give decision-makers a clearer line of sight into that intersection. It combines historical context, forecast trajectory, segmentation logic, competitive profiling, and current industry dynamics into a single analytical base for 2026 planning.
Detailed breakdowns, full segmentation figures, and complete company-level analysis are presented in the full report. For executives who need the precise data required to finalize sourcing strategies, product plans, and investment assumptions, the complete study provides the depth and structure necessary to move from market awareness to executable strategy.
For detailed analysis of this topic, please visit the official page: Radio Frequency Front-end Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com