

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Terahertz Imaging Inspection Market Hits $215M in 2025, Growth to $344.8M at 6.98% CAGR

Strategic Intelligence for 2026: Navigating the Terahertz Imaging Inspection Market
In the landscape of industrial quality control and non-destructive testing, terahertz imaging has evolved from a novel scientific concept into a critical enabling technology. As manufacturing processes become increasingly sophisticated—demanding higher precision, faster throughput, and non-invasive inspection methods—the reliance on electromagnetic spectrum frequencies between microwaves and infrared has grown commensurately. For enterprise strategists, investors, and operations directors, understanding the trajectory of this market is not merely an academic exercise but a financial imperative.
PW Consulting presents this comprehensive analysis of the Terahertz Imaging Inspection Market, drawing on extensive historical data and forward-looking projections through 2032. This report is designed to equip decision-makers with the clarity needed to navigate a sector defined by rapid technological iteration and shifting regulatory frameworks. By examining the growth trajectories analyzed up to the 2026 horizon, we identify where capital allocation and R&D efforts will yield the highest returns in the coming cycle.
The Strategic Imperative of a High-Growth Sector
The fundamental value proposition of terahertz imaging lies in its ability to penetrate non-conductive materials without the ionizing risks associated with X-rays. This unique capability positions the technology at the intersection of semiconductor manufacturing, security screening, and pharmaceutical quality assurance. Our analysis indicates that the market has transitioned from a phase of experimental validation to one of commercial scaling.
Historical data reveals a consistent upward trend in market valuation. From a baseline of approximately 163.15 million USD in 2020, the market demonstrated resilience and steady expansion, reaching over 205.5 million USD by 2024. The momentum is projected to continue, with valuations expected to approach 223.97 million USD in 2026. Looking further ahead, the forecast suggests the market could surpass 344.8 million USD by 2032. This represents a compound annual growth rate of nearly 7 percent over the forecast period.
This trajectory underscores a critical shift: terahertz technology is no longer confined to niche research laboratories. It is becoming integral to high-volume industrial processes. For businesses operating in 2026, the question is not whether this technology will mature, but how quickly their supply chains and inspection protocols will need to adapt to remain competitive. Early adopters who integrate these insights into their strategic planning stand to secure significant advantages in quality certification and operational efficiency.
Key Market Dynamics Shaping the 2026 Landscape
The growth of the terahertz imaging sector is not occurring in a vacuum. It is being driven and constrained by a complex interplay of technological advancements, regulatory developments, and infrastructure challenges. Understanding these dynamics is essential for accurate market forecasting.
Technology and Throughput Challenges
While the potential applications are vast, the path to widespread adoption faces technical hurdles. Early implementations often relied on single-pixel mechanical scanning architectures. While effective for low-volume inspection, these systems inherently limit throughput and scalability for industrial in-line applications. Recent research indicates a strong industry focus on shifting toward focal-plane arrays and parallel detection methods to address these bottlenecks. The ability to move from point-by-point scanning to real-time imaging is a key differentiator for vendors aiming to capture large-scale manufacturing contracts.
Furthermore, challenges remain in power generation and detection efficiency. High device costs currently act as a barrier to entry for smaller enterprises. However, as component costs decrease and system reliability improves, the total cost of ownership is becoming more favorable for high-value inspection tasks, such as semiconductor wafer inspection and multilayer coating analysis.
Regulatory and Standardization Frameworks
The regulatory environment is evolving rapidly, creating both opportunities and compliance complexities. In late 2024, the FDA granted Breakthrough Device designation to a terahertz-based skin cancer detection system, accelerating its pathway to clinical commercialization. This milestone signals broader acceptance of terahertz technology in sensitive environments.
Worldwide THz Image Intensifier Market
However, significant challenges persist regarding standardization. There is currently a lack of standardized measurement protocols and exposure metrics specifically tailored to terahertz frequencies. This absence presents a key barrier to consistent regulatory compliance and metrology verification. While emerging frameworks supported by NIST and European Commission collaborative initiatives are beginning to focus on industrial adoption protocols, no dedicated NDT standards or certifications exist specifically for terahertz imaging yet. Organizations entering this space must navigate this ambiguity carefully, often needing to establish internal validation standards until broader industry consensus is reached.
Market Competition and Innovation
The competitive landscape is characterized by a mix of specialized imaging firms and broader photonics manufacturers. Our analysis identifies several key companies driving innovation and deployment in this space.
- TeraView Limited (Cambridge, UK): Recognized as a pioneer in commercial terahertz pulsed imaging systems, their focus spans non-destructive testing, semiconductor inspection, and pharmaceutical quality control. Notably, in July 2025, they partnered with DOOLIM-YASKAWA to deploy the TeraCota 2000 sensor for real-time automotive paint inspection, marking a significant step in automotive manufacturing integration.
- Menlo Systems GmbH (Martinsried, Germany): A provider of turn-key THz time-domain spectroscopy and imaging systems. In November 2025, they demonstrated the TeraSmart with THz Reflection Head for real-time tablet thickness measurement, highlighting applications in pharmaceutical manufacturing quality control.
- TOPTICA Photonics AG (Gräfelfing, Germany): Known for ultrafast time-domain terahertz platforms, they introduced the TeraScan ultra platform in August 2025. This product is optimized for wafer inspection and high-resolution terahertz imaging, targeting the semiconductor sector's demand for precision.
- Luna Innovations Incorporated (Roanoke, VA, USA) and TeraSense Group Inc. (San Jose, CA, USA): These firms supply T-Ray systems and portable sub-THz linear imaging scanners respectively. TeraSense announced a pipeline for their THz Passive Body Scanner System 3.0 in October 2025, emphasizing high-speed imaging capabilities for security applications.
- Emerging Players and Research Institutes: Entities like Sequestim Limited and Cambridge Terahertz Inc. continue to push boundaries in security screening and real-time detection. Additionally, in January 2026, the Beijing Research Institute of Telemetry was granted a European patent for a multimode real-time imaging system supporting passive and active THz modes for aerospace target surveillance, indicating growing intellectual property activity outside traditional Western markets.
The market concentration remains relatively fragmented, with no single entity commanding a dominant share. This fragmentation suggests that innovation speed and niche specialization are currently more valuable than sheer market dominance. For potential partners or acquirers, this presents opportunities to identify technology leaders in specific verticals before they consolidate market share.
Market Segmentation and Application Verticals
The deployment of terahertz imaging technology is not uniform across all industries. Our segmentation analysis reveals distinct patterns in how value is distributed across types and applications, though specific regional and detailed percentage breakdowns are reserved for the full report to ensure strategic advantage for our clients.
By Technology Type: The market is currently dominated by Transmission Imaging systems, which account for the largest share of revenue. This is followed by Reflection Imaging and Other Types. The prevalence of transmission systems is largely driven by their established utility in semiconductor and pharmaceutical inspection where material penetration is critical. However, reflection imaging is gaining traction in scenarios where access to both sides of a component is impossible, such as certain coating inspections or structural integrity tests.
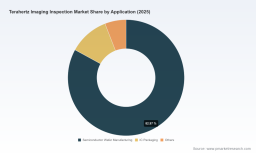
By Application: Semiconductor Wafer Manufacturing stands out as the primary driver of market value. As chip architectures shrink and complexity increases, the demand for non-destructive, high-resolution inspection tools becomes existential for manufacturers. Other significant applications include IC Packaging and a diverse range of industrial uses categorized under Others. The security sector also remains a robust growth area, particularly for body scanners and parcel screening systems, driven by heightened global security protocols.
By Region: Global adoption patterns show strong activity across North America, Europe, and Asia Pacific. Each region presents unique regulatory environments and industrial priorities. For instance, semiconductor-heavy regions in Asia Pacific drive specific demand curves compared to security-focused deployments in North America or Europe. Detailed regional revenue splits and growth rates for each territory are provided within the confidential sections of the full study.
Strategic Insights and Recommendations for 2026
Based on the synthesis of historical data, current developments, and forward-looking forecasts, several strategic recommendations emerge for stakeholders operating in 2026.
1. Align R&D with Throughput Requirements
Investors and product managers should prioritize technologies that solve the throughput bottleneck. Systems that rely on single-pixel mechanical scanning may face obsolescence as industrial clients demand conveyor-based and high-speed inspection solutions. Focus should be placed on vendors demonstrating progress in focal-plane arrays or parallel detection architectures.
2. Monitor Regulatory Evolution Closely
Given the lack of dedicated NDT standards, companies should engage with standardization bodies early. Compliance strategies should be flexible enough to adapt to emerging frameworks from NIST and European Commission initiatives. Proactive engagement can position a company as a standard-setter rather than a follower.
3. Target High-Value Verticals First
While the market breadth is wide, the highest immediate value lies in semiconductor manufacturing and pharmaceutical quality control. The ROI for terahertz inspection is clearest in these high-margin sectors where defect detection directly impacts product yield and safety. Security applications offer volume but often come with different procurement cycles and price sensitivities.
4. Evaluate Partnership Opportunities
The competitive landscape includes many specialized players. Rather than building capabilities from scratch, large industrial firms may find value in partnering with established technology providers like TeraView or TOPTICA to integrate sensing capabilities into existing production lines. The recent commercial partnership between TeraView and DOOLIM-YASKAWA serves as a blueprint for successful industrial integration.
Conclusion: The Value of Deep Intelligence
The Terahertz Imaging Inspection Market is poised for sustained growth, driven by the indispensable need for non-destructive, high-resolution inspection in modern manufacturing. However, the path forward is nuanced. Success requires more than just awareness of the technology; it demands a granular understanding of market sizing, competitive positioning, and the specific barriers to adoption that vary by region and application.
This article provides a high-level overview of the strategic landscape. It highlights the growth trajectory from 2020 through the 2032 forecast and identifies key players shaping the industry. Yet, the true strategic advantage lies in the details that cannot be fully disclosed here.
To make informed capital allocation decisions, executives need access to detailed segmentation data, specific regional growth rates, precise competitive market shares, and comprehensive risk assessments. These elements are critical for building robust business cases and avoiding costly strategic missteps.
PW Consulting's full Terahertz Imaging Inspection Market research report offers this depth. It includes complete revenue breakdowns, detailed competitor profiles, and actionable forecasts tailored to specific business units. We invite you to access the full report on our website to gain the comprehensive intelligence necessary to lead in this evolving sector.
Terahertz Imaging Inspection Market
For detailed analysis of this topic, please visit the official page: Terahertz Imaging Inspection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com