

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Conductive Acetylene Black for Li‑ion Battery Market Poised to Expand at 11.45% CAGR, Signaling Rapid Global Growth

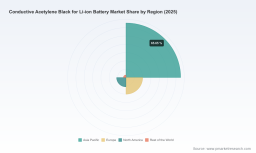
Worldwide Conductive Acetylene Black for Li‑ion Battery Market — Strategic Outlook 2026
PW Consulting today publishes an executive industry brief accompanying our full market study, Worldwide Conductive Acetylene Black for Li‑ion Battery Market. This briefing distills the report’s most consequential, decision‑critical insights for corporate leaders, procurement teams, and investors preparing to make strategic moves in 2026. It demonstrates why conductive acetylene black is no longer a niche commodity but a strategic raw material whose supply, technology pathway, and carbon profile will materially influence battery competitiveness and downstream cost and performance curves.
Worldwide Hot Melt Adhesive Film Market
Market snapshot: momentum and scale
Our model shows the market for conductive acetylene black used in lithium‑ion batteries expanding rapidly through the decade. From a measured market base in 2020, the market reached a robust global size in 2025 and our forecast projects sustained acceleration from 2026 through 2032 at a compound annual growth rate (CAGR) of approximately 11.45%. Under PW Consulting’s central scenario, the market value rises materially by 2032, reflecting combined demand growth from electric vehicles, portable electronics, and grid‑scale storage as well as ongoing performance and purity upgrades required by advanced electrode formulations.
Worldwide Sample Evaporator Market
Why acetylene black matters now
- Conductive additives are a small share of cell mass but an outsized driver of power delivery, cycle life, and electrode manufacturability. Acetylene black’s morphology and ultra‑low metallic impurity profile make it a preferred choice for high‑performance LIB anode and cathode formulations.
- As battery makers chase higher energy density and faster charging rates, the tolerance for impurity and inconsistency shrinks. That raises the bar for battery‑grade carbons and converts what was once a commodity buy into a strategic sourcing decision.
- Concurrently, decarbonization of upstream carbon production and secure access to acetylene feedstock are emerging as procurement KPIs. Buyers increasingly evaluate not just price and quality, but the carbon intensity and contractual integrity of supply chains.
Primary market dynamics shaping 2026 decisions
- Capacity additions and timing. Significant greenfield capacity expansions are scheduled to come online in the 2026 window. These additions will alter regional flows and bargaining parameters for large offtakers; understanding precise commissioning schedules and ramp profiles is a procurement imperative.
- Feedstock dependency. Acetylene black production remains dependent on acetylene feedstocks, historically sourced via calcium carbide or newer low‑carbon plasma methods. Feedstock sourcing agreements and proximity to acetylene suppliers materially impact unit economics and risk exposure.
- Policy and financing. Public finance and subsidies are already shaping the competitive landscape: government‑backed loans and technology subsidies are accelerating low‑carbon acetylene programs and incentivizing near‑site manufacturing. These measures will influence siting decisions and long‑term cost curves.
- Concentration and supplier power. The market exhibits moderate to high concentration among leading manufacturers. A small set of established producers account for the majority of battery‑grade acetylene black capacity, which creates both stability in quality standards and potential bottlenecks for rapid demand spikes.
- Technology and product differentiation. Suppliers are competing on ultra‑low impurity grades, morphology control, and tailored electrolyte‑electrode interaction properties. The winners will be those who combine consistent product specs with transparent low‑carbon production pathways.
Competitive landscape: what to watch in 2026
Our report profiles incumbent and emerging suppliers and maps strategic moves that will determine supply availability and pricing dynamics in 2026. Key vendor developments through 2025 highlight concrete shifts:
Worldwide Retail LMS Software Market
- Denka Company Limited (Tokyo, Japan) continues to promote ultra‑pure product formulations optimized for next‑generation batteries, while pursuing capacity diversification through international joint ventures. Denka’s supported initiatives—including public financial arrangements and technology subsidies for low‑carbon acetylene—demonstrate how industrial policy and corporate strategy can coalesce to secure prioritized feedstock and accelerated production capability.
- Orion Engineered Carbons (Luxembourg, with major operations in Europe and the USA) is scaling capacity with a new dedicated acetylene black plant in La Porte, Texas. Commissioning anticipated in 2026 will materially expand effective battery‑grade capacity available to North American and global OEMs and should be closely watched by buyers seeking to rebalance regional exposure.
- IRPC (Thailand) and other regional producers are positioning premium grades for battery use, reinforcing Asia’s role in both manufacturing and innovation. Regional manufacturing footprints remain a strategic lever for cellmakers seeking to shorten supply chains.
- U.S. suppliers such as Soltex Inc. continue to supply a diversified portfolio of grades, enabling specialized applications and fast prototyping cycles for battery developers.
Collectively, the top three and five producers capture a majority share of the market, underscoring structural supplier influence. This concentration creates both opportunities for long‑term partnerships and negotiation leverage for large offtakers—and systemic risk if demand accelerates beyond planned expansions.
Strategic actions for 2026—operational and commercial playbook
Leaders preparing 2026 budgets and sourcing strategies should treat conductive acetylene black as a strategic procurement category. Our report extracts practical tactics from market data and supplier interviews; below are the highest‑impact actions we recommend:
- Segmentation of sourcing strategies: separate high‑purity, low‑carbon grades for critical cell lines from broader commodity buys for legacy products. Tailor contract length and flexibility accordingly.
- Secure upstream visibility: negotiate early access to feedstock arrangements or second‑tier supply to mitigate acetylene supply shocks. Consider feedstock‑to‑product joint ventures for critical capacity.
- Lock in conditional offtakes around commissioning milestones: as new facilities come online in 2026, staggered offtake contracts tied to ramp rates can be more cost‑effective than spot exposure.
- Implement supplier scorecards that weight carbon intensity and traceability alongside quality and price. Regulatory and customer scrutiny of embodied emissions will grow, affecting procurement KPIs.
- Stress‑test sourcing strategies under multiple growth scenarios. Rapid EV adoption, accelerated ESS deployment, or a slower‑than‑expected scale of low‑carbon feedstock can each produce divergent outcomes; prepare contingency plans for inventory, logistics, and contract flexibility.
- Pursue collaborative R&D and qualification programs to accelerate adoption of next‑gen acetylene black grades, shortening qualification cycles and locking in technical differentiation that is difficult for competitors to replicate quickly.
What the full PW Consulting report contains (practical deliverables)
The full report is designed as an operational manual for 2026 decision‑making. Key deliverables include:
- Granular, vendor‑level profiles and benchmarking across manufacturing footprint, product grades, QA practices, and supply chain resilience metrics.
- Detailed market forecasts and scenario models (2026–2032) reflecting alternative EV/ESS growth paths and technology adoption curves, with sensitivity to feedstock and policy interventions.
- Supply map and capacity‑commissioning calendar, highlighting where and when new production will materially change regional flows and negotiating leverage.
- Manufacturing cost models and margin drivers for acetylene black production under prevailing feedstock configurations, including low‑carbon process variants.
- Commercial playbook templates—offtake term structures, price indexation mechanisms, quality acceptance criteria, and escalation clauses to operationalize strategic sourcing choices.
- M&A and investment heatmaps identifying potential acquisition targets, JV partners, and white‑space investment opportunities for industrial players and private equity.
- Regulatory and policy tracker that evolves with subsidy programs, public financing instruments, and technology grants influencing low‑carbon acetylene adoption.
To respect the “trailer” principle, this briefing intentionally highlights scope and strategic takeaways while withholding the full set of subsegment tables and supplier‑level commercial datapoints that appear exclusively in the complete report package.
Implications for investors, OEMs, and battery manufacturers
2026 will be a decision point: organizations that align procurement, engineering, and corporate strategy to the emerging geometry of acetylene black supply and low‑carbon production will gain first‑mover advantages in cost, quality, and sustainability narratives. Investors should prioritize companies with transparent feedstock strategies and credible commissioning schedules. OEMs and cellmakers should convert short‑term contingency planning into multi‑year supplier partnerships that embed ramp commitments and technology co‑development clauses.
Next steps
PW Consulting’s full Worldwide Conductive Acetylene Black for Li‑ion Battery Market report provides the proprietary datasets, vendor scorecards, and commercial templates needed to operationalize the strategies summarized here. For procurement teams, engineering groups, and corporate strategists planning for 2026 and beyond, the report is a tactical roadmap—complete with executable playbooks and scenario models—that transforms market intelligence into immediate action.
Contact PW Consulting or visit our report page to access the full analysis, obtain tailored briefings for your executive committee, or license the underlying datasets and supplier models to support 2026 planning and contract negotiations.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Acetylene Black for Li-ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com