

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Burden Carrier Market Poised for Expansion — Forecasted 4.95% CAGR Signals New Strategic Opportunities

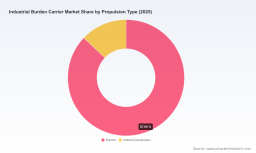
Worldwide Industrial Burden Carrier Market — Strategic Imperatives for 2026
Executive snapshot
The Worldwide Industrial Burden Carrier Market has moved from a niche operational asset to a strategic fleet component across manufacturing, logistics, aviation and heavy industry. Our latest analysis at PW Consulting shows that the market expanded from USD 420.5 Million in 2020 to USD 535.4 Million in 2025 (base year). Under our modeled scenarios the sector is projected to continue its steady climb into the early 2030s — with a 2026 projection of USD 552.9 Million and a trajectory that reaches USD 750.85 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.95% across the forecast period.
eSIM Module Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is the inflection year for many operators evaluating fleet electrification, modular platforms and lifecycle service monetization. The numbers above show sustained market expansion, but the strategic opportunity lies in timing investments to capture efficiency gains and regulatory tailwinds.
Worldwide Blogger Outreach Software Market -
Regulatory drivers: Global zero-emission mandates, indoor air-quality standards and evolving safety norms (including ongoing relevance of ISO 3691-1 for related self-propelled industrial trucks) are accelerating the shift toward electric and low-emission burden carriers. These mandates change procurement specifications, total-cost-of-ownership (TCO) calculations and upgrade cycles.
Worldwide Swim Club Management Software Market -
Supply-chain and input-cost sensitivity: Steel and related raw-material price fluctuations — from iron ore through hot-rolled coil (HRC) — materially affect chassis and frame economics. Procurement strategies that lock favorable terms or enable material substitutes de-risk manufacturing margins.
-
Operational dynamics: Persistent labor shortages and the rise of warehouse automation are increasing reliance on burden carriers to maintain throughput, reduce manual handling injuries, and integrate with warehouse management systems (WMS) and fleet telematics.
What the PW Consulting report contains — practical, decision-ready content
-
Executive summary with rapid-read strategic implications for C-suite, procurement and plant operations teams.
-
Market-sizing and three-scenario forecasting (baseline, upside, downside) anchored to our 2025 base and extending through 2032, including sensitivity tests on raw-material prices, battery-cost curves, and regulatory adoption timelines.
-
Buyers’ playbook — procurement checklists, supplier evaluation templates, and acquisition vs. lease TCO calculators calibrated for burden carriers.
-
Supply-chain heatmap — supplier concentration, single-sourcing risks, and tactical hedging strategies for steel and battery cell exposure.
-
Product and technology roadmap — feature-priority matrices (battery chemistry, modular chassis, telematics), integration pathways to WMS and AMR systems, and upgradeability guidelines to protect installed-asset value.
-
Commercial models — pricing tiers, service-contract designs, extended-warranty economics and aftermarket parts strategies to monetize installed fleets.
-
M&A and partnership screening — criteria-driven shortlist of targets, valuation frameworks and integration playbooks for scale or capability acquisitions.
-
Country- and facility-level implementation playbooks — compliance checklists, CAPEX phasing, and change-management templates for frontline adoption.
Competitive landscape — what leading vendors are signaling
The sector is populated by diverse OEMs ranging from specialist burden-carrier manufacturers to large material-handling conglomerates. The competitive picture is best described as evolution toward electrified, configurable platforms and service-led differentiation. Below we summarize the strategic posture of key players covered in the report.
-
Motrec International Inc. (Quebec, Canada) — https://motrec.com/
Strengths: Highly configurable electric flatbed designs and proven heavy-load platforms. Strategic angle: customization and heavy-duty reliability. Implication: Motrec is well-positioned to win bespoke fleet deployments where payload and durability outweigh unit-price sensitivity. -
Taylor-Dunn Manufacturing Company (Anaheim, CA, USA) — https://www.taylor-dunn.com/
Strengths: Broad portfolio with proven utility in tight-pathway environments and high-towing variants. Strategic angle: ergonomics and operational familiarity. Recent activity: launched new ergonomics-focused product line in 2025 to address operator comfort and safety, supporting longer duty cycles. -
Cushman (Textron Specialized Vehicles) (Augusta, GA, USA) — https://cushman.txtsv.com/
Strengths: Brand scale, dealer networks and product breadth across personnel and material movement. Strategic angle: channel depth and integrated aftermarket offerings. Implication: Cushman competes on total ecosystem rather than single-model advantages. -
Pack Mule (Capacity Trucks) (USA) — https://packmule.com/
Strengths: Heavy-duty NXG and ALPHA series engineered for manufacturing and distribution centers. Strategic angle: payload and towing as differentiators for industrial customers facing high throughput demands. -
Johnson Industries Inc. (Kentucky, USA) — https://johnsonindustries.com/
Strengths: Safety-first designs tailored for mining and heavy industry. Strategic angle: ruggedization and compliance with demanding safety protocols. -
Trowin Industries (USA) — https://www.trowin.com/
Strengths: Versatile flatbed platforms for maintenance, rescue and baggage handling. Strategic angle: role-specific versatility. -
Columbia ParCar Corp (Reedsburg, WI, USA) — https://www.columbiaparcar.com/
Strengths: Broad product family focused on industrial material and personnel movement. Strategic angle: value-oriented platforms with aftermarket support. -
Bobcat Company (West Fargo, ND, USA) — https://www.bobcat.com/
Strengths: Leveraging construction-equipment engineering to deliver heavy-capacity carrier models. Recent activity: announced enhanced warehouse-capability model availability in early 2026, signaling continuity of product refresh cadence and channel readiness. -
Toyota Material Handling (Columbus, IN, USA) — https://www.toyotaforklift.com/
Strengths: End-to-end material handling portfolio and extensive dealership network. Strategic angle: integration with forklifts, automation systems and fleet services. -
HC Forklift America (USA)
Strengths: Newer entrants focusing on lithium-ion propulsion and multi-seater/enclosed cabin options. Recent activity: showcased a lithium-ion, 4-seater model with enclosed cabin at a major trade show in March 2026 — an example of differentiation through cabinization and battery chemistry.
Recent strategic signals and what they mean
-
Product refreshes and trade-show debuts in 2025–2026 demonstrate that vendors are racing to lock design wins with electrified, operator-centric features rather than competing solely on base-platform price.
-
OEMs are layering aftermarket and telematics services to build recurring revenue streams — an important consideration for buyers that want predictable lifecycle costs.
-
New lithium-ion offerings and enclosed-cabin variants suggest that vendors are anticipating use-cases beyond traditional warehouse floors — including airport operations, campus mobility and controlled-environment manufacturing.
Five priority moves for 2026
-
Accelerate pilot-to-scale electrification: Run segmented pilots that validate battery chemistry, duty-cycle matching and charging infrastructure — consolidate learnings into a 24–36 month roll-out plan tied to TCO thresholds.
-
Hedge raw-material exposure: Negotiate multi-year supply agreements or volume options with steel and battery suppliers; explore alternative materials and modular subframes to reduce margin volatility.
-
Design for service revenue: Structure aftermarket contracts (parts, predictive maintenance, remote diagnostics) and align incentives with dealers for uptime guarantees; this improves ROI on higher-spec electric platforms.
-
Prioritize integration and safety compliance: Ensure new fleet specifications include telematics for WMS/ERP integration and meet or exceed applicable safety standards; this reduces friction during deployment and protects operating metrics.
-
Targeted M&A or partnership play: For OEMs and Tier-1 suppliers, evaluate bolt-on acquisitions that add battery expertise, telematics platforms or dealer networks. For large end-users, consider strategic partnerships for shared charging or fleet-as-a-service arrangements.
How to use this research in your 2026 planning cycle
Executives should treat the report as both a market map and an implementation manual. Use the forecast scenarios to stress-test your procurement calendar and CAPEX approvals; use the supplier heatmap and raw-material sensitivity analyses to build procurement contingencies; and use the buyer-playbook sections to align internal stakeholders on preferred-spec frameworks and service-level KPIs.
Next steps and where to access the full intelligence
PW Consulting’s Worldwide Industrial Burden Carrier Market report is designed to be executable for teams setting strategy in 2026. This article provides the strategic context and executive actions; the full report contains the granular segmentation, region- and application-level forecasting, competitive share tables, and downloadable financial models that underpin our recommendations. For license options, bespoke advisory, and access to the datasets and software models that drive our forecasts, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Burden Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com