

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Stainless Steel Vacuum Flask Market to Rise from USD 5,620M in 2025 to USD 8,035M by 2032 at a 5.24% CAGR, Led by Asia‑Pacific

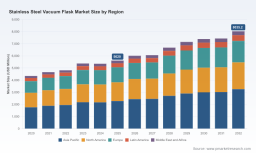
Worldwide Stainless Steel Vacuum Flask Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research, prepared with a 2025 base and a 2026–2032 forecast horizon, distils the competitive, commercial, and supply‑chain dynamics that will determine winners and losers in the stainless steel vacuum flask industry over the next seven years. Our proprietary market model projects continued expansion from a multi‑billion USD market in 2025 toward a materially larger global opportunity by 2032, underpinned by a steady compound annual growth rate of 5.24%. For commercial leaders preparing budgets, capex plans, product roadmaps, M&A pipelines and retail negotiations in 2026, this report translates headline growth into actionable choices.
Worldwide Organic Detox Tea Market
Why this briefing matters for 2026 strategy
-
Growth with disruption: A predictable mid-single‑digit CAGR masks multiple near‑term shocks — raw material inflation, product safety incidents and a shifting retail mix. Leaders must reconcile steady top‑line expansion with episodic margin and reputational risks.
Worldwide Mechanical Presses Machine Market -
Fragmented supply economics: The market’s relatively low concentration (CR3 ≈ 18.45%, CR5 ≈ 26.32%) signals buyer power opportunities and M&A upside, but also implies intense competition on price and distribution. Strategic players will need distinct differentiation or scale plays to expand margin pools.
Worldwide Oil Cooling Units Market -
Operational levers are decisive in 2026: Decisions on dual‑sourcing, inventory posture, raw‑material hedging, and testing protocols will materially affect P&L and time‑to‑shelf across the year.
-
Channel and premiumization are not binary choices: High‑growth pockets remain in premium, lifestyle and sustainability‑led segments while e‑commerce and omnichannel strategies reallocate distribution economics. 2026 will be a year of calibration rather than wholesale reinvention.
What’s inside the full PW Consulting report (practical, executive‑ready)
-
Forward‑looking market model with scenario outputs: baseline, stress (raw‑material shock), and acceleration (premiumization surge) — all linked to revenue, margin and inventory outcomes for 2026–2032.
-
Channel playbooks: tailored go‑to‑market templates for D2C, online retail, supermarkets/hypermarkets and specialty channels with margin levers, promotional cadence, and SKU rationalization guidance.
-
Supply‑chain heatmaps and supplier scorecards: manufacturability, capacity, quality history and on‑shore/off‑shore risk scoring to prioritize dual‑sourcing and contingency stock policies.
-
Cost‑pass through and pricing toolkit: elasticity testing frameworks and recommended price architecture to protect margins when stainless steel and nickel costs move.
-
Regulatory and safety readiness checklist: recalls and product‑safety playbooks, including incident response, communication templates, and third‑party testing protocols.
-
M&A and portfolio playbook: target typologies, valuation approaches, integration risks, and a short list of acquisition templates aligned with scale, premium, or capability buys.
-
Innovation and sustainability roadmap: materials tradeoffs (304 vs 316 stainless decisions), recyclability claims verification, and consumer‑facing sustainability narratives that convert into price premium analytics.
Competitive landscape — strategic implications for 2026
The sector combines household consumer brands, premium lifestyle players, and high‑volume OEM/ODM manufacturers. Below we synthesise the competitive positions that matter for 2026 planning.
-
Thermos (China / US) — Market leadership and brand franchise provide shelf dominance and retail leverage. However, recent product‑safety incidents involving millions of units have elevated regulatory scrutiny, warranty and recall risk, and downstream liability exposure for retailers and distributors. For strategy teams, the priority is to stress‑test quality assurance, supplier traceability and crisis communications protocols.
-
Zhejiang Haers and other large Chinese OEMs — These suppliers offer scale, cost competitiveness and strong ODM/OEM capabilities to hundreds of brands. Their strengths make them natural partners for private label and volume playbooks, but exposure to commodity cycles and export regulation necessitates robust procurement and contractual protections.
-
Tiger & Zojirushi (Japan) — Premium engineering, reputation for durable thermal performance, and a customer base that values reliability support resilient margins. Their playbook is quality‑led product differentiation, which is attractive to acquirers seeking margin resilience in a crowded market.
-
Hydro Flask, Klean Kanteen, YETI (United States) — Lifestyle and sustainability credentials drive premium pricing and brand loyalty. These players illustrate the value of community, design and environmental positioning in extracting higher unit economics.
-
Regional OEMs and smaller manufacturers (e.g., Steel Termos, Mountop, LAIKOE) — Important for regional distribution and bespoke product lines. They will be focal points for consolidation and fast capacity augmentation if demand surprises on the upside.
Collectively, these dynamics create a market where brand equity, manufacturing depth, and channel mastery coexist — but where no single player exerts dominant pricing power. That creates persistent opportunities for acquisition, private label growth, and vertical integration in 2026.
Key external risks and industry signals to monitor
-
Commodity volatility: Recent material cost inflation is pressuring margins. A sustained upward move in stainless steel or nickel will force either margin compression or elevated retail price increases; both outcomes require different tactical responses.
-
Product‑safety and regulatory scrutiny: High‑profile recalls accelerate retailer due‑diligence and increase insurance costs. Firms without rapid traceability and third‑party testing frameworks will face longer lead times for listings and higher compliance costs.
-
Trade and concentration risks: Current global manufacturing concentration creates vulnerability to geopolitical or logistics shocks. Diversification of manufacturing footprint, or contractual assurances with key suppliers, should be prioritized.
-
Channel shifts: Consumers continue shifting toward online and specialty lifestyle channels. Retailers and brands that optimize digital funnels, subscription models and premium channel experiences will capture disproportionate share of growth.
Practical 90‑day actions for executives planning 2026
-
Initiate a supplier stress‑test: map second‑tier suppliers, validate alternative sourcing, and lock short‑term hedges for critical metals where feasible.
-
Run a SKU profitability audit: identify low‑margin SKUs to rationalize and reallocate shelf / digital real estate to high‑return products.
-
Implement a recall readiness simulation with legal, quality and comms teams; ensure insurance and liability clauses are current.
-
Fast‑track premium lane pilots: test higher‑margin SKUs with differentiated finishes, warranty offers, and sustainability credentials via direct channels.
-
Evaluate strategic M&A targets: prioritize bolt‑on OEMs for capacity and regional reach, or niche premium brands to accelerate margin expansion.
How PW Consulting supports boardroom decisions in 2026
Beyond the published market study, PW Consulting offers executive workshops that translate the report’s scenario outputs into boardroom‑ready decisions: bespoke revenue and cost models, target screening for strategic acquisition, supplier renegotiation playbooks, and a regulatory‑compliance checklist tailored to your SKUs and geographies. Our deliverables are designed to move from insight to implementation within 60–90 days.
The full report contains the granular segmentation, SKU‑level proxies, channel elasticities and the proprietary heatmaps that clients use to quantify opportunity and risk. We intentionally omit those core subsegment tables from this preview to preserve the usable intelligence that guides tactical 2026 moves.
To obtain the full Worldwide Stainless Steel Vacuum Flask Market report, including the model files, scenario outputs and recommended implementation timeline, visit the PW Consulting report page or contact our industry team for a confidential briefing and an accelerated deployment package tailored to your firm’s exposure.
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Vacuum Flask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com