

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide FPD Lithography Systems Market Valued at USD 4,280.0 Million in 2025, Set to Reach USD 6,313.3 Million by 2032 at a 5.71% CAGR

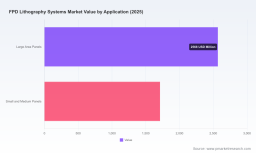
Worldwide FPD Lithography Systems Market: Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on Worldwide FPD (Flat Panel Display) Lithography Systems synthesizes empirical market trajectories, competitive signals and regulatory vectors to equip C-suite leaders and strategic investors as they set priorities for 2026. Built on a base year of 2025 with a historical window covering 2020–2025 and a forward forecast to 2032, the report quantifies the market and—just as importantly—translates change drivers into executable choices for procurement, partnerships, R&D and M&A. The top-line: the global market expands from an estimated USD 4,280.0 Million in 2025 to an expected USD 6,313.3 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.71% over the forecast period.
Space Chamber Market
Why this report matters for 2026 strategy
-
Timing decisions against a shifting investment cycle: Our analysis identifies a temporary industry pullback in 2026 as major panel manufacturers reassess capital deployments in light of recent tariff and trade-policy shifts. Firms that defer or accelerate purchases without scenario analysis risk either underutilized assets or lost time-to-market.
Worldwide Web Application Firewall (WAF) Software Market -
Regulation and compliance are now strategic levers: Cross-border export controls and chemical compliance frameworks are altering permissible buyer-supplier configurations and product specifications. Our regulatory overlay quantifies exposure to recent export-control expansions and ongoing EU chemicals regimes, enabling legal-informed procurement strategies.
Load Bank Rental for Data Centers Market -
Market concentration shapes negotiating power: The FPD lithography market demonstrates very high concentration at the vendor tier—our competitive concentration metrics highlight an industry where the top three suppliers command the vast majority of revenues. This structural reality changes counterparty behaviours, lead times, service economics and the shape of potential alliances.
Report highlights — what executives will find inside
-
Integrated market-sizing and trajectory modelling: We provide a reconciled historical series (2020–2025) and a granular forecasting engine for 2026–2032. The model embeds macro demand drivers, technology substitution effects and a supply-side capacity build, delivering scenario outputs aligned to strategic decision gates.
-
Scenario-based investment playbooks: Four investment scenarios—Consolidation, Acceleration, Wait-and-See and Regionalization—translate macro foresight into specific procurement and CAPEX timing recommendations. Each playbook includes risk-adjusted NPV sensitivity and break-even timing for major platform classes.
-
Technology and product roadmaps: We map technological inflection points (light sources, multi-lens optics, overlay precision) and their expected impact on yield, throughput and cost per panel. This section supports Make vs Buy debates and R&D prioritization.
-
Supply chain and localization diagnostic: The report contains supplier dependency matrices, single-source exposure heatmaps and practical mitigations—including contract clauses, strategic stocking, and dual-sourcing templates—tailored for 2026 procurement cycles.
-
Commercial and go-to-market playbook: For equipment vendors, we offer differentiated GTM options by customer archetype (leading integrators, high-mix panelmakers, and emerging local champions), supported by pricing levers and service-model optimization to defend margin in a concentrated industry.
-
M&A and partnership screening: The study identifies target profiles and valuation frameworks for bolt-on acquisitions, joint development projects and manufacturing partnerships—critical when incumbents look to expand adjacent capabilities or secure domestic supply in response to trade restrictions.
-
Regulatory compliance toolkit: Practical checklists, certification paths and compliance-cost scenarios are provided so procurement teams and legal counsel can quickly quantify the implications of export controls and hazardous-chemical restrictions on planned purchases.
Competitive landscape — interpreting the signals
The market’s oligopolistic structure concentrates strategic focus on a small number of vendors and a rising cohort of domestic challengers. PW Consulting’s competitive analysis highlights three archetypal players shaping 2026 decision contexts:
-
Nikon Corporation (Tokyo, Japan): A technology leader in multi-lens FPD lithography, Nikon’s recent product activity signals a push to optimize power consumption and high-definition yields. Notably, Nikon announced order acceptance for Gen 8 systems equipped with UV-LED sources in late 2025 and is positioning shipments in early 2026. Nikon’s cross-application capability—translating multi-lens expertise into back-end semiconductor patterned tools—adds strategic optionality for buyers seeking multi-purpose platforms.
-
Canon Inc. (Tokyo, Japan): Canon’s mirror-projection platforms remain a mainstay for array and color-filter processes. Recent product releases demonstrate an emphasis on overlay accuracy and throughput for mid-size automotive and smartphone panel production. Canon’s established aftermarket and service footprint make it a partner of choice for clients prioritizing lifecycle uptime.
-
Shanghai Micro Electronics Equipment Co., Ltd. (SMEE) (Shanghai, China): As domestic industrial strategies intensify, SMEE represents an emergent onshore supplier option. Buyers weighing localization and trade-risk mitigation should evaluate trade-offs across performance, lead times and compliance certifications when considering domestic alternatives.
While these firms’ product announcements and launch timelines are shaping 2026 procurement calendars, buyers must weigh product performance against availability constraints and regulatory permissibility. PW Consulting’s vendor-performance matrices and supplier risk scores are built precisely to support that evaluation process.
Regulatory and geopolitical dynamics affecting 2026
-
Expanded export controls: U.S. export regulations issued in late 2024 broadened controls on advanced lithography components and certain DUV and packaging tools. Aligned policies from other technology-exporting governments have created an uneven ability to move equipment and components across borders—this affects which suppliers can serve which customers in 2026, and at what cadence.
-
Japan’s export policy alignment: Japanese export controls have tightened in step with allied policies, introducing additional procedural requirements for specific categories of lithography hardware and subsystems.
-
Chemicals and environmental compliance: EU-level chemical frameworks continue to constrain material choices for certain process chemistries, raising compliance costs and sometimes forcing design or consumable changes that affect operating expenditure models.
-
Policy-driven investment pauses: Public commentary from major vendors and public filings indicate a near-term investment appraisal by panel manufacturers—this temporary contraction in 2026 demand creates a window for re-negotiating procurement terms and for opportunistic strategic positioning.
Strategic implications and actionable recommendations for 2026
-
Adopt a dual-track procurement strategy: Prepare a primary procurement timeline aligned to your technology roadmap but maintain a contingency queue with alternative suppliers or deferred delivery options. Use contractual instruments that convert cancelled firm orders into priority scheduling once demand recovers.
-
Quantify regulatory exposure up-front: Map each planned purchase against export-control matrices and chemicals compliance checklists to avoid costly retrofits or shipment denials. Incorporate regulatory clause templates into supplier contracts to share compliance risk.
-
Pursue strategic co-development where feasible: For OEMs and panelmakers seeking differentiation, partnering with suppliers on light-source upgrades or overlay enhancements can accelerate access to performance gains while improving supply resilience.
-
Leverage the temporary 2026 slowdown: Buyers with secure order books should negotiate extended service packages and supplier-managed spare pools at favorable economics; investors should scan the market for consolidation opportunities when valuations recalibrate.
-
Prioritize lifecycle economics: Move beyond unit prices to holistic cost-of-ownership models that include energy consumption (a growing differentiator), yield impacts and uptime penalties. Our model translates these inputs into comparable TCOs across vendor platforms.
What we withhold publicly — and how to get it
PW Consulting follows a “trailer” approach in this release: we present the analytical framework, market trajectory and strategic implications to support executive decisions, while reserving granular segment-level allocations and proprietary vendor share detail for subscribers. The report contains detailed splits by region, platform type and application, plus transaction-level vendor share tables that underpin the concentration metrics referenced above. These detailed tables and the interactive forecast model are accessible via the report landing page for clients and registrants.
Conclusion — positioning for 2026
FPD lithography systems sit at the intersection of rapid technological evolution, concentrated supplier power and intensifying regulatory oversight. For 2026, the dominant themes are timing, regulatory alignment and resilience. Organizations that deploy scenario-aligned procurement playbooks, couple technology roadmaps with supplier risk mitigation, and use the temporary market recalibration to optimize lifecycle economics will emerge with structural advantage as demand resumes. PW Consulting’s Worldwide FPD Lithography Systems Market report empowers those decisions with validated market sizing (USD 4,280.0 Million in 2025 growing to USD 6,313.3 Million by 2032 at a 5.71% CAGR), concentration analytics, and actionable playbooks—supporting senior leaders as they navigate 2026’s strategic inflection points.
For full access to segmented data, vendor-specific tables, scenario models and the downloadable forecasting workbook, please visit the official report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide FPD Lithography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com