

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Main-Chain Liquid Crystalline Polymer Market to Reach USD 2.42 Billion by 2032, Growing at a 7.42% CAGR

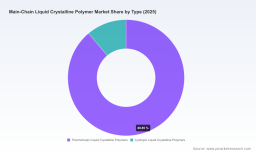
Main-Chain Liquid Crystalline Polymer Market: Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
The main‑chain liquid crystalline polymer (LCP) market is moving from niche high‑performance applications into a phase of broad strategic importance for electronics, mobility and industrial OEMs. Our market model shows the global market expanding from approximately 1,024 million USD in 2020 to 1,466 million USD in 2025, and—under our central scenario—reaching roughly 2,420 million USD by 2032. That trajectory represents a sustained compound annual growth profile (CAGR) of about 7.42% through the forecast window. Concentration metrics also signal a market where scale and technical differentiation matter: the top three suppliers control a material majority of market share, and the top five approach an overwhelming near‑80% share. For 2026 planning cycles, these dynamics create a narrow window to align sourcing, product strategy and investment timing to avoid being locked out of critical supply and qualification pathways.
Ultrasonic Box Nailer Market
Why 2026 is a pivotal year
- Qualification inflection: OEMs in electronics, automotive electrification and aerospace are tightening qualification corridors for polymer families. The combination of longer testing cycles (driven by regulatory scrutiny) and demand pull from miniaturization and higher operating temperatures means manufacturers must commit to supplier roadmaps earlier to secure next‑generation components.
- Supply chain squeeze: Specialty monomers and feedstock constraints have become a recurrent theme. Limited global supply of purified monomers and batch polymerization characteristics create price volatility and lead times that can materially affect project economics if not hedged through contracts or strategic stockpiles.
- Premium positioning and cost‑to‑serve: Main‑chain LCPs trade at a structural premium—roughly on the order of double high‑temperature nylons—reflecting complex production routes and specialty inputs. That pricing dynamic has implications for value capture, contract negotiation and the economics of substitution versus redesign.
- Regulatory and sustainability acceleration: Updated regulatory frameworks in major markets are extending qualification and disclosure requirements for novel polymer grades. Parallel policy drivers are pushing for traceability, safer chemistries and certified green feedstocks, shifting supplier selection criteria beyond price and into lifecycle performance.
What PW Consulting’s Main‑Chain LCP report delivers (practical, action‑oriented components)
This is not an academic exercise—our report is built to be operational in 2026 decision cycles. Highlights of the practical deliverables include:
Alloy Steel Chains Market
- Robust market model and scenario suite: A multi‑scenario demand engine covering technology adoption curves, end‑market substitution risks, and sensitivity to raw‑material shocks; outputs are provided in downloadable, client‑ready workbooks to support internal planning and board materials.
- Forward pricing and margin model: Granular cost‑builds and margin scenarios incorporating specialty monomer availability, energy cost pass‑throughs, and contract structures (spot, index, long‑term), enabling CFOs to stress‑test P&L impacts under multiple supply scenarios.
- Qualification timeline maps: Practical gating criteria and typical timelines for grade qualification across key OEM segments, with recommended accelerants (pilot runs, co‑development agreements, third‑party validation partners) to compress time‑to‑market.
- Supplier and capability matrix: A strategic supplier map that scores companies on production footprint, technical depth, sustainability credentials and capacity flexibility—designed for procurement to prioritize strategic partners and design dual‑sourcing strategies.
- Technology and product roadmap playbooks: Comparative analysis of thermotropic and lyotropic main‑chain approaches, film versus molding applications, and options for hybrid solutions—plus recommended R&D focus areas with potential ROI windows.
- M&A and partnership screens: Target lists and valuation heuristics for acquisition, minority investments and JV structures aligned to accelerate market entry, access to feedstocks, or capability acquisition (e.g., precision molding, films, battery insulation technologies).
- Risk register and mitigation plans: Practical mitigation for raw material volatility, regulatory lag, and reputational risks from chemical policy shifts—complete with recommended contracting clauses and insurance structures.
To preserve the value of proprietary segmentation and the precise forecasts that underpin supplier selection and M&A screens, we intentionally withhold detailed sub‑segment financials in this release. The full report contains those data tables and interactive models for enterprise use.
Oxide Transparent Ceramics Market
Competitive landscape: who matters and why
- Celanese Corporation (Dallas, Texas): Known for branded LCP lines and engineered compounds that balance flow, heat resistance and dimensional stability—a strategic player in high‑volume electronics and connector markets. Recent capacity additions in China reflect a move to secure local supply for 5G and adjacent electronics demand.
- Polyplastics Co., Ltd. (Tokyo): A precision‑molding oriented supplier that has broadened its portfolio with biomass‑balanced variants, signaling near‑term differentiation on sustainability credentials and supply chain traceability.
- Sumitomo Chemical Co., Ltd. (Tokyo): A major incumbent that has used M&A to consolidate capabilities, recently acquiring LCP neat resin assets to strengthen its ICT and mobility offerings—underscoring a strategy of vertical integration into high‑growth end‑markets.
- Toray Industries, Inc. (Tokyo): A focus on films and high‑frequency applications gives it an edge in advanced electronics and RF components, an area that will be critical as device speeds and thermal loads increase.
- Solvay S.A. (Syensqo) (Brussels): Offers high‑heat and flame‑retardant grades targeting EV battery insulation and industrial applications—an example of product differentiation to address emerging electrification needs.
- Specialist producers (e.g., Ueno Fine Chemicals, Kuraray): Niche capabilities in high‑performance engineering plastics, films and fibers that serve specialized component makers and offer potential acquisition or partnership targets for scaling OEMs.
Recent strategic moves—capacity expansion in China by a global supplier, a biomass‑balanced product launch from a Japan‑based specialist, and a targeted acquisition to consolidate resin assets—illustrate three clear competitive playbooks: scale via capacity, differentiate via sustainability, and consolidate via inorganic growth. For buyers and investors, understanding which supplier follows which playbook is essential for alignment on risk and long‑term support.
Supply chain and raw‑material dynamics
- Monomer availability: Purified terephthalic acid derivatives and specialty hydroxybenzoates are often produced by a narrow set of chemical manufacturers. Disruptions, capacity constraints or quality variability can disrupt full value chains; securing long‑dated offtake or strategic stock positions is therefore a pragmatic step.
- Pricing mechanics: Batch polymerization, specialized purification steps and limited producer competition result in a structurally higher cost basis—suppliers generally command a premium versus commodity high‑temperature polymers. Buyers must model premium capture and the elasticity of demand based on substitution and redesign costs.
- Options to manage risk: Near‑term levers include long‑term supply agreements, collaborative R&D to enable alternative monomer routes, and localized inventory strategies. Longer‑term levers include backward integration, joint ventures with monomer producers, or development of robust recycling loops to offset virgin feedstock exposure.
Regulation, sustainability and the qualification curve
- Regulatory tightening: Recent updates to U.S. TSCA review rules and ongoing EU REACH workstreams increase testing and disclosure obligations for novel grades, extending qualification timelines and raising the upfront compliance cost for new entrants.
- Sustainability as a selection criterion: Policies and buyer preferences increasingly favor traceability and circularity; mass‑balance biomass approaches and certified green feedstocks are emerging as commercially viable differentiators rather than peripheral marketing claims.
- Implication for product strategy: Suppliers that can demonstrate verified feedstock claims, reduced lifecycle impacts, and transparent supply chains will command preferential qualification opportunities with sustainability‑focused OEMs.
A pragmatic decision framework for 2026
2026 should be treated as a decision momentum year. The following prioritized activities will deliver asymmetric value:
- Near term (0–12 months): Lock preferred supply via hybrid contracts (mix of long‑term and flexible volumes), accelerate grade qualification with co‑development partners, and pilot biomass‑balanced or traceable feedstock pathways to signal compliance readiness to customers and regulators.
- Medium term (12–36 months): Execute capacity tie‑ups or JV structures where scale is needed; selectively pursue M&A to acquire missing capabilities (e.g., films, precision molding); and implement pricing strategies that capture structural premium without compromising adoption.
- Long term (>36 months): Invest in circularity (recycling, monomer recovery) and R&D into alternative monomer chemistries that reduce supply dependence and enable new price points. Build multi‑tier supplier ecosystems to mitigate single‑source risks.
How PW Consulting helps operationalize the insights
Our Main‑Chain LCP market study is designed to convert market intelligence into executable moves for procurement, product strategy, corporate development and R&D. The report packages include interactive models, supplier scorecards, qualification pathway templates, CapEx ROI tools and an M&A target shortlist tailored to specific corporate profiles (e.g., OEM, compounder, monomer producer). For procurement teams, we provide negotiation playbooks and contract clauses; for product teams, we offer technical readiness matrices and pilot deployment plans.
To preserve the commercial value of the dataset and to ensure aligned use across enterprise stakeholders, this announcement intentionally refrains from publishing the detailed segment‑level financial tables and regional/application splits included in the full study. If your 2026 strategy depends on precise segment forecasts, supplier share scenarios or tailored M&A screening, the full report and accompanying client workbooks provide those deliverables with licenseable access.
Final takeaways
- The main‑chain LCP market is entering a structurally attractive phase with sustained growth and concentrated supplier power; strategic moves made in 2026 will determine supplier relationships, margin capture and product roadmaps for the rest of the decade.
- Successful players will combine tactical procurement (to manage supply and price exposure), targeted investments (to secure capacity or capability), and sustainability‑driven differentiation (to meet regulatory and customer demands).
- PW Consulting’s study translates these dynamics into actionable plans, models and tools that align board‑level strategy with plant‑floor execution—without compromising the proprietary segmentation and datasets that drive competitive advantage.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com